
Will AI Slowdown Calls Change AMD Stock Narrative
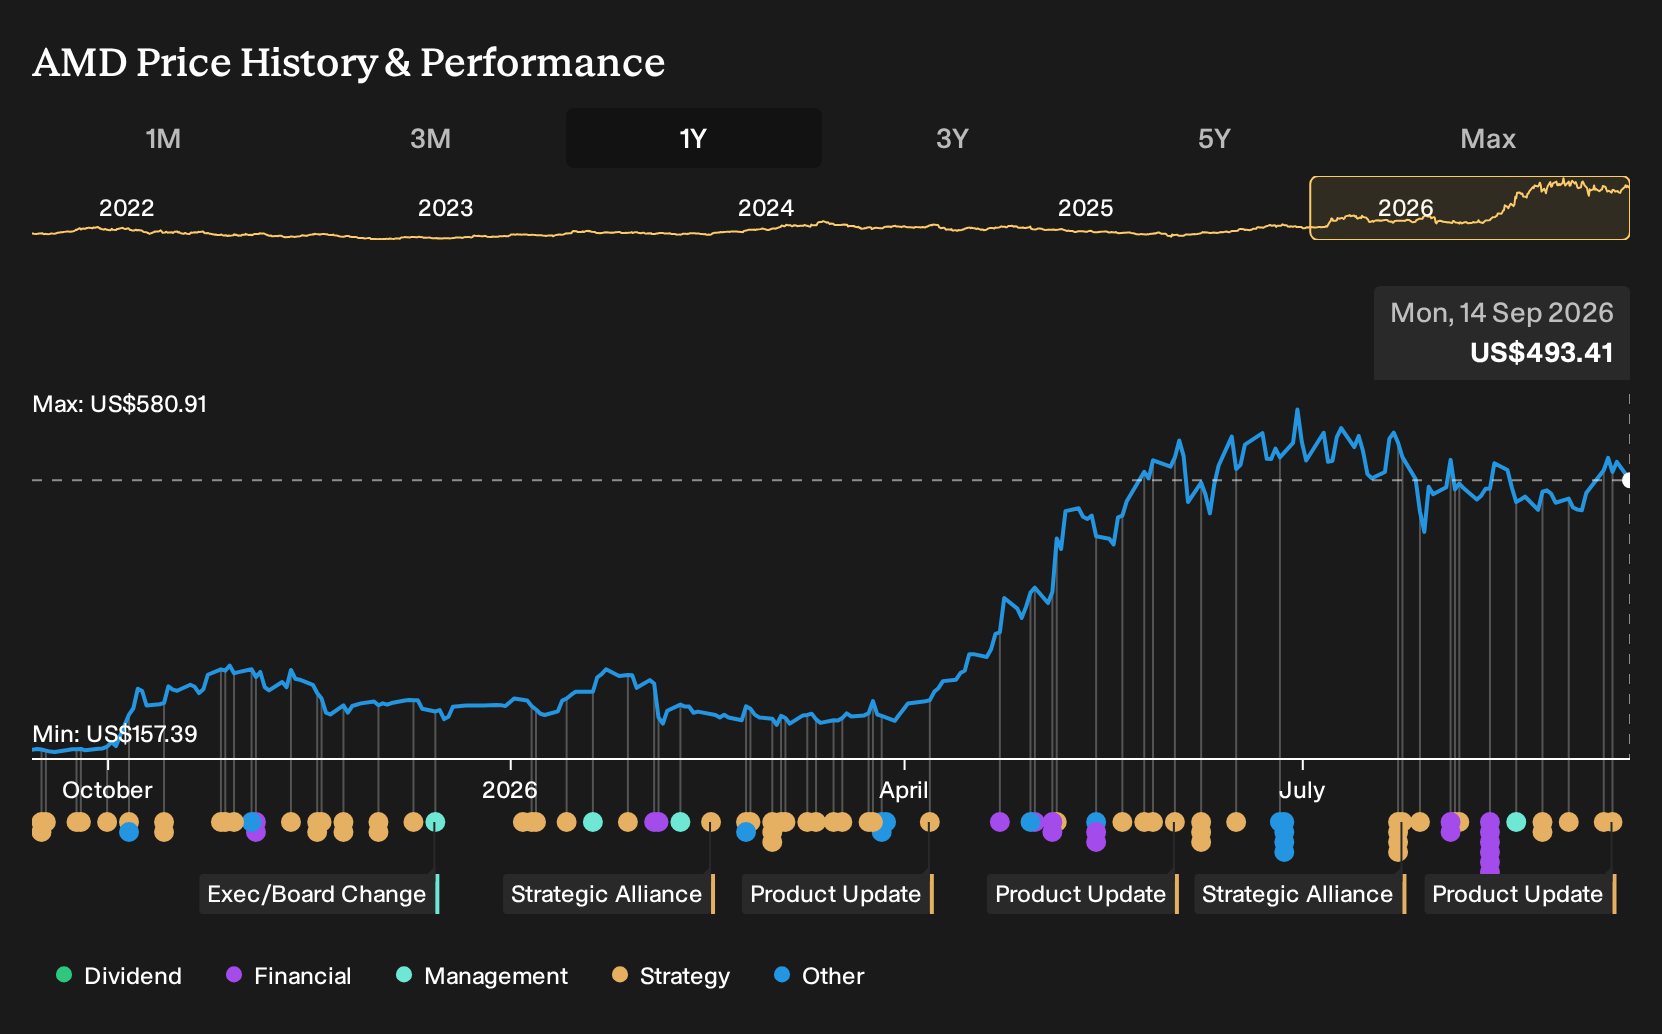
- Advanced Micro Devices was caught in a broad sell-off in AI and semiconductor stocks after leading AI executives publicly urged a coordinated slowdown in frontier AI development, raising questions about future demand for data center and AI infrastructure hardware.
- The pullback highlights a gap between AMD’s strong AI product momentum and sector-level worries that regulatory or safety-driven pauses could affect how quickly customers commit to large accelerator and server rollouts.
- Next, the focus shifts to how AMD’s investment narrative around AI and data center growth compares with these AI safety driven demand concerns.
Scan how other AI hardware and infrastructure plays are reacting to the same safety headlines by running your eye over 60 AI infrastructure stocks as you assess where AMD now fits in the story.
Advanced Micro Devices Investment Narrative Recap
To own Advanced Micro Devices, you need to believe its AI and data center engine, from EPYC CPUs to Instinct accelerators and future MI350 and MI400 parts, can keep pulling more workload share from cloud and enterprise customers. The key near term catalyst is execution on that AI ramp and keeping gross margins healthy while R&D stays heavy.
The sharp AI safety headlines and sector sell off have mostly hit sentiment rather than AMD’s order book so far, so the bigger risk still sits in execution and competition. Any stumble on Helios, MI400, or ROCm adoption, or pricing pressure from rivals, would be most painful given the premium valuation.
The quantum networking tie up with Xanadu around the Backline platform is the announcement that best matches the current AI debate. While the market focuses on model size and training limits, this project focuses on infrastructure and on how quickly classical AMD compute can talk to quantum hardware using the PennyLane software stack as the control layer.
For you, the relevance is straightforward. If quantum and classical systems start to be treated as one distributed fabric, the bar for AMD’s latency, software ecosystem, and data center roadmap rises. That creates another execution swing factor on top of Helios and MI400, but it also adds a new potential source of accelerator demand if the concept gains traction.
Advanced Micro Devices' narrative projects US$137.4b revenue and US$38.5b earnings by 2029. This assumes 49.3% yearly revenue growth and an earnings increase of about 6x from US$6.5b today.
Uncover why Advanced Micro Devices' fair value signals a 22% potential upside to its current price, a discount that could close quickly.
Exploring Other Perspectives
Some of the lowest AMD analysts fixate on export controls as the swing factor. They already penciled in 32.2% annual revenue growth and US$23.8b earnings by 2029, far below the consensus US$38.5b path. With fresh AI safety headlines and the Backline quantum link, those cautious views could shift again. Use them as contrasting reference points, not as a script.
Explore 27 other Advanced Micro Devices fair value estimates, including one that suggests as much as 46% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider performing your own analysis.
- A great starting point for your Advanced Micro Devices research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Advanced Micro Devices. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Advanced Micro Devices' overall financial health at a glance.
Looking For More Investment Ideas Beyond Advanced Micro Devices?
Once you have a view on Advanced Micro Devices, it can help to consider it alongside other opportunities with different risk and income profiles. The Simply Wall St Screener lets you scan the market quickly and then go deeper only where the story makes sense for you.
- If you care most about resilience and capital preservation, start with a group of 11 resilient stocks with low risk scores that score well on stability and risk metrics.
- For potential mispriced opportunities, compare AMD with a broader pool of 34 high quality undervalued stocks that pair healthier balance sheets with stronger cash generation.
- If income matters to your plan, round out your watchlist with 6 dividend fortresses that combine higher yields with a focus on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com