
Is Kennametal (KMT) Stock Still Reasonable After A 45% Run?
Kennametal has delivered a strong share price run over the past year, which naturally puts the focus on what investors are paying for its earnings today. With the stock recently closing at US$29.31, the question now is how well that tag lines up with the profits the business is generating.
- The share price has risen 44.9% over the past year, which raises the stakes on whether the current valuation is still grounded in its earnings power.
- The company’s value story rests heavily on how consistently it can convert its industrial tooling and wear solutions business into earnings, since that drives both its P/E multiple and the cash it has available for reinvestment or returns to shareholders.
- The analysts covering Kennametal have run their own numbers. See what analysts think Kennametal's shares could be worth.
For investors, the debate is whether Kennametal’s current share price is adequately supported by the earnings it produces today and what the market expects it to earn next.
If you want to explore the same earnings question you are asking of Kennametal across a wider set of opportunities, take a look at 34 high quality undervalued stocks.
Is Kennametal Still Cheap on Earnings?
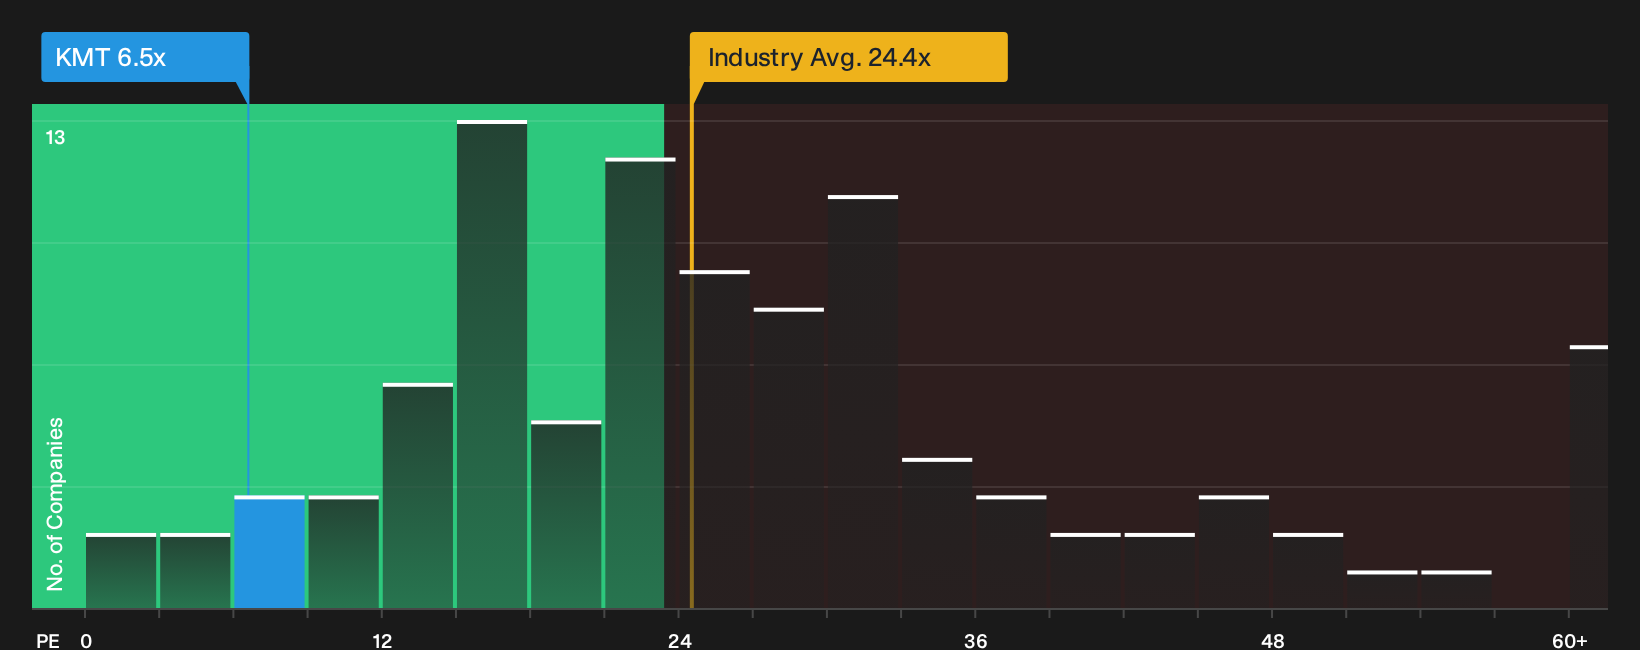
The P/E ratio fits Kennametal because investors are mainly weighing what they are paying for each dollar of current profits. On that front, the stock trades on roughly 6.5x earnings, which is far below the Machinery industry average of about 24.4x and also well under the broader peer group near 35.5x.
The fair P/E that would be expected for Kennametal, based on factors like its sector, profitability profile, size and risk, sits meaningfully higher than where the shares trade today. That gap means the current multiple points to an undervalued earnings stream on this framework, although any judgement still hinges on how durable you think those profits are through a full cycle. Explore the numbers behind Kennametal's P/E valuation.
The Kennametal Narrative: What Would Justify Today's Price?
Kennametal Narratives on Simply Wall St pick up where the P/E puzzle leaves off by spelling out what kind of future growth, margins and earnings would need to play out for the current share price to look materially higher or lower. Each scenario ties its number to a clear view on how Kennametal's growth profile, profitability and risk picture could shift, which you can revisit as fresh company results and new information emerge on the Community page.
Investors in Kennametal are split between those who see disciplined execution creating more value from here and those who think the tungsten uplift has already done the heavy lifting.
Bull case: 11% undervalued
"Kennametal is investing in product innovation and digital transformation initiatives (such as partnerships in advanced toolpath software and specialized solutions for AI data centers and EVs), creating new avenues for higher-margin growth and improved earnings quality..."
Discover why this Narrative puts Kennametal at 11% undervalued.
Bear case: 9% overvalued
"Higher tungsten prices and tariffs are being offset with price and surcharges today, If raw material costs stay elevated while customers resist further increases, pricing power could weaken and compress gross margin and adjusted EBITDA margin..."
Explore why this Narrative puts Kennametal at 9% overvalued.
Before you focus on Kennametal’s valuation, check what could trip it up
Kennametal’s price tag and earnings profile tell only part of the story, because recent research has also highlighted specific business risks that could change how you view the stock. Take a closer look at 4 warning signs (2 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com