
TFI International (TSX:TFII) Could Be 21% Undervalued On Strong Q2 Earnings And Dividend Rise
TFI International (TSX:TFII) is back in focus after reporting a 39% jump in Q2 2026 net income, lifting its quarterly dividend and pairing that with an optimistic earnings outlook for the next quarter.
Recent price action shows that momentum in TFI International has cooled in the short term, with a 30-day share price return down 8.7% and a 90-day share price return down 9.1%. This comes even as the year-to-date share price return sits at 26.9% and the 1-year total shareholder return is 43.7%, supported by stronger earnings, a higher dividend and investor attention around events like the upcoming Morgan Stanley conference appearance.
Spot opportunities that follow similar earnings and dividend stories as TFI International by scanning our curated list of 3 high quality undervalued stocks.After that surge in earnings and a sharp run over the past year, the pullback in TFI International leaves a simple fork in the road. Is most of the upside already cashed in, or does value still remain?
Most Popular Narrative: 21% Undervalued
On the most followed view of TFI International, a fair value near CA$236 sits well above the last close at CA$185.79, which puts the recent pullback in a very different light.
Strong free cash flow generation supported by disciplined CapEx, cost controls, and effective working capital management is enabling accelerated share buybacks and ongoing dividends, driving per-share earnings growth independent of the near-term revenue environment.
See why 51 investors see TFI International as 21% undervalued.
Result: Fair Value of CA$236 (UNDERVALUED)
Still, the bullish case for TFI International hinges on freight conditions and execution in U.S. LTL. Weak demand or slower pricing progress could quickly challenge this 21% undervalued view.
Find out about the key risks to this TFI International narrative.
Another View: TFI International Through The P/E Lens
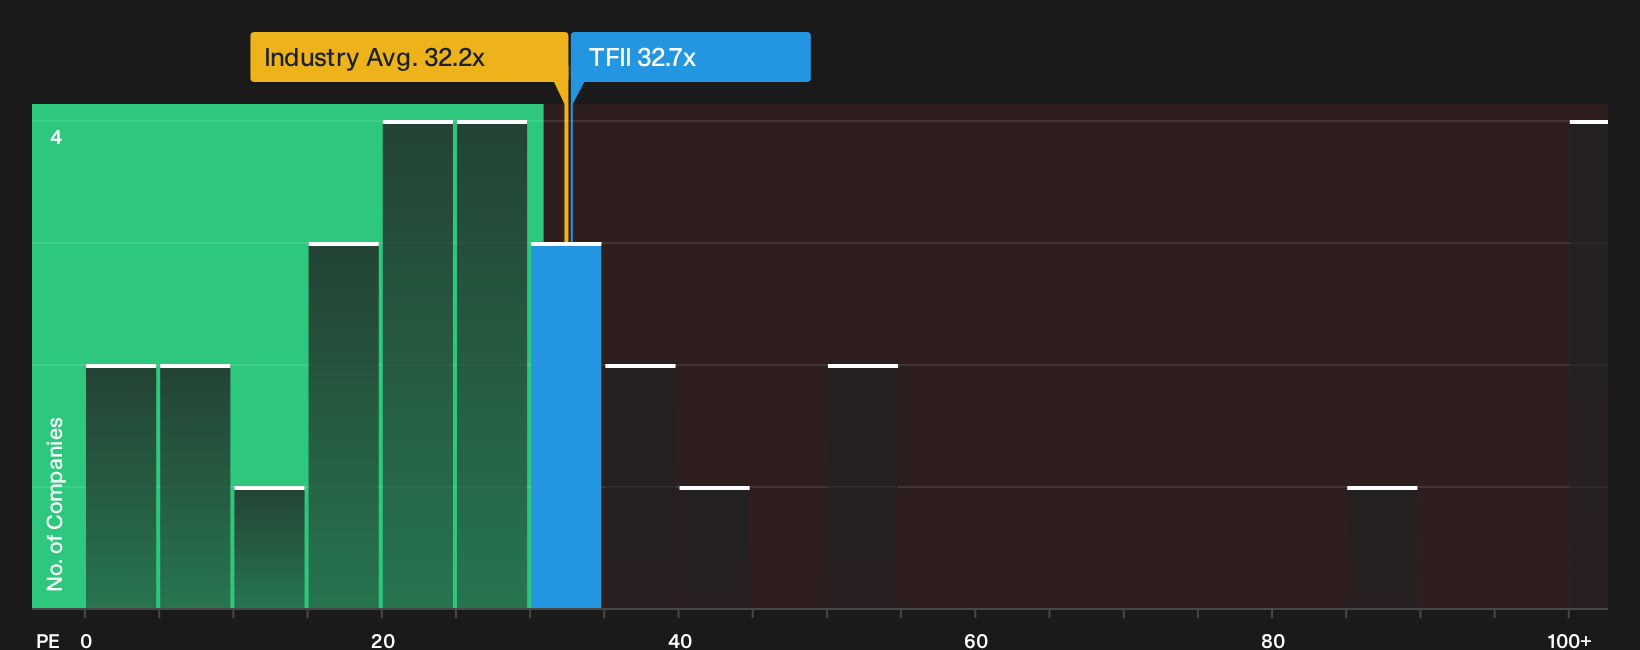
The first take frames TFI International as 21% undervalued, yet the market multiples tell a tougher story. On a P/E of 32.7x, the stock trades above both peer levels at 23.7x and an estimated fair ratio of 27.4x, which points to valuation risk if expectations cool.
For investors weighing that gap against the bullish fair value work, the question is simple: Is the current price paying up for execution that still needs to be delivered, or is this just the entry ticket for a quality freight operator on a good run?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around TFI International can feel confusing, so move quickly to inspect the underlying data, pressure test the bullish and bearish angles, and weigh both the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond TFI International?
If TFI International has your attention, use this moment to widen your watchlist, compare different setups, and pressure test your thesis across other opportunities.
- Target resilient income by scanning companies that offer reliable payouts through our 2 dividend fortresses.
- Hunt for mispriced quality by tracking financially solid businesses trading below their implied value using the 3 high quality undervalued stocks.
- Spot stronger balance sheets by filtering for companies with robust financial footing through the list of solid balance sheet and fundamentals (7 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com