
Is Mobility Global (MBGL) Fully Valued After Fresh Rideshare Recall Data?
Fresh CARFAX data on unfixed safety recalls in taxis and rideshares has pushed Mobility Global (MBGL) into focus, as investors consider how its vehicle lifecycle analytics might intersect with growing scrutiny on ride safety.
Recent trading paints a mixed picture for Mobility Global, with the share price at US$20.34 after a modest 1-day share price return of 0.39%, a 7-day share price return that declined 0.88%, and a year-to-date share price return that slipped 3.12%. This suggests momentum has softened even as fresh recall data keeps the story in play.
Scan beyond Mobility Global and compare how rideshare safety and recall exposure stack up across a curated list of 11 resilient stocks with low risk scores that may better align with your risk tolerance.
With Mobility Global drifting slightly this year yet tied to a fresh recall story, the real tension is simple. Is it worth stepping in at US$20.34 now, or waiting for a cleaner entry point as valuation comes into focus next?
Price-to-Earnings of 29.3x for Mobility Global: Is it justified?
Valuation work on Mobility Global leans heavily on its P/E of 29.3x, which sits above both peers and the wider US Professional Services group, even with the share price at $20.34.
The P/E ratio compares the current share price to earnings per share. For a data and analytics business like Mobility Global, that figure often reflects how much investors are willing to pay today for each dollar of forecast profit, especially when earnings are expected to change over time.
Analysts expect earnings to grow 14.8% per year and revenue 7.4% per year, which is slower than the broader US market forecasts in both cases. That combination suggests the current P/E assumes a fair amount of future progress, even though recent profit growth was affected by an $84.0m one off loss and net profit margins eased from 12.7% to 11.3%.
Relative to peers, the gap is clear. Mobility Global trades on a 29.3x P/E compared with a 23.5x peer average and a 22.1x average for the US Professional Services industry. This implies investors are paying a premium multiple despite lower forecast growth and a currently low 2.1% return on equity that is projected to remain low at 3.9% in three years.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 29.3x (OVERVALUED)
Still, the recall spotlight could fade quickly if regulators or rideshare platforms change reporting rules. This would blunt interest in Mobility Global’s data edge.
Find out about the key risks to this Mobility Global narrative.
Another View on Mobility Global’s Value
The P/E work suggests Mobility Global trades rich, yet the SWS DCF model tells a very different story. At $20.34, the stock is indicated as trading around 51.8% below an estimated future cash flow value of $42.21. Which lens should matter more for you: earnings today or cash flows over time?
Look into how the SWS DCF model arrives at its fair value.
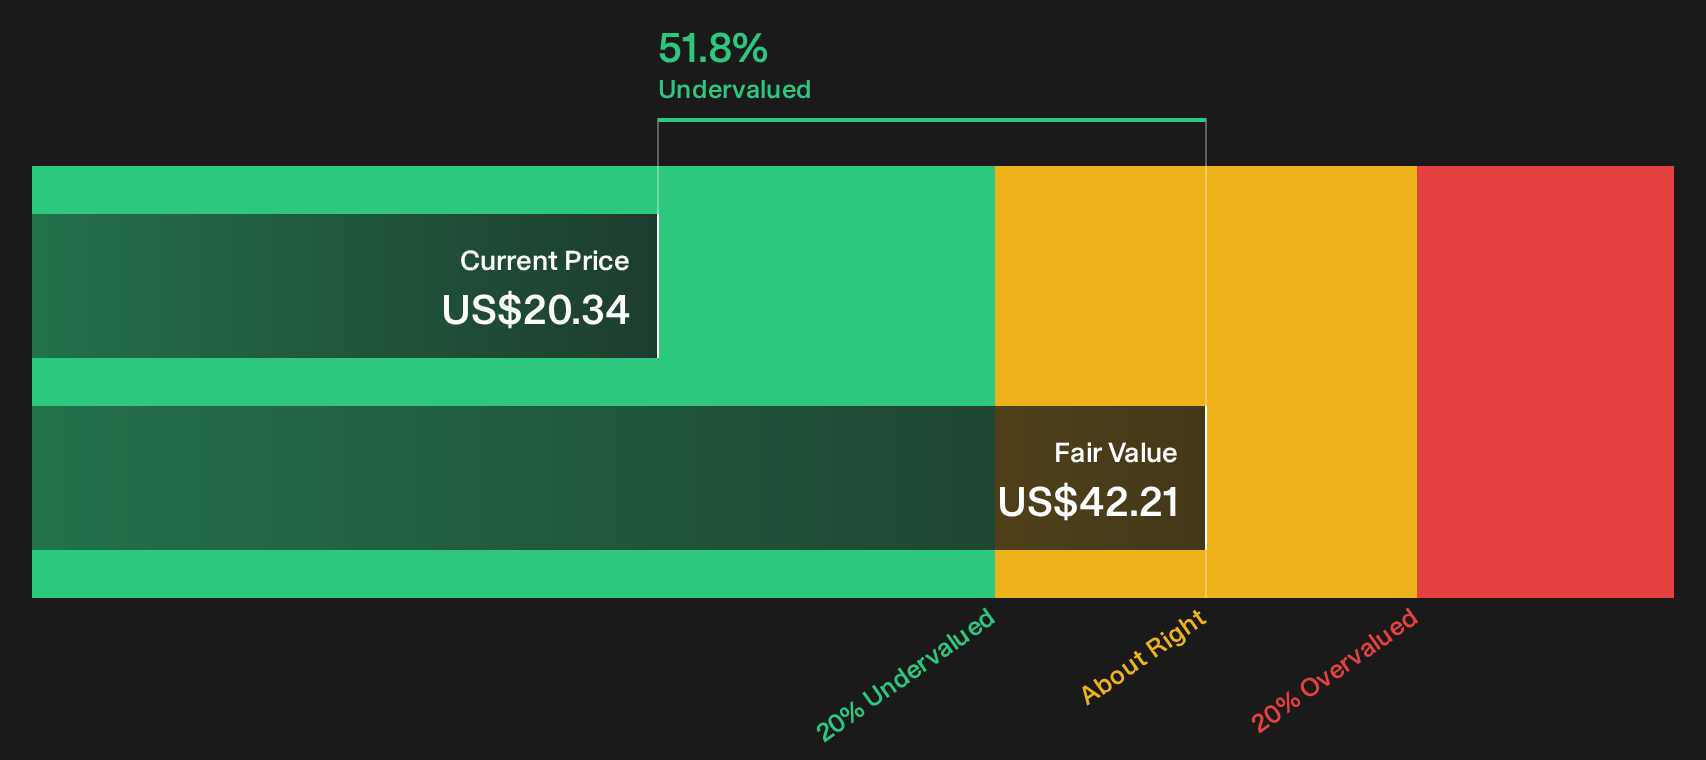
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Mobility Global for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With Mobility Global drawing both concerns and optimism in equal measure, the real edge comes from seeing the numbers yourself and acting before sentiment shifts. Take a closer look at the underlying signals and weigh the 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Mobility Global?
If Mobility Global has sharpened your focus on risk, valuation, and quality, do not stop on a single ticker. Broaden your watchlist before the next move passes you by.
- Target resilient balance sheets by scanning a list of solid balance sheet and fundamentals (22 results) that filters for companies with financial strength at the core of their story.
- Hunt for mispriced opportunities through a 34 high quality undervalued stocks that filters for strong fundamentals trading at what may be discounted prices.
- Prioritize reliable cash payouts with a 6 dividend fortresses focused on companies offering yields above 5% that aim to keep payments sustainable.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com