
Learn Why The Bull Case For Wix.com (WIX) Could Change Following AI Lawsuits
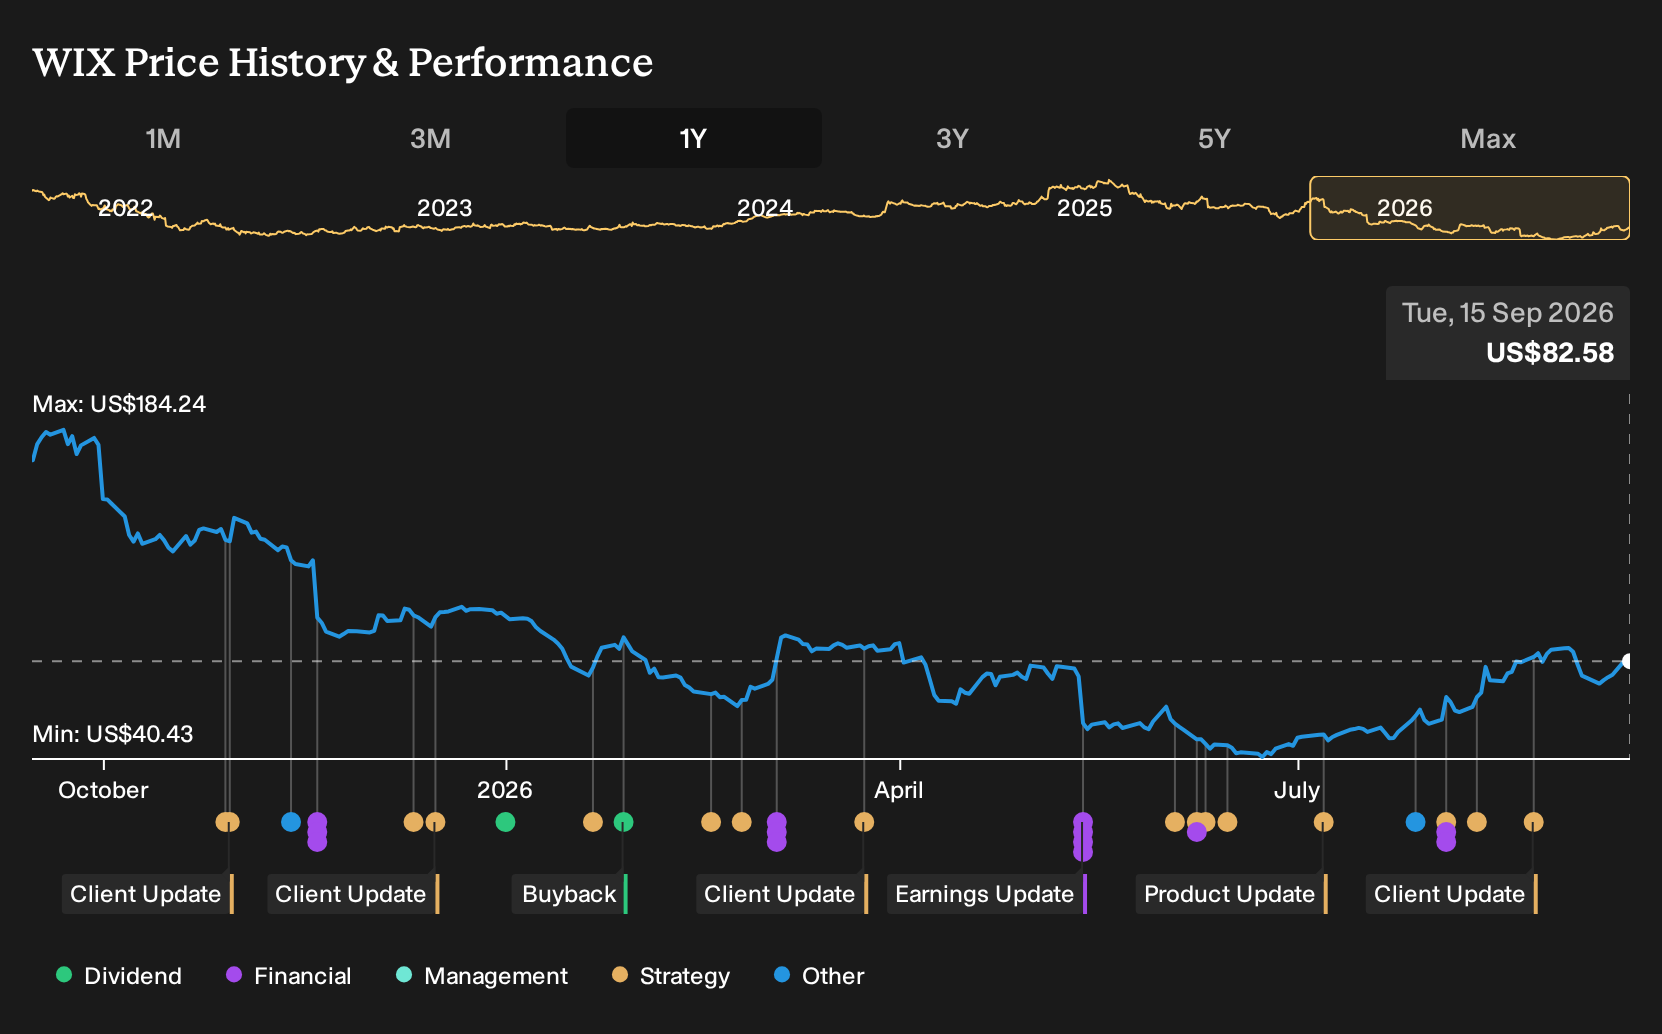
- Multiple law firms have filed or publicized securities class actions and investigations against Wix.com, alleging past misstatements about the competitiveness, costs, and financial impact of its AI products, including Base44 and Wix Harmony, following weaker than expected 2026 quarterly results and subsequent layoffs.
- The wave of litigation highlights how Wix.com's AI ambitions may be tied to heavier development and marketing spending, product gaps against rivals, and questions about whether the economics of its AI offerings match earlier expectations.
- We will now examine how Wix.com's investment narrative around AI driven growth and margins is challenged by allegations about AI product economics.
Wix.com Investment Narrative Recap
To own Wix.com right now, you need to believe its AI tools can still pull in new users, keep existing customers engaged, and eventually support cleaner profitability, even with higher R&D and infrastructure spending. The recent lawsuits focus on past statements rather than fresh product launches. As a result, the core near term catalyst remains execution on AI driven features and user monetization.
The biggest immediate risk sits around profitability pressure. Higher AI costs, competitive pricing, negative shareholders equity, and a volatile share price all raise the stakes if user growth or paid conversion slow. Litigation adds uncertainty, but the more practical swing factor is whether Wix.com can run AI heavy products without letting expenses outrun revenue.
The 2026 class action filings tied to Wix.com's AI products are the clearest recent development to watch. Several firms allege the business overstated the competitiveness and financial benefits of tools like Base44 and Wix Harmony while understating development and promotion costs, after weaker quarterly results and a sharp share price drop.
For you, the link to catalysts is straightforward. Wix.com is leaning on AI led user acquisition, higher conversion, and broader use cases such as app building through Base44 to support future earnings. Any litigation outcome that constrains how it markets these tools, or highlights sustained cost overruns, would weigh directly on that AI driven growth story.
Wix.com's narrative projects US$2.9b revenue and US$326.7m earnings by 2029. This assumes 12.5% yearly revenue growth and a substantial earnings increase from a loss of US$40.6m today.
Uncover why Wix.com's fair value indicates a 5% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
One alternate angle on Wix.com focuses on margin risk rather than AI driven upside. The most optimistic analysts were still working off profit margins rising from a loss of 8.2% today to 9.7% in three years, with about US$3.1b revenue and US$303.0m earnings by 2029. Those forecasts predate the lawsuits, so you should expect opinions to move and you may wish to explore several viewpoints before deciding how comfortable you feel with that margin story.
Explore 9 other Wix.com fair value estimates, including one that suggests as much as 147% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your independent analysis.
- A great starting point for your Wix.com research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Wix.com. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Wix.com's overall financial health at a glance.
Looking for more Wix.com investment ideas?
If Wix.com has put AI risk and reward on your radar, it can help to widen the lens and look at other listed businesses with different profiles using the Simply Wall St Screener.
- If you want steadier balance sheets to compare against Wix.com, start with a list of solid balance sheet and fundamentals (22 results) that already clear some key financial health checks.
- For investors who prefer a margin of safety on valuation, scan through 34 high quality undervalued stocks that combine quality metrics with pricing that screens as potentially attractive.
- If you are hunting for lesser known opportunities away from headline AI stories, browse 16 high quality undiscovered gems that pair strong fundamentals with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com