
Why Modine Manufacturing (MOD) Is Back In The Spotlight
Modine Manufacturing (MOD) has put a spotlight on its future direction by scheduling an Analyst and Investor Day in Chicago on 18 November 2026, following the planned spin-off of its Performance Technologies segment.
The recent pullback in Modine Manufacturing’s share price, with a 30-day share price return of 14.62% and a 90-day share price return of 36.99% in the red, contrasts with a year to date share price return of 27.03% and a three year total shareholder return of just over 3x. This points to longer term momentum while hinting that the planned spin off and upcoming Analyst and Investor Day are prompting investors to reassess near term expectations.
Scan beyond Modine Manufacturing and see how other capital goods players are being priced around similar inflection points with the hand-picked 34 high quality undervalued stocks.
Bulls point to Modine Manufacturing’s multi-year plan and upcoming spin off, while bears focus on the sharp pullback. Which side does the current valuation actually support as you weigh the next move?
Most Popular Narrative: 42% Undervalued
On the most followed view of Modine Manufacturing, a fair value of $310.29 sits well above the last close at $178.87. This puts the upcoming spin off and Analyst Day in sharp focus for anyone weighing that gap.
The accelerating build-out of data centers and the need for next-generation cooling solutions are driving extraordinary demand for Modine's products, with management forecasting the potential to double data center revenues from ~$1 billion in fiscal '26 to $2 billion by fiscal '28. This structural demand from digital infrastructure is set to materially boost revenue growth and deliver significant operating leverage over time.
See why 49 investors see Modine Manufacturing as 42% undervalued.
Result: Fair Value of $310.29 (UNDERVALUED)
Still, Modine Manufacturing’s significant data center build out and the integration of recent HVAC acquisitions leave execution risk on margins and cash conversion firmly on the table.
Find out about the key risks to this Modine Manufacturing narrative.
Another View On Modine Manufacturing’s Valuation
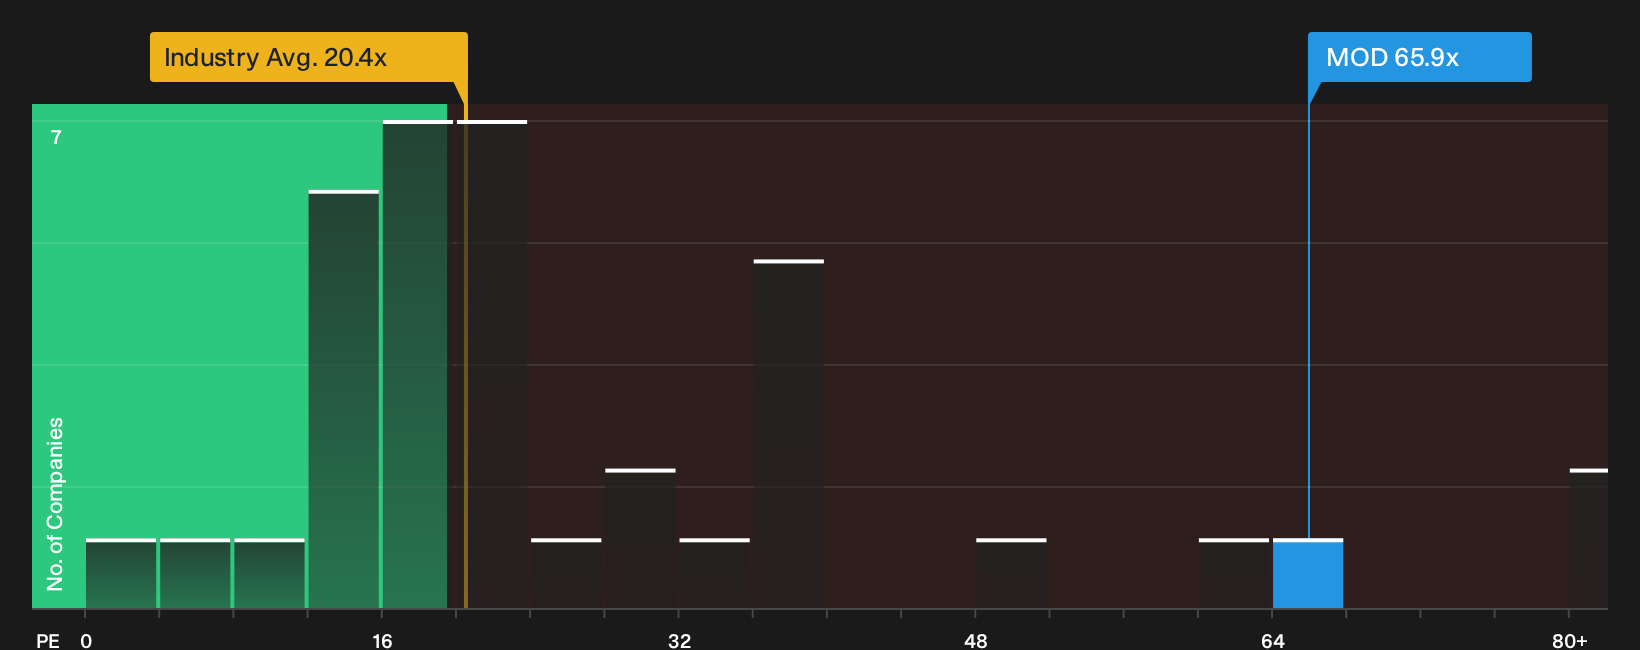
The most popular narrative leans on future cash flows and a fair value around $310, yet the current P/E of 65.9x tells a different story. That multiple is high compared with the US Building industry on 20.6x and peers on 22.6x, even if it is below the 73.3x fair ratio estimate.
For investors, that gap cuts both ways. A rich P/E relative to sector and peer averages can limit upside if sentiment cools. At the same time, a discount to the fair ratio hints at room for the market to move closer to those regression based levels. Which risk feels more real to you right now: overpaying on earnings, or walking away from a stock priced below its fair ratio target?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Modine Manufacturing can feel like both a warning and an opening. Move quickly, check the facts for yourself, and weigh the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Modine Manufacturing?
If Modine Manufacturing has sharpened your focus on valuation and risk, broaden your watchlist with a few targeted ideas that could round out your portfolio.
Use the Simply Wall St Screener to uncover fresh opportunities across different angles and avoid relying on a single story or sector.
- Target income resilience by scanning companies that have paid-up balance sheets and meaningful yields through the 6 dividend fortresses.
- Hunt for quality at a discount by zeroing in on companies our models flag as mispriced using the 34 high quality undervalued stocks.
- Tilt toward stability by filtering for businesses that carry lighter risk profiles with the 11 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com