
What Veeva Systems (VEEV)'s Amgen CRM Rollout Means For Shareholders
- Amgen recently announced plans to deploy Veeva Systems' Vault CRM globally, extending a decade-long collaboration and highlighting adoption of Veeva's Vault CRM Suite and Agentic Call Report to support engagement with healthcare professionals.
- Veeva Systems is pushing deeper into artificial intelligence with platforms such as Vault AI and Falcon, positioning its software as embedded workflow infrastructure for complex life sciences processes rather than just a traditional CRM tool.
- We will now look at how Veeva Systems' AI push, highlighted by Falcon, could reshape the broader investment narrative around the business.
Veeva Systems Investment Narrative Recap
To own Veeva Systems, you need to believe it can keep turning its position in life sciences software and CRM into steady, high quality earnings, while AI tools like Vault AI and Falcon deepen its role inside customer workflows. The short term swing factor is how quickly clients start using these agentic capabilities at scale. The Amgen rollout is useful proof of execution, but it does not radically change the near term trajectory on its own.
The biggest near term risk is simple. Large pharma customers might move more slowly than Veeva expects on AI heavy workflows, especially if decision cycles stay long or agentic tools feel disruptive to field teams. That would make the AI “incremental growth” story take longer to show up in bookings and could pressure returns on rising R&D and go to market spend.
The Amgen plan to deploy Vault CRM globally is the clearest operational tie in to Veeva Systems’ AI story right now. It directly touches the firm’s stated ambition to keep more than 70% of the life sciences CRM market over time and to use the Vault CRM Suite as the foundation for agentic commercial tools such as Falcon and the Agentic Call Report.
For you as an investor, the key question is whether deals like Amgen turn into broader suite usage, more Commercial Cloud subscriptions and measurable adoption of AI features such as Vault AI assistance and workflow automation. Execution risk sits around implementation complexity, customer concentration in top pharma accounts and the possibility that agentic fatigue or competing platforms from larger software vendors slow down follow on projects.
Veeva Systems' current earnings of $941.7 million are projected by analysts to reach $1.4b by 2029. This implies a revenue path that targets $4.7b in that same year, built on an assumed 12.7% yearly top line growth rate and an earnings increase of about $458 million from earnings today.
Uncover why Veeva Systems' fair value indicates a 6% potential downside to its current price, leaving little room for error.
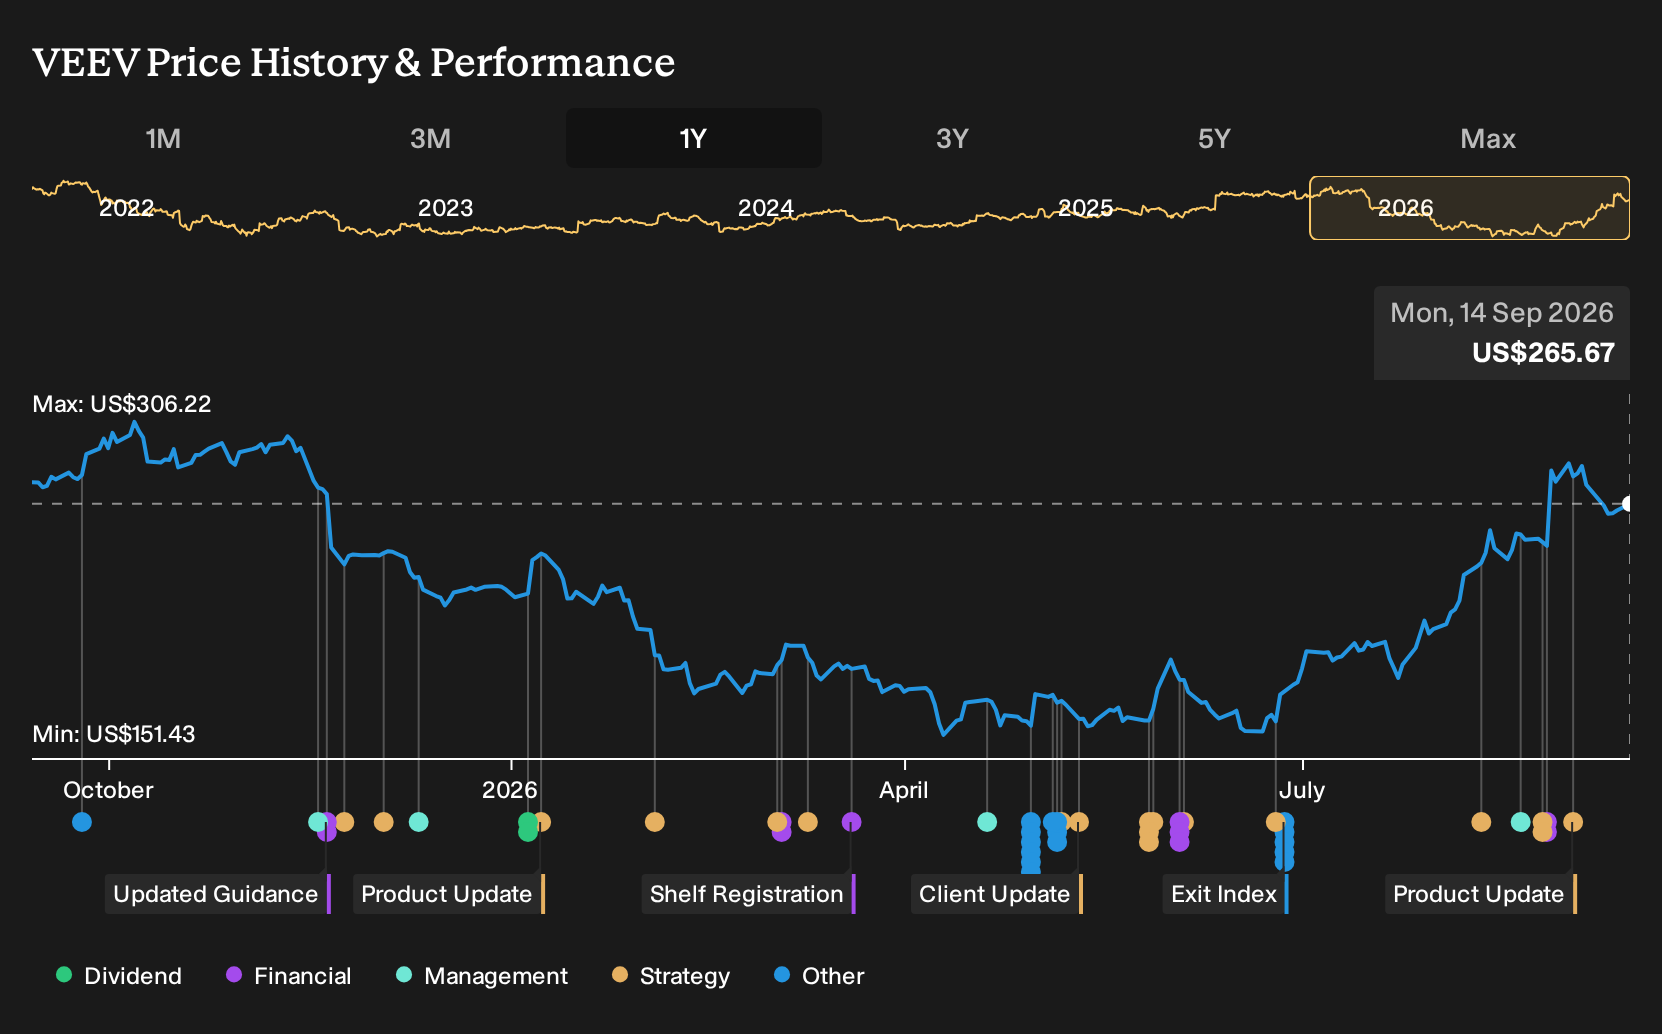
Exploring Other Perspectives
One alternate view anchors on Veeva Systems pushing beyond CRM. Bullish analysts looked for revenue of about US$5.0b and earnings near US$1.6b by 2029, based on wider adoption of Development Cloud, Quality and data products. Those forecasts came before the Amgen rollout, so this new contract could still reshape their story.
Explore 7 other Veeva Systems fair value estimates, including one that suggests as much as 44% potential increase from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Veeva Systems research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Veeva Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Veeva Systems' overall financial health at a glance.
Looking For More Ideas Beyond Veeva Systems?
If the Veeva Systems story has sparked fresh questions about where to put capital to work next, it can help to line it up against a broader watchlist of opportunities that match your risk profile, income needs, or quality threshold.
- If capital protection matters most to you, start with a set of 11 resilient stocks with low risk scores that score well on resilience and consistency.
- For investors hunting for mispriced quality, compare Veeva Systems with a curated 34 high quality undervalued stocks that pair solid fundamentals with more appealing entry points.
- Income focused readers who want cash returns alongside potential upside can review a focused group of 6 dividend fortresses that clear the 5% yield bar while aiming to keep payouts supported by fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com