
How MCT Joint Venture Will Impact Rush Enterprises Stock (RUSH.A) Investors
- Rush Enterprises recently completed a 50/50 joint venture with MCT Companies, adding a 17-location Carrier Transicold dealership and mobile service network plus reported quarterly revenue of $1.9b, a three-for-two stock split, and a higher dividend.
- The MCT Companies partnership brings refrigerated transport systems, rentals, and mobile service into the Rush Enterprises offering. This deepens its parts and service footprint across multiple states at a time when aftermarket support is a core earnings pillar.
- We will look at how the Rush Enterprises investment narrative around aftermarket strength and capital returns is shaped by the completed MCT venture.
Scan how Rush Enterprises’ refrigeration and service focus compares with other transport and industrial stocks by zeroing in on hand-picked opportunities in the list of solid balance sheet and fundamentals (22 results).
Rush Enterprises Investment Narrative Recap
Rush Enterprises appeals to shareholders who believe in a long runway for parts, service and related solutions tied to commercial trucking, with truck sales adding more cyclical upside on top. The biggest near term swing factor still sits in freight activity and fleet spending appetite. Weak freight or prolonged regulatory uncertainty can keep new truck orders cautious and limit upside from big ticket units.
The new MCT joint venture and recent $1.9b quarter emphasize the aftermarket and refrigeration angle, supporting the key catalyst of building more recurring service touchpoints rather than relying only on truck cycles. The largest risk remains sector wide pressure on freight demand and customer profitability. High leverage on the balance sheet can also amplify any downturn in volumes or margins.
The three for two stock split and higher dividend sit in the background of this story but still matter for investor perception. A split does not change Rush Enterprises' underlying value, yet it can improve trading liquidity and make the share price feel more approachable for smaller accounts.
The raised dividend, post split, reflects management confidence in the cash generation profile tied to parts, service and related offerings. For investors tracking catalysts, a sustainable payout combined with incremental growth from MCT can support a patient thesis, provided freight conditions and regulatory outcomes do not erode the earnings base that funds those distributions.
Rush Enterprises Forecasts Behind the MCT Story
Rush Enterprises' refrigeration build out through MCT is now being compared with analyst assumptions that revenue can grow by 10.0% a year over the next few years, with profitability expected to improve from 3.7% margins to 4.0% by 2029. Those projections rely on the idea that more parts and service work, including refrigerated transport systems, can support earnings through different points in the trucking cycle. For investors watching the story, the key question is how effectively the MCT footprint can contribute to that higher margin mix without depending too heavily on new vehicle demand.
Rush Enterprises' narrative outlines potential revenue of US$9.6b and earnings of US$387.1m by 2029. This is based on 10.0% yearly revenue growth and an earnings increase of about US$121.9m from US$265.2m today.
Uncover why Rush Enterprises' fair value indicates a 21% potential upside to its current price before the market closes that gap.
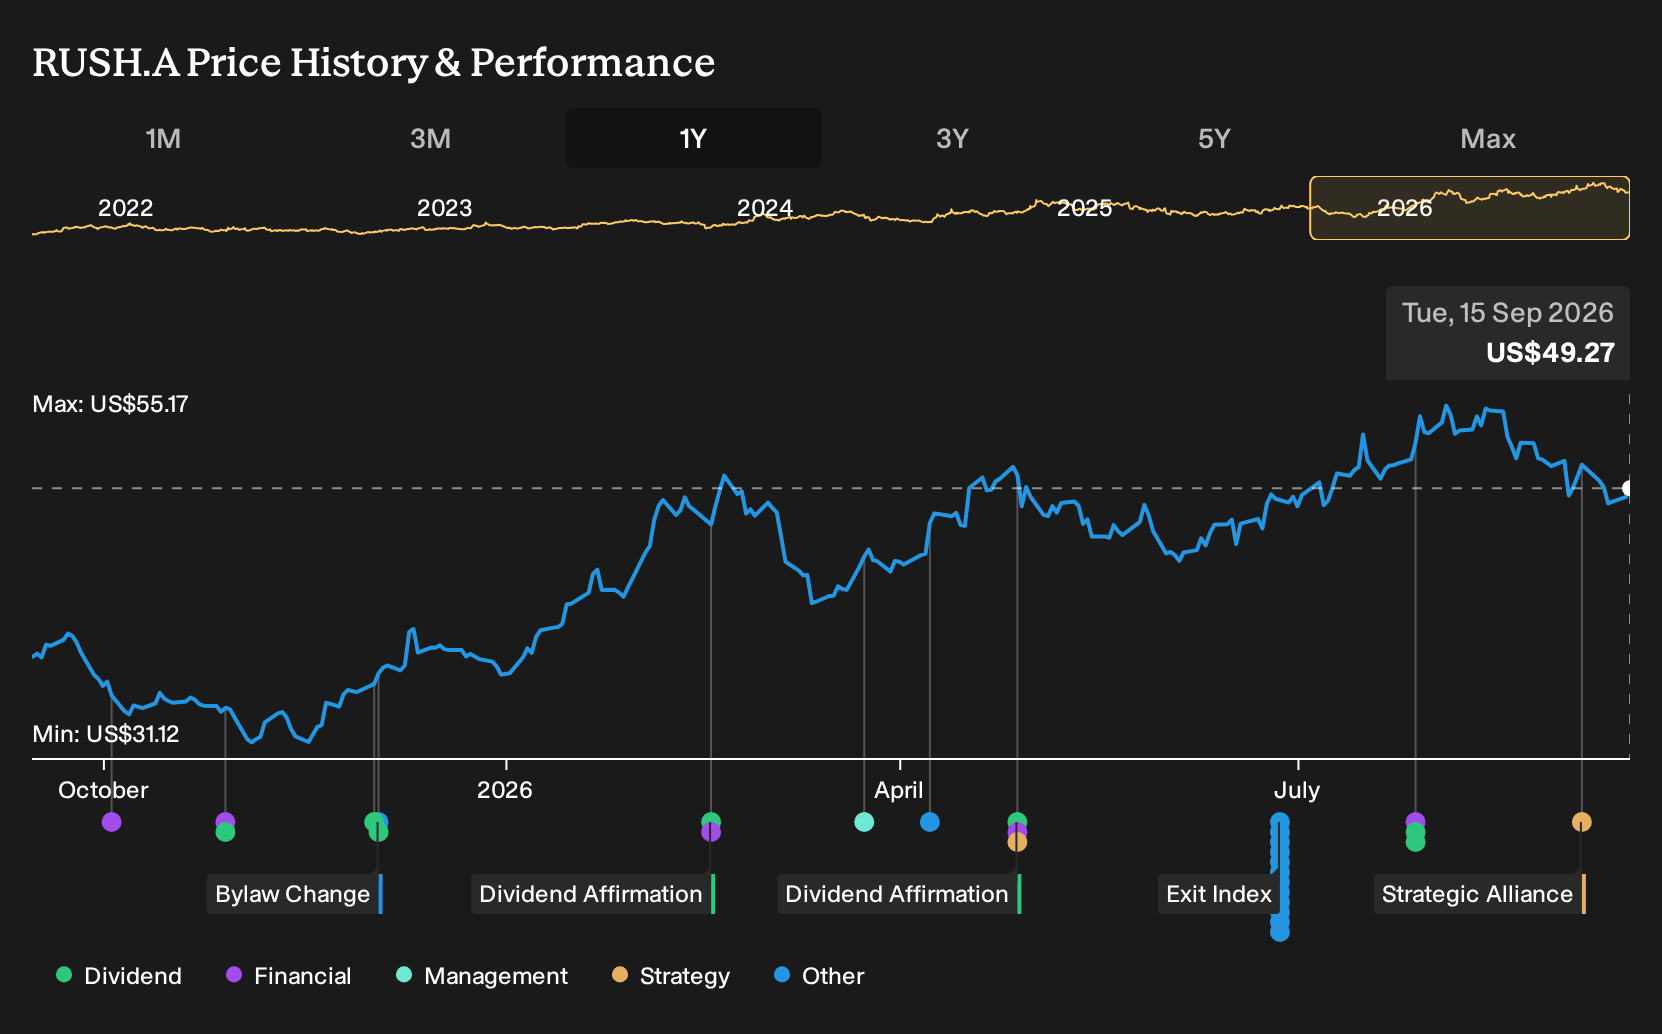
Exploring Other Perspectives
Some of the most optimistic analysts focus on Rush Enterprises using leasing as a long term catalyst rather than refrigeration. Before this joint venture, the bullish group was already modelling about US$10.0b of revenue and US$374.0m of earnings by 2029. You can now judge whether the completed MCT deal pushes those expectations even higher or forces a rethink.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Rush Enterprises research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Rush Enterprises. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Rush Enterprises' overall financial health at a glance.
Looking For More Investment Ideas Beyond Rush Enterprises?
If the Rush Enterprises story has sharpened your thinking, use that momentum to scan a wider field of opportunities that match your risk tolerance and income needs. The Simply Wall St Screener lets you filter for financial strength, income potential and value so you can build a watchlist that fits your own playbook rather than someone else's.
- For investors who want resilient businesses first and excitement second, start with a 11 resilient stocks with low risk scores screen that prioritizes balance sheet strength and steadier fundamentals.
- If income is your priority, focus on companies with robust cash flows and payouts in the 6 dividend fortresses selection that could complement or contrast with Rush Enterprises' dividend profile.
- To hunt for lesser known opportunities with solid financial underpinnings, scan the 16 high quality undiscovered gems list that might not yet be crowded with institutional attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com