
3 European Growth Companies With Insider Ownership Growing Earnings At 13%
In recent weeks, European markets have faced pressure from rising oil prices and inflation concerns, influenced by geopolitical tensions and monetary policy shifts. Despite these challenges, growth companies with substantial insider ownership can offer resilience and potential for earnings expansion, as they often align management interests with shareholder value.
Top 10 Growth Companies With High Insider Ownership In Europe
| Name | Insider Ownership | Earnings Growth |
| Pharma Mar (BME:PHM) | 12.1% | 39.6% |
| MilDef Group (OM:MILDEF) | 10.3% | 31.1% |
| Kuros Biosciences (SWX:KURN) | 25.9% | 58.6% |
| KebNi (OM:KEBNI B) | 12% | 103.8% |
| Gold Road International (OB:GOLDR) | 35.9% | 89.8% |
| CTT Systems (OM:CTT) | 17.4% | 55.3% |
| CD Projekt Red (WSE:CDR) | 35.2% | 45.3% |
| Bonesupport Holding (OM:BONEX) | 10.6% | 32.2% |
| Bergen Carbon Solutions (OB:BCS) | 11.9% | 52% |
| 2G Energy (XTRA:2GB) | 13.4% | 29.8% |
Let's dive into some prime choices out of the screener.
Framery Group Oyj (HLSE:FRAMERY)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Framery Group Oyj designs, manufactures, and markets soundproof private workspaces and related software solutions to address noise and privacy issues in open offices across multiple regions worldwide, with a market capitalization of €509.64 million.
Operations: The company's revenue is primarily generated from its Furniture & Fixtures segment, amounting to €220.05 million.
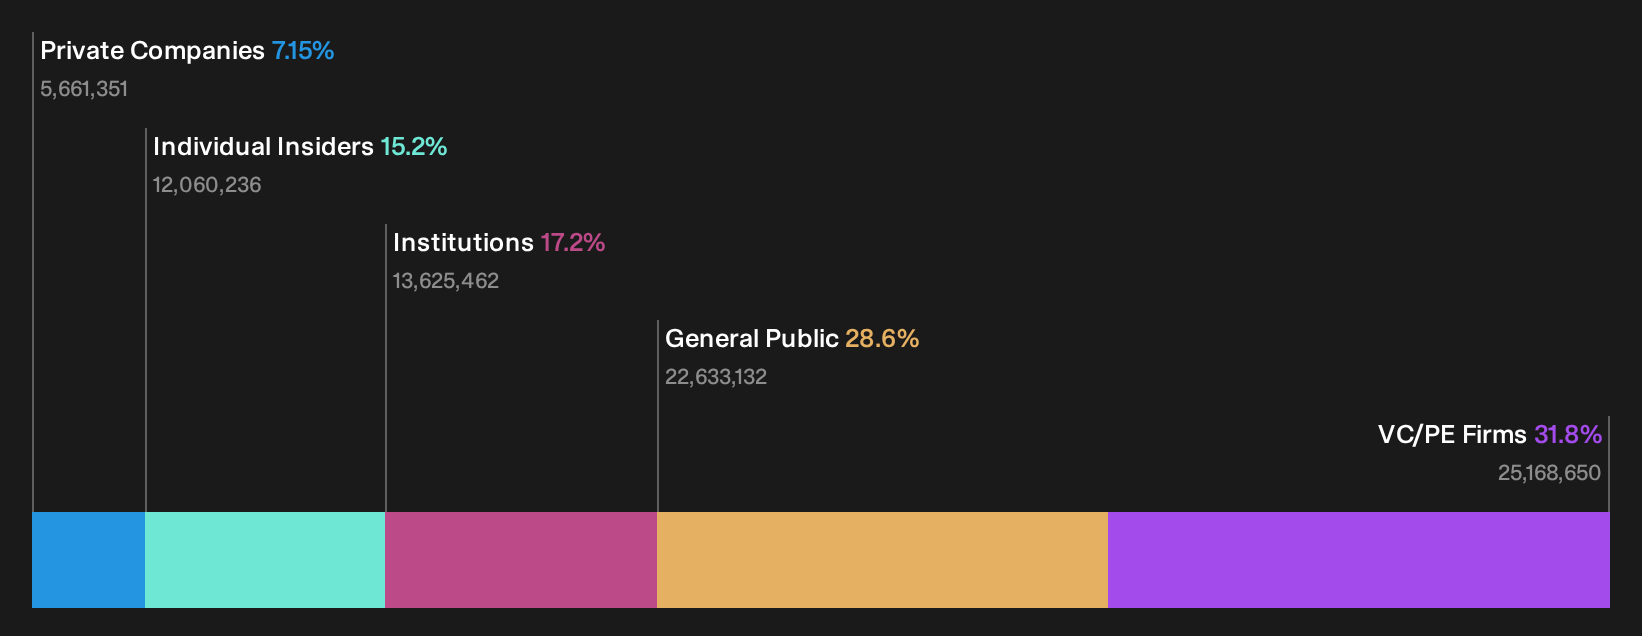
Insider Ownership: 15.2%
Earnings Growth Forecast: 13.8% p.a.
Framery Group Oyj exhibits strong growth potential with a very high forecasted return on equity of 57.3% in three years, despite its high debt levels. While earnings are expected to grow at 13.8% annually, surpassing the Finnish market's growth rate, revenue growth is slower at 7.6%. The company's stock is trading significantly below its estimated fair value and analysts expect a price rise of 43.4%. Recent earnings showed substantial net income improvement year-over-year.
- Get an in-depth perspective on Framery Group Oyj's performance by reading our analyst estimates report here.
- The analysis detailed in our Framery Group Oyj valuation report hints at an deflated share price compared to its estimated value.
NOTE (OM:NOTE)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: NOTE AB (publ) offers electronics manufacturing services across Western Europe and internationally, with a market capitalization of approximately SEK4.88 billion.
Operations: Revenue segments for the company include SEK955.99 million from the Rest of World and SEK3.07 billion from Western Europe.
Insider Ownership: 30%
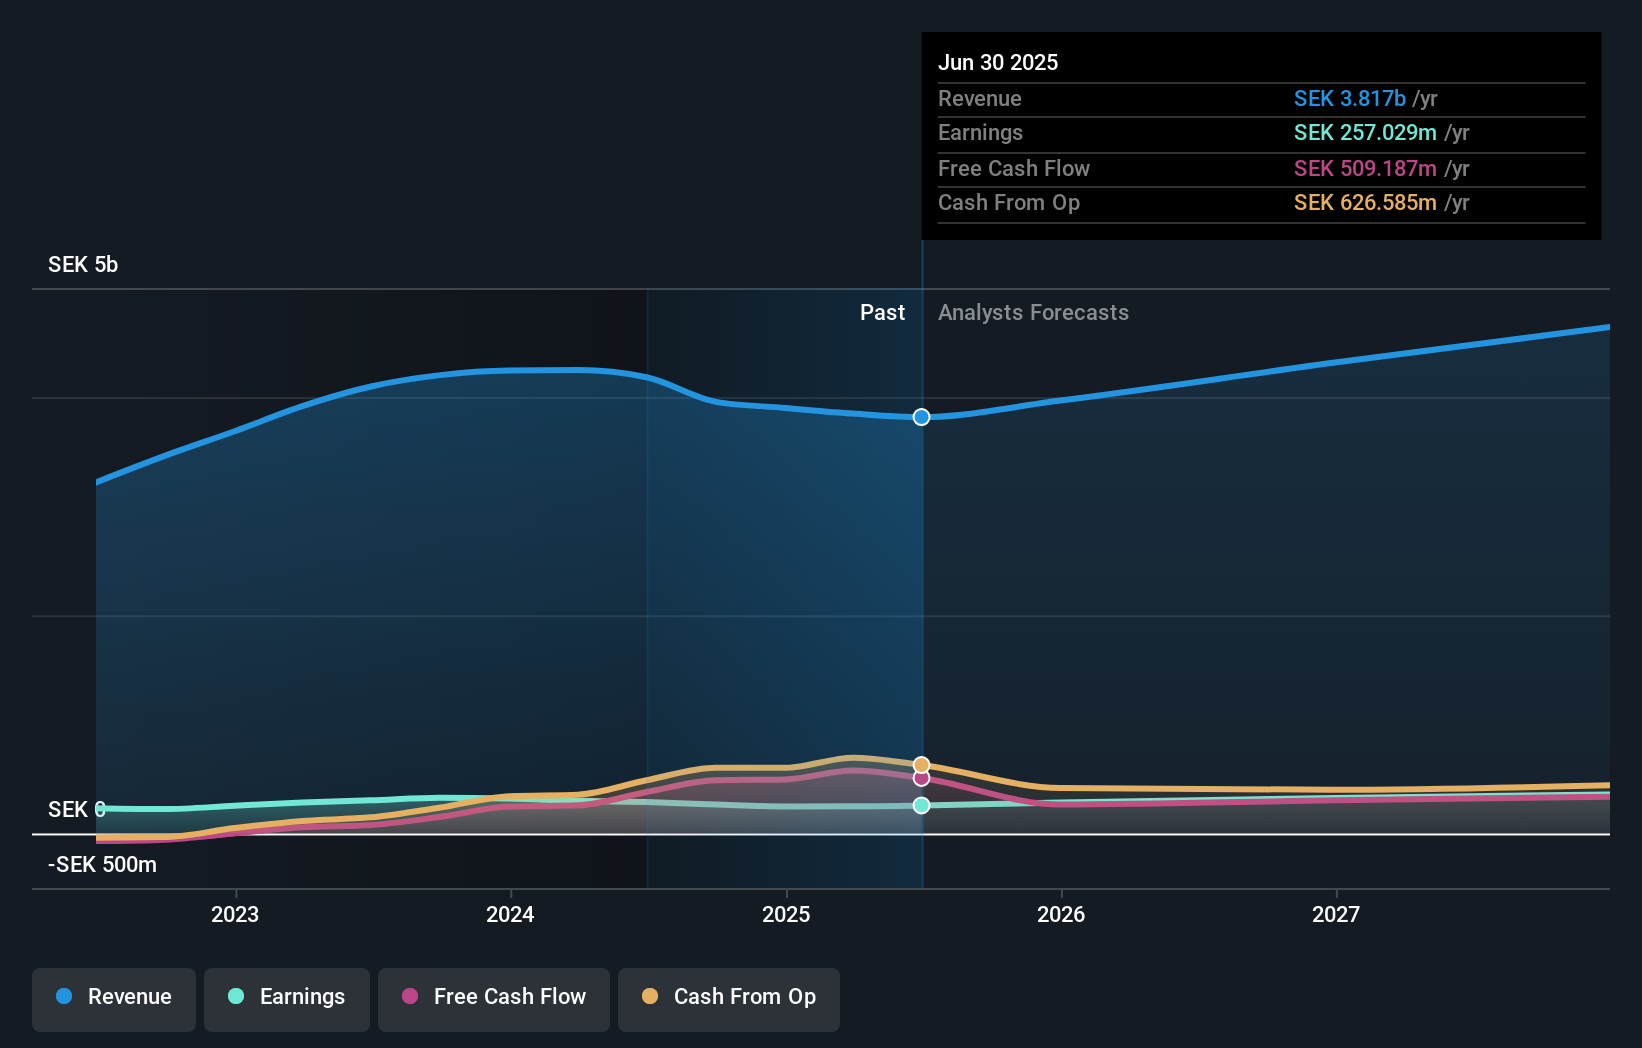
Earnings Growth Forecast: 23.1% p.a.
NOTE AB demonstrates strong growth potential with high insider ownership, supported by recent contracts in security and data centre sectors. Earnings are forecast to grow significantly at 23.1% annually, outpacing the Swedish market. Despite a lower return on equity forecast of 17.8%, the company trades at a significant discount to its fair value and shows substantial insider buying recently. However, its debt coverage by operating cash flow remains weak, which could pose financial challenges.
- Click to explore a detailed breakdown of our findings in NOTE's earnings growth report.
- Our expertly prepared valuation report NOTE implies its share price may be lower than expected.
Sectra (OM:SECT B)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Sectra AB (publ) offers medical IT and cybersecurity solutions across Sweden, the United Kingdom, the United States, and other international markets, with a market cap of approximately SEK57.07 billion.
Operations: The company's revenue is primarily derived from its Imaging IT Solutions segment, which generated SEK3.26 billion, and its Secure Communications segment, which contributed SEK448.96 million.
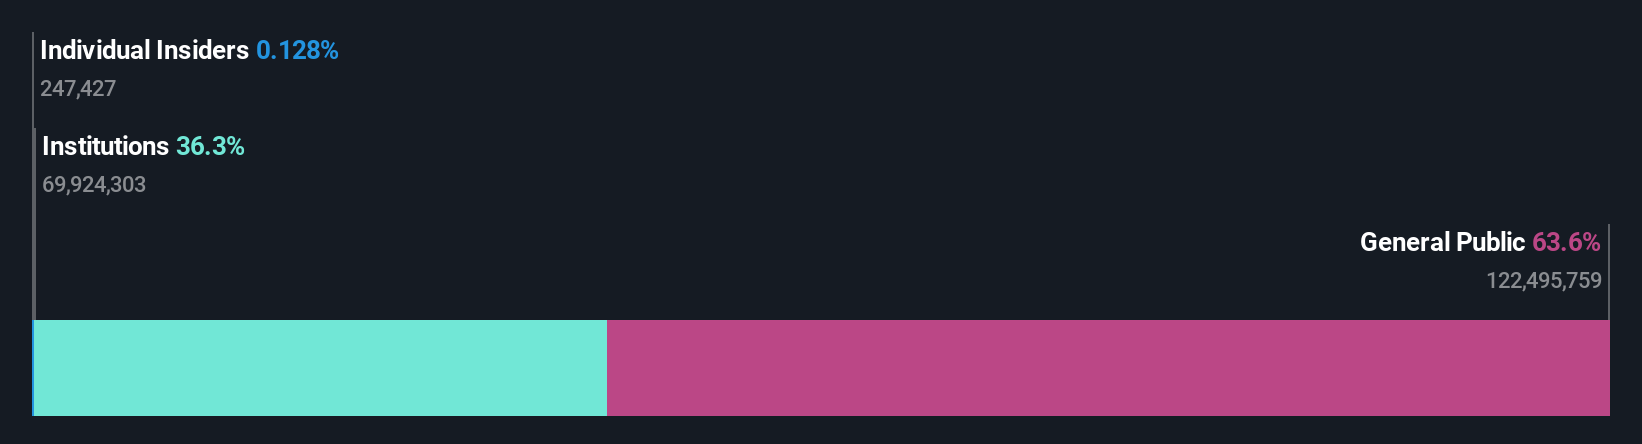
Insider Ownership: 28.8%
Earnings Growth Forecast: 23.8% p.a.
Sectra shows promising growth with earnings projected to rise 23.8% annually, surpassing the Swedish market's average. Despite significant insider selling recently, the company continues to expand its Sectra One enterprise imaging solution across Europe and North America, highlighted by a major contract extension in Denmark. Recent board changes and a special dividend announcement reflect ongoing corporate activity, while robust revenue growth further underscores its potential as a dynamic player in healthcare technology.
- Click here and access our complete growth analysis report to understand the dynamics of Sectra.
- Insights from our recent valuation report point to the potential overvaluation of Sectra shares in the market.
Taking Advantage
- Click here to access our complete index of 214 Fast Growing European Companies With High Insider Ownership.
- Interested In Other Possibilities? Uncover 27 companies that survived and thrived after COVID and have the right ingredients to survive Trump's tariffs.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com