
Did Delivery App Push Just Shift McDonald's Stock Investment Narrative?
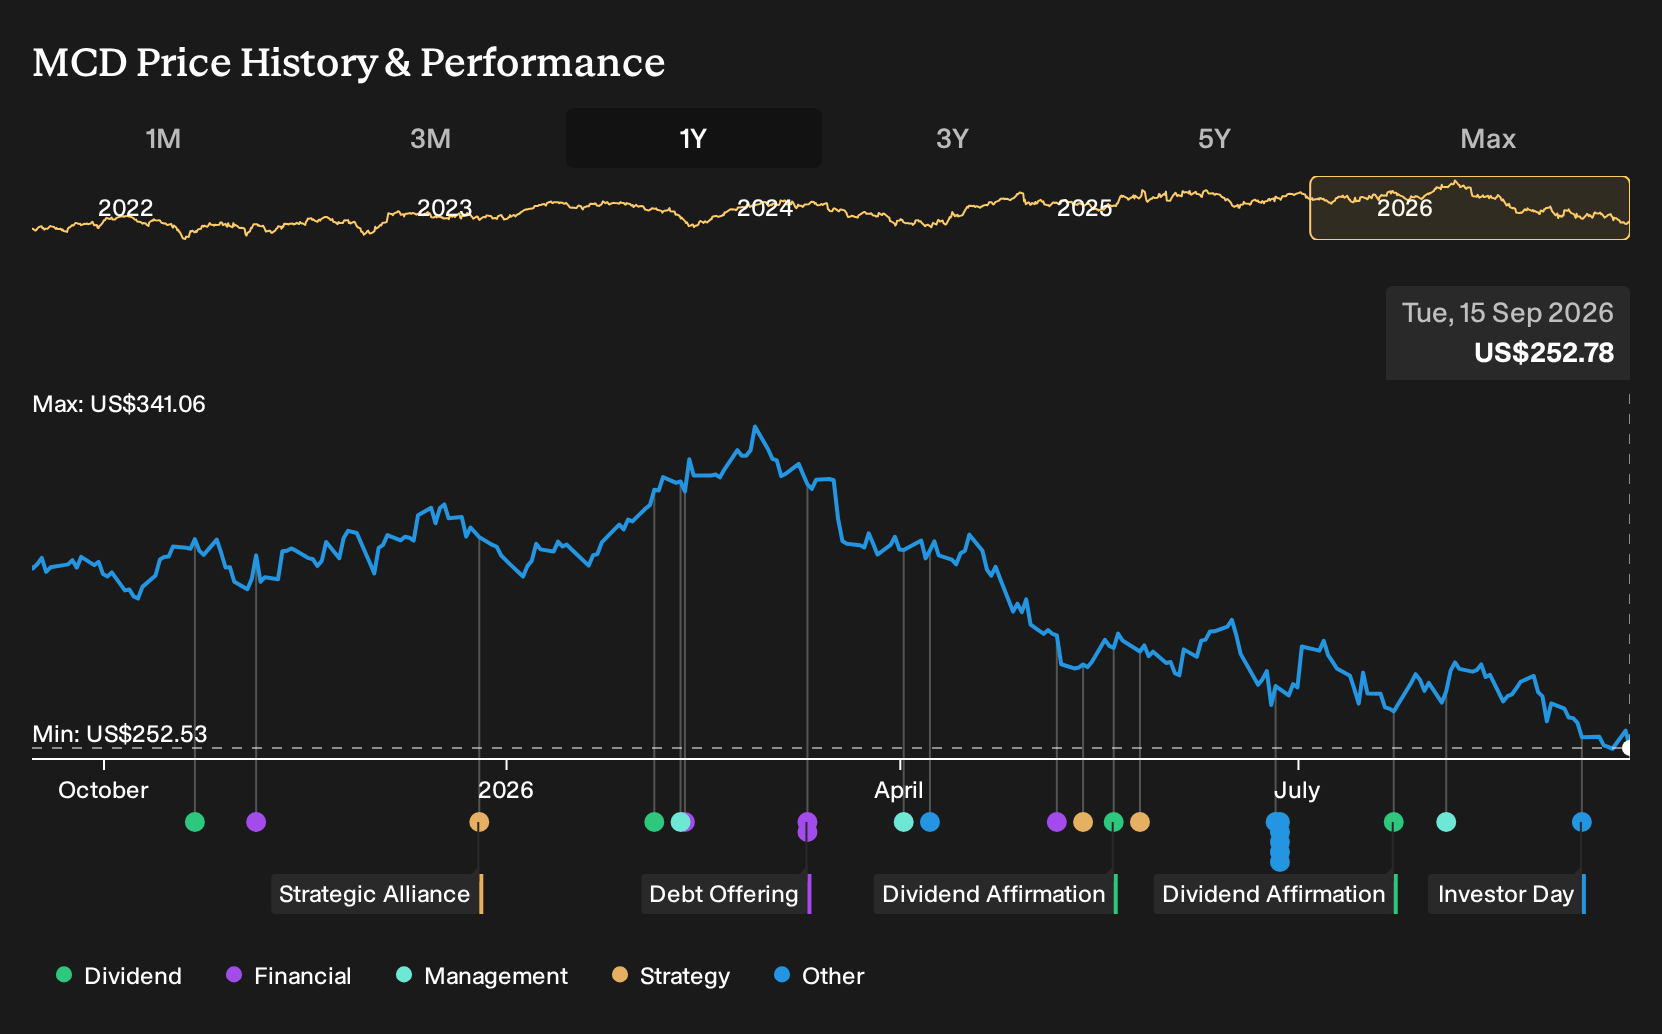
- McDonald's is preparing for an upcoming investor day after reporting that its global delivery platform generated about US$20b in systemwide sales across roughly 90% of restaurants, with a goal to route 30% of delivery orders through its own app by the end of 2027.
- The focus on app based ordering, unified technology and branded promotions such as the SpongeBob x One Piece Happy Meal indicates a push to deepen customer engagement while responding to demand pressures and operational challenges.
- We will now look at how McDonald's digital push and investor day focus might influence the broader investment narrative for the business.
McDonald's Investment Narrative Recap
To stay comfortable owning McDonald's today, you need to believe its digital push, delivery scale and menu promotions can offset pressure on lower income guests and rising operating costs. The near term swing factor is whether digital ordering and branded campaigns translate into steadier traffic as the investor day details how management intends to support demand.
The biggest operational risk right now is that weaker spending from price sensitive customers lingers, keeping U.S. same store sales under pressure while input costs and labor remain elevated. Recent headlines about worker safety incidents and competitive pricing only matter if they start to affect store level operations, franchise relations or brand perception in a sustained way.
The most relevant recent update is McDonald's disclosure that its global delivery platform has reached about US$20b in systemwide sales across roughly 90% of restaurants, with a target of routing 30% of those orders through its own app by the end of 2027. That scale gives the business more levers on order mix, marketing and data as it prepares to address investors at the upcoming event.
Execution around this digital ecosystem is tied directly to key catalysts. Progress on app penetration and unified technology could help efficiency and guest frequency, while any delays, higher than expected tech costs or pushback from franchisees would add to the existing concerns around slower low income traffic and intense U.S. competition that investors are already watching closely.
McDonald's narrative projects US$31.7b in revenue and US$10.7b in earnings by 2029, based on analyst expectations. This implies forecast revenue growth of 4.6% per year and an earnings increase of about US$1.9b from current earnings of US$8.8b.
Uncover how McDonald's fair value indicates a 25% potential upside to its current price before sentiment closes that gap.
Exploring Other Perspectives
Across 10 fair value estimates from the Simply Wall St Community, views on McDonald's stretch from about US$233.67 to US$316.06 per share, so retail opinions already span a wide gap. You are weighing those pre news views against fresh concerns around low income traffic and worker safety, as well as the digital and delivery ambitions highlighted ahead of investor day. That mix of caution and potential means opinion can differ sharply. It is worth exploring several of these community viewpoints before deciding how McDonald's fits your own thesis.
Explore 9 other McDonald's fair value estimates, including one that suggests there may be as much as 25% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so rely on your own analysis and judgment.
- A great starting point for your McDonald's research is our analysis highlighting 6 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for McDonald's. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate McDonald's overall financial health at a glance.
Looking for more McDonald's style investment ideas?
If McDonald's digital and delivery push has you thinking about where else technology, balance sheet strength or income potential might matter, it can help to widen the search beyond a single stock. The Simply Wall St Screener lets you filter for traits that match your own approach, whether you care more about resilience, income or finding under followed opportunities.
- If capital preservation sits high on your list, start with companies that score well on resilience and financial risk and review our 11 resilient stocks with low risk scores.
- If you want potential upside with solid underlying numbers, scan a curated 16 high quality undiscovered gems that have quality fundamentals but limited attention.
- If you care most about balance sheet strength and durable business profiles, focus on our list of solid balance sheet and fundamentals (22 results) to see which stocks currently meet that bar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com