
OSRAM Licht (HMSE:OSR) Draws Fresh Attention As A Pricey Valuation Question Emerges
OSRAM Licht (HMSE:OSR) has drawn fresh attention after recent share performance, with the price closing at €52. This lighting and sensor specialist now shows a mix of short term declines and longer run gains.
Recent trading tells a mixed story for OSRAM Licht. The share price has eased over shorter periods, while the 1 year and 3 year total shareholder returns of 4.25% and 23.63% indicate that investors have still been rewarded over time.
Scan how OSRAM Licht stacks up against other industrials by reviewing our hand picked list of solid balance sheet and fundamentals (195 results), which may better fit your risk tolerance and style.
OSRAM Licht combines a sizeable €4.94b market value with solid long term shareholder returns. However, after the recent soft patch around €52, it is worth asking whether that quality actually comes at a fair price today.
Price-to-Earnings of 32.2x: Is it justified?
On a simple earnings lens, OSRAM Licht carries a P/E of 32.2x, while the last close sits at €52. That level looks more demanding than some peers, yet still lines up closely with parts of the broader Electrical sector and its immediate comparison group.
The P/E ratio compares what you pay per share to the profit the business generates per share. For a lighting and sensor specialist like OSRAM Licht, this metric reflects how much investors are willing to pay today for each euro of reported earnings in a sector where profitability, capital intensity, and technology cycles can influence what seems reasonable.
Against the European Electrical industry, the picture gets sharper. OSRAM Licht trades above the regional industry average P/E of 25.4x, which signals investors are paying a clear premium relative to that group. At the same time, the stock sits slightly below the Electrical industry average of 33.4x and under the peer average of 34x, so the current valuation also undercuts some closer comparables that the market prices even richer on earnings.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 32.2x (ABOUT RIGHT)
Still, the recent share price softness and OSRAM Licht's premium P/E could face pressure if sector sentiment weakens or if earnings momentum disappoints expectations.
Find out about the key risks to this OSRAM Licht narrative.
Another view on OSRAM Licht’s value
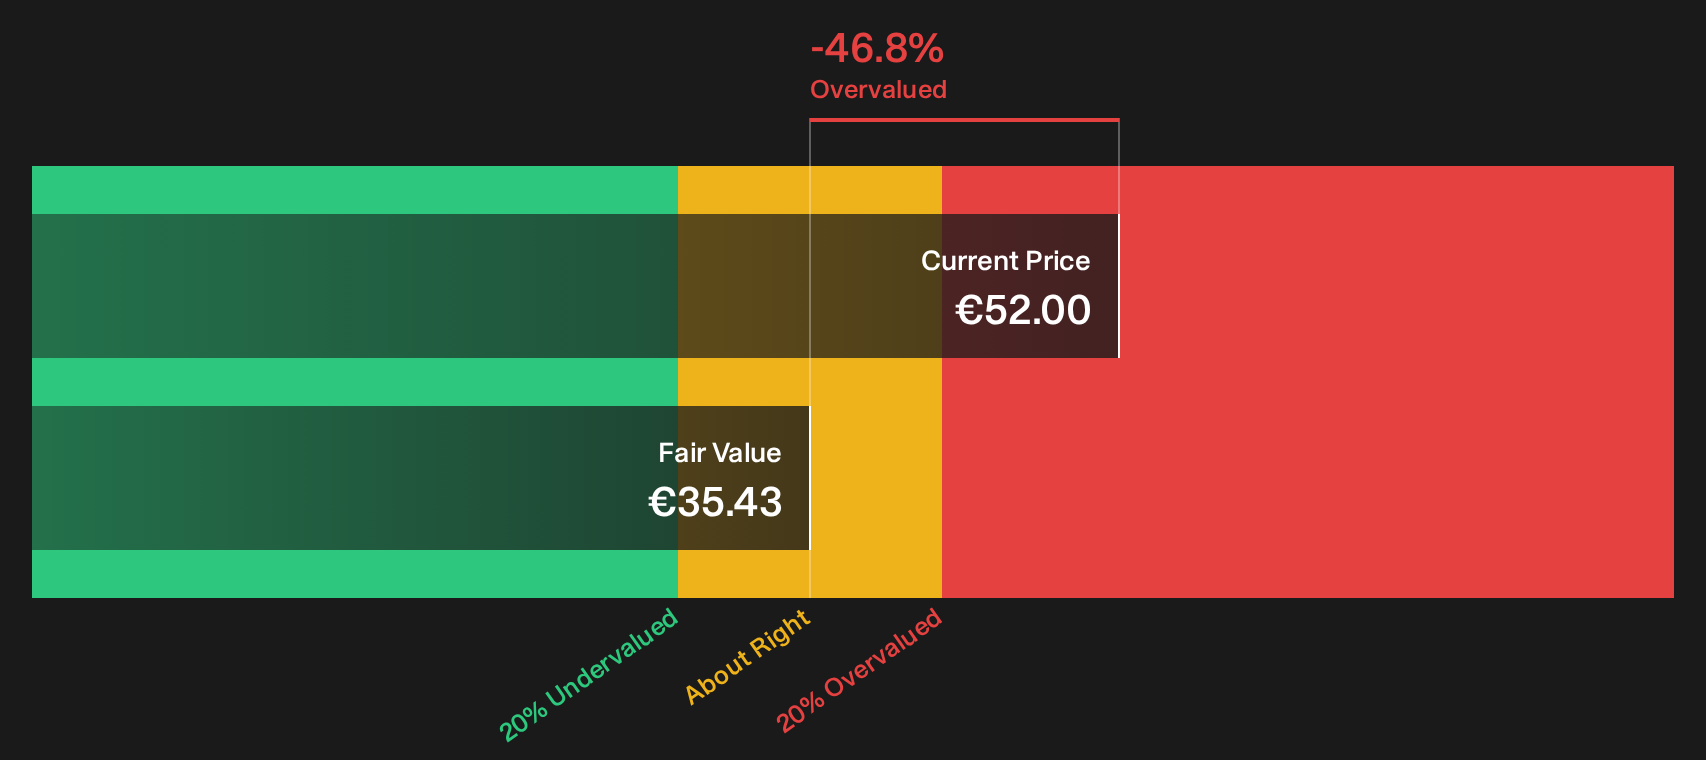
The first check used the P/E ratio and pointed to OSRAM Licht looking roughly in line with parts of its sector on earnings. A second lens, the SWS DCF model, paints a different picture. On that framework, the current €52 price sits well above an estimated future cash flow value of €35.43, which frames the stock as overvalued rather than fairly priced.
That kind of gap can matter. It suggests buyers today pay a premium that only holds up if future cash generation tracks a more upbeat path than the model implies. This raises the question for investors about how much optimism is already in the price.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out OSRAM Licht for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 194 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on OSRAM Licht so far. If you want to move quickly and decide where you stand, start by weighing its 1 key reward.
Looking for more OSRAM Licht sized investment ideas?
If OSRAM Licht has sharpened your sense of price versus quality, now is the moment to widen the lens and compare it with other targeted opportunities.
- Target resilient potential by reviewing a 102 resilient stocks with low risk scores that may better match the level of volatility you are comfortable taking on.
- Hunt for value with a 623 high quality undiscovered gems that surfaces lesser known businesses with fundamentals you can assess on your own terms.
- Prioritise consistent strength by scanning a 161 dividend fortresses that focuses on companies offering higher income streams alongside underlying business quality.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com