
AI Demand Boosts Outlook Could Be A Game Changer For Snowflake (SNOW)
- Snowflake reported second quarter fiscal 2027 sales of US$1,546.79 million and a reduced net loss of US$191.72 million, while completing a US$3.70 billion buyback that retired 25.38 million shares under its March 2023 program.
- Management raised full year fiscal 2027 product revenue guidance to US$6,070 million and tied performance to rising demand for AI offerings such as CoCo and CoWork, highlighting AI workloads as a core engine for future usage.
- The focus now turns to how Snowflake's upgraded full year guidance and AI driven demand might reshape the wider investment narrative.
Scan other AI infrastructure plays moving on similar themes to Snowflake's Data Cloud by reviewing our curated list of 60 AI infrastructure stocks.
Snowflake Investment Narrative Recap
To be comfortable owning Snowflake, you need to believe its AI Data Cloud can keep turning rising AI interest into durable usage rather than one off migration spikes. The latest quarter points to stronger product demand and a smaller loss, while the completed US$3.7b buyback tightens the share count but does not change the operating story.
The key near term catalyst is management’s raised fiscal 2027 product revenue guidance, which hinges on customers actually ramping AI workloads like CoCo and CoWork. The biggest risk stays the same. Competition and normalization of migration heavy projects could slow consumption and make it harder to absorb Snowflake’s elevated R&D and sales spending.
The most relevant update here is Snowflake’s higher full year fiscal 2027 product revenue outlook of US$6,070 million, up from US$5,840 million. That guidance reflects management’s view of demand durability after the second quarter, where sales reached US$1,546.79 million and the net loss narrowed to US$191.72 million.
This revision matters for catalysts because it ties the near term story directly to execution in AI heavy workloads and large enterprise migrations. If those projects scale as Snowflake intends, the higher revenue base could help absorb ongoing investment and gradually reduce losses. If adoption is slower, the gap between spending and monetization remains the core pressure point.
Snowflake's narrative points to forecast revenue of US$11.7b and expected earnings of US$172.1 million by 2029. This sits against analyst assumptions of 29.1% yearly top line growth and an earnings shift of roughly US$1.3b from the current loss of about US$1.1b in earnings today.
Uncover how Snowflake's fair value indicates a 28% potential upside to its current price before the market closes the gap.
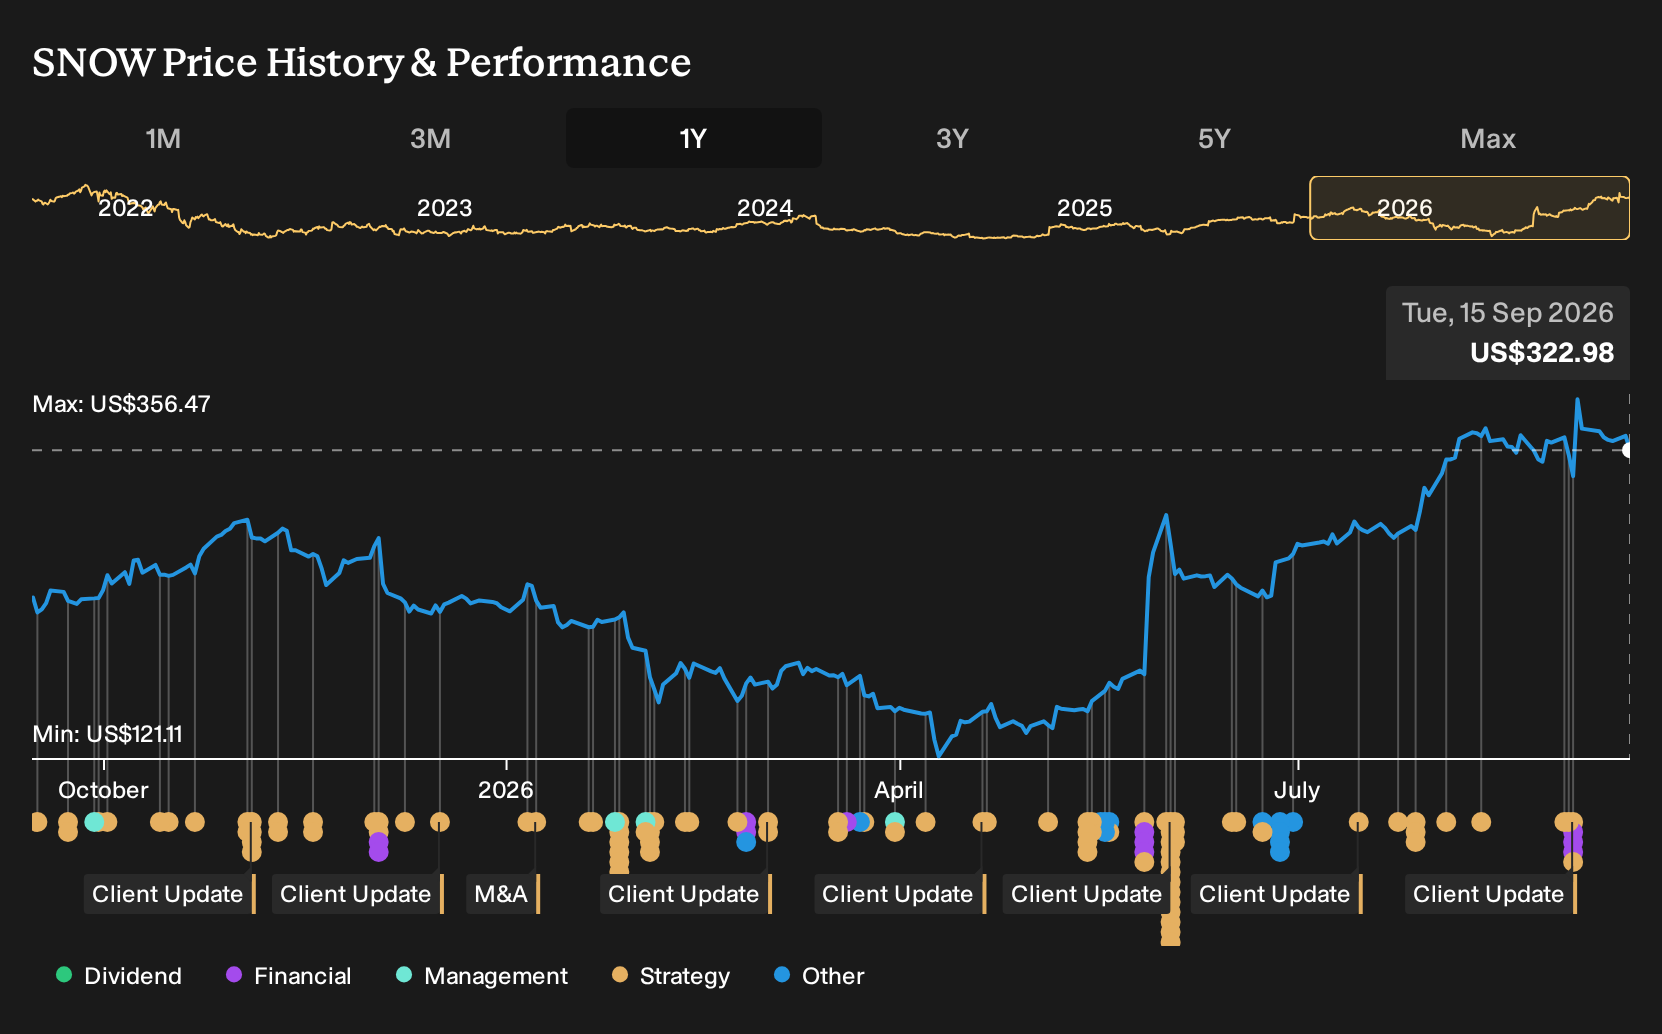
Exploring Other Perspectives
One alternate angle to watch is the bullish view that Snowflake’s AI driven partnerships, like Sayari and Optimove, could turn AI workloads into a far more powerful revenue engine than consensus expects. Those analysts were already pencilling in about US$11.8b of revenue and US$485.4 million of earnings by 2029, so they may reassess those targets again after this news. That gap to the more cautious forecasts highlights how widely opinions can differ, so treat this as a prompt to compare several narratives and decide which feels closest to your own expectations.
Explore 7 other Snowflake fair value estimates, including one that suggests potential upside of up to 43% from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so trust your own analysis.
- A great starting point for your Snowflake research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Snowflake. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Snowflake's overall financial health at a glance.
Looking For More Investment Ideas Beyond Snowflake?
Once you have a view on Snowflake, it often helps to compare it with other opportunities that fit different risk and income profiles. The Simply Wall St Screener lets you quickly scan groups of companies that share similar financial traits or balance sheet strength, so you can build a watchlist that suits how you like to invest.
- If you want to focus on potential mispricing, review a curated 34 high quality undervalued stocks that currently screen well on both quality and value filters.
- For investors who care most about capital protection and steadier business profiles, narrow your search to a 11 resilient stocks with low risk scores that scores well on resilience metrics.
- Those chasing future leaders before they become widely followed can scan a 16 high quality undiscovered gems that already show solid fundamentals but get less attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com