
Fitch Upgrade Might Change The Case For Investing In Kite Realty Trust (KRG)
- Fitch Ratings recently upgraded Kite Realty Group Trust’s long-term issuer ratings and operating partnership ratings to BBB+ from BBB, citing sustained operational outperformance and progress under its Project Elevate capital recycling program.
- The agency highlighted how tight open-air retail supply and strong tenant demand have improved Kite Realty Group Trust’s pricing power, helping the landlord quickly re-lease space previously vacated by bankrupt tenants.
- We will now look at how Kite Realty Group Trust’s investment narrative may shift as Fitch’s BBB+ upgrade reframes its perceived credit strength.
See how Fitch’s upgrade of Kite Realty Group Trust fits into the broader hunt for resilient balance sheets with our curated 11 resilient stocks with low risk scores.
Kite Realty Group Trust Investment Narrative Recap
To own Kite Realty Group Trust, you need to be comfortable with a simple idea. The REIT is trading near-term earnings noise for what it sees as higher quality, open-air Sunbelt and suburban retail exposure. Fitch’s move to BBB+ helps the story on balance sheet strength, but it does not change the near-term swing factors that matter most.
The key short term catalyst is still execution on backfilling big box vacancies and getting rent commencements from leases signed under stronger market terms. The biggest risk remains timing and cost. Delays in tenant build outs, persistent box vacancy, or higher interest expense could pressure net operating income even if headline occupancy looks healthy.
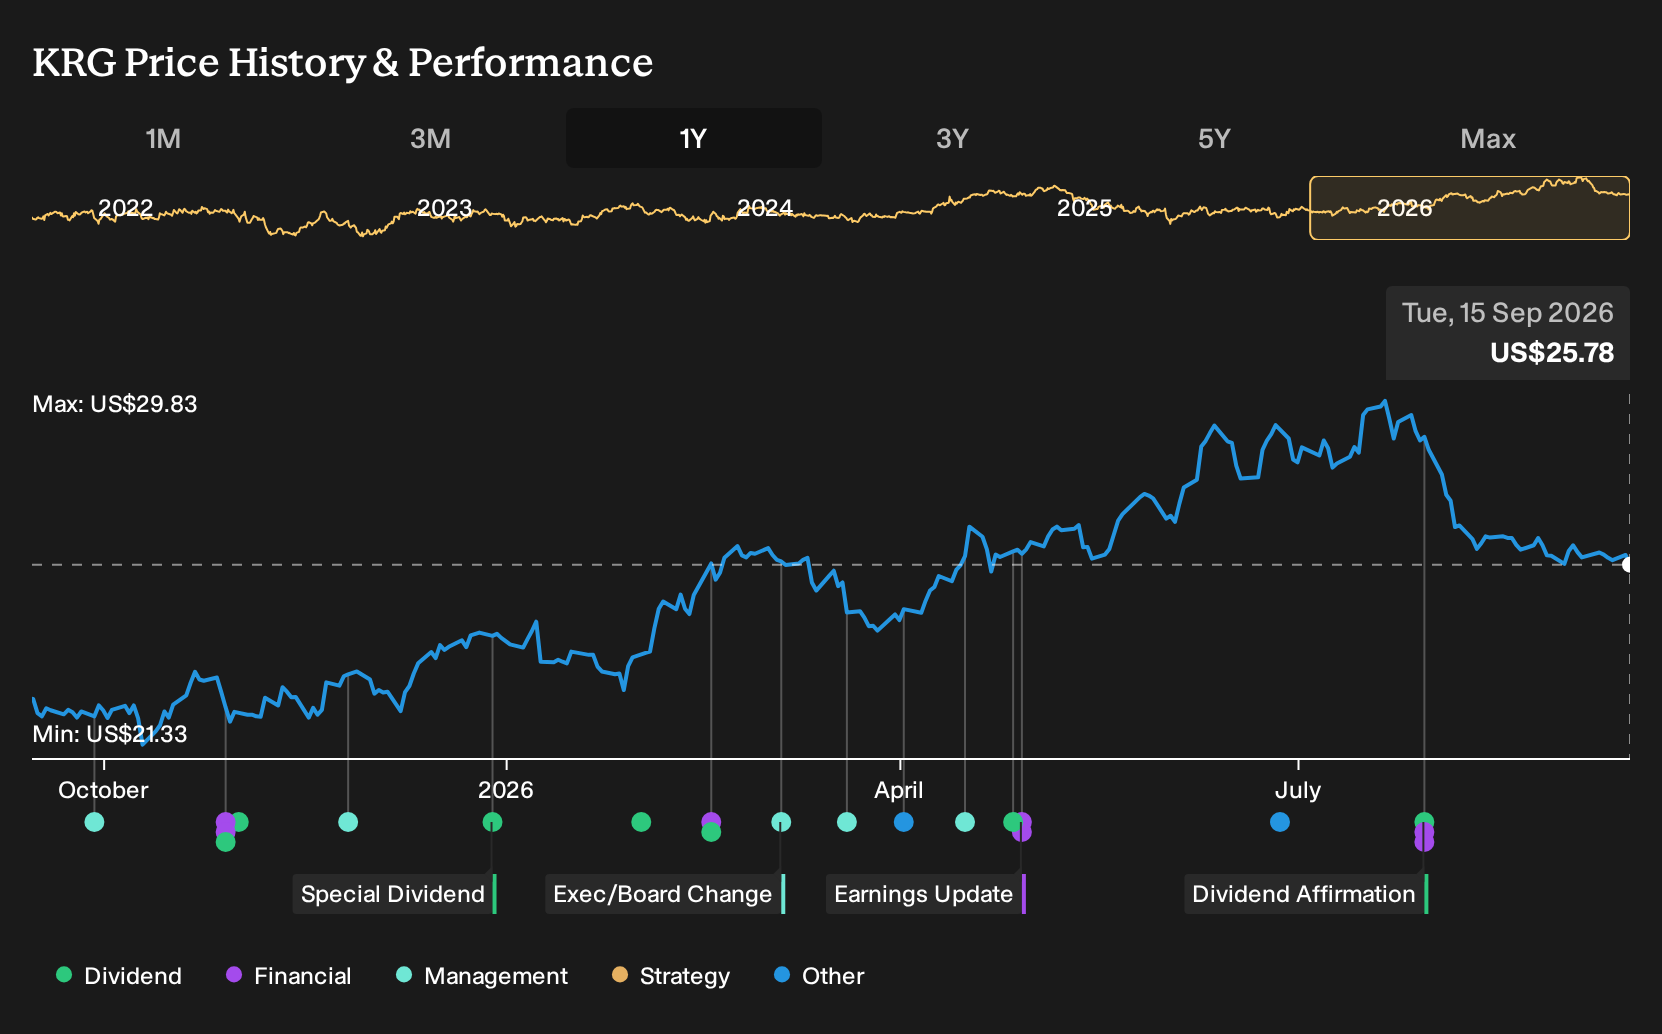
The BofA NY Global Real Estate Conference appearance on 15 September 2026 is well timed alongside the Fitch upgrade. Management now has a fresh platform to walk investors through how Project Elevate, leasing spreads and capital allocation are feeding into Kite Realty Group Trust’s credit profile and interest coverage.
For you, the event is mainly about clarity on execution. Watch for concrete updates on rent commencement schedules for previously bankrupt anchor boxes, traction in Sunbelt and gateway markets, and any commentary on refinancing plans given interest payments are flagged as a pressure point. Those details will shape how durable this new BBB+ footing looks over the next couple of years.
Kite Realty Group Trust’s current analyst narrative points to forecast revenue of $877.4 million and earnings of $48.0 million by 2029, built on assumed yearly revenue growth of 2.1% and an earnings decline of about $238.3 million from earnings today of $286.3 million.
Uncover why Kite Realty Group Trust's fair value indicates an 18% potential upside to its current price, a gap that could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between US$27.90 and US$30.50, so private investors already bracket Kite Realty Group Trust within a fairly tight band. Those views were formed before the Fitch BBB+ upgrade and the BofA NY conference, which could reshape expectations around interest costs, tenant risk and long term cash flow resilience.
Explore another Kite Realty Group Trust fair value estimate, including one that suggests it could be worth just $27.90.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Kite Realty Group Trust research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Kite Realty Group Trust. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kite Realty Group Trust's overall financial health at a glance.
Looking For More Ideas Beyond Kite Realty Group Trust?
If Kite Realty Group Trust has sharpened your focus on balance sheet strength and income potential, it can be worth widening the lens to other opportunities that share similar qualities or offer a different mix of risk and reward.
- For investors who want quality businesses trading on what may be appealing valuations with strong fundamentals, the 16 high quality undiscovered gems can surface candidates that often sit off the usual radar.
- If dependable income is a priority and you prefer companies with higher yields, take a look at 6 dividend fortresses that concentrate on payouts with a focus on resilience.
- For a focus on financial strength and balance sheet resilience, the list of solid balance sheet and fundamentals (22 results) can help you narrow in on businesses where debt and liquidity metrics look more robust.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com