
Why Is United Parcel Service (UPS) Cutting Amazon Volumes To Protect Margins?
- United Parcel Service (NYSE:UPS) has reduced its Amazon delivery volumes by more than 50% as part of a margin-focused shift.
- Management is prioritising steadier margins, gross profit and operating cash flows over headline package volume and revenue growth.
- The cutback in Amazon volumes marks a new phase in how UPS balances large platform partnerships against profitability goals.
- The Amazon volume cut and margin focus are only one part of the wider UPS story that investors may want to understand. We have also flagged 3 warning signs (1 major) for United Parcel Service.
For readers looking beyond UPS to other ideas in this corner of the market, there is also 2 elite penny stocks with strong financials.
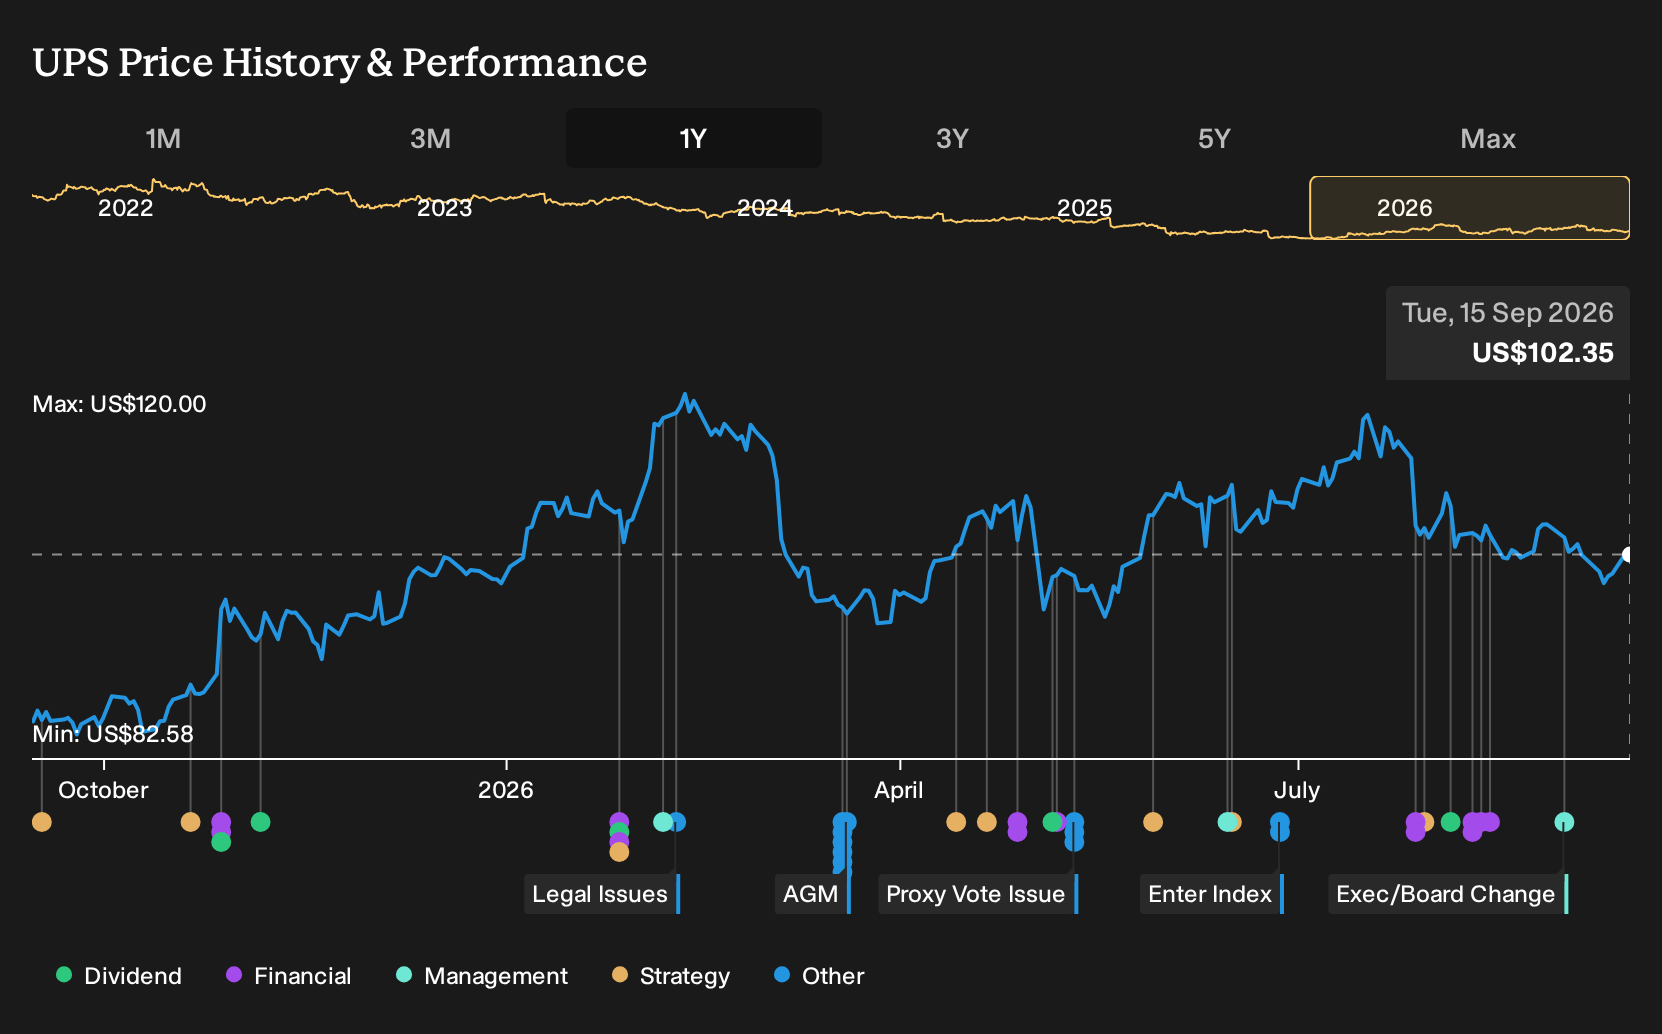
United Parcel Service runs a global parcel and freight network in the US and abroad, and the Amazon volume shift highlights how a logistics provider of its size can lean on a broad customer mix rather than any single e commerce platform.
Why has United Parcel Service pulled back so sharply from Amazon volumes?
UPS is swapping a big stream of low margin Amazon parcels for business that fits better with its pricing and service model. Management is using that shift to stabilise gross profit, operating cash flow and earnings margins rather than chase raw shipment counts.
Does this Amazon reset change the United Parcel Service Narrative investors have been tracking?
The cut aligns directly with the existing Narrative, which leans on $3.5b of planned annual cost savings, the Network of the Future overhaul and a push into higher margin segments like healthcare. The Amazon reduction is one of the clearest tests of whether that margin focused mix shift can hold up against trade policy risks and network reconfiguration costs.
See how these catalysts shape United Parcel Service's path to a $116 fair value.
What should you watch next to see if this margin first strategy is working for UPS?
The key signpost is how UPS reports domestic and international operating margins and free cash flow through 2026 as Amazon volumes fall past the 50% mark. Updates around the September 2026 Morgan Stanley Laguna presentation, particularly on the Network of the Future and building closures, will show whether cost savings are tracking to plan.
One more loose thread in the United Parcel Service story
Headline figures only tell part of the United Parcel Service story, and internal checks point to something important in how those profits are being reported that readers may want to scrutinise more closely. See what our checks flag about the quality of United Parcel Service's earnings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com