
3 US Industrial Distributor Stocks Built For Rising Costs
Supply chains are heating up again, rates are climbing and geopolitical shocks are feeding through to freight, energy and component costs. That mix is punishing for some businesses, yet it can reward distributors and niche suppliers with real pricing power. If you care about which industrial stocks might handle this pressure better than others, keep reading. This article walks through three US industrial distributors exposed to these inflation and rate catalysts.
The three industrial distributors discussed next are only a sample, and the full screen surfaced 238 more US listed suppliers with similarly interesting stories that are not covered in this article. To go straight to the broader opportunity set, use the US Industrial Distributors and Niche Suppliers with Pricing Power screener to identify, filter and analyze which pricing power plays best fit your own watchlist.
W.W. Grainger (GWW)
W.W. Grainger is one of the purest plays on the pricing power theme in this screen, sitting between manufacturers and customers to keep factories, warehouses and hospitals running when supply chains are strained and input costs keep shifting.
Grainger distributes maintenance, repair and operating supplies through its High Touch Solutions North America arm, which generated about US$14.8b of revenue, and its Endless Assortment online platforms, which added roughly US$3.9b. Together, these support a roughly US$60.2b market value.
"Grainger's increasing mix of private label products and ongoing investment in supply chain automation are supporting margin expansion and higher long-term free cash flow conversion, helping offset transitory gross margin headwinds from LIFO/tariff impacts."
What happens if one emerging pressure quietly shifts how much pricing power Grainger can really exercise on every order it ships?
If that pressure point matters to you, read the full narrative for W.W. Grainger to see how Grainger's pricing power story could be shifting behind the headline numbers.

Applied Industrial Technologies (AIT)
Applied Industrial Technologies plugs directly into the pricing power theme, sitting between suppliers and manufacturers to keep motion, fluid power and automation systems running when input costs move around and maintenance cannot wait.
Applied Industrial Technologies runs a large Service Center network that produced about US$3.2b of revenue and an Engineered Solutions arm that added roughly US$1.9b, supporting a US$11.7b market value.
"The accelerating build-out of data center, semiconductor, and advanced manufacturing infrastructure is increasing demand for industrial automation, robotics, and flow control solutions, positioning Applied Industrial Technologies to capture higher-margin sales and expand its addressable market, supporting long-term revenue and margin growth."
What happens if one quiet shift in how customers source higher value automation work changes how much pricing room Applied Industrial Technologies really has on each project?
That quiet shift in sourcing is exactly what the full narrative for Applied Industrial Technologies unpacks, highlighting where Applied Industrial Technologies could still expand pricing and margin headroom.

WESCO International (WCC)
WESCO International is one of the clearest pricing power plays in this screen, supplying electrical, communications and utility products across manufacturing, construction and data center projects where higher input, freight and energy costs often need to be passed through quickly.
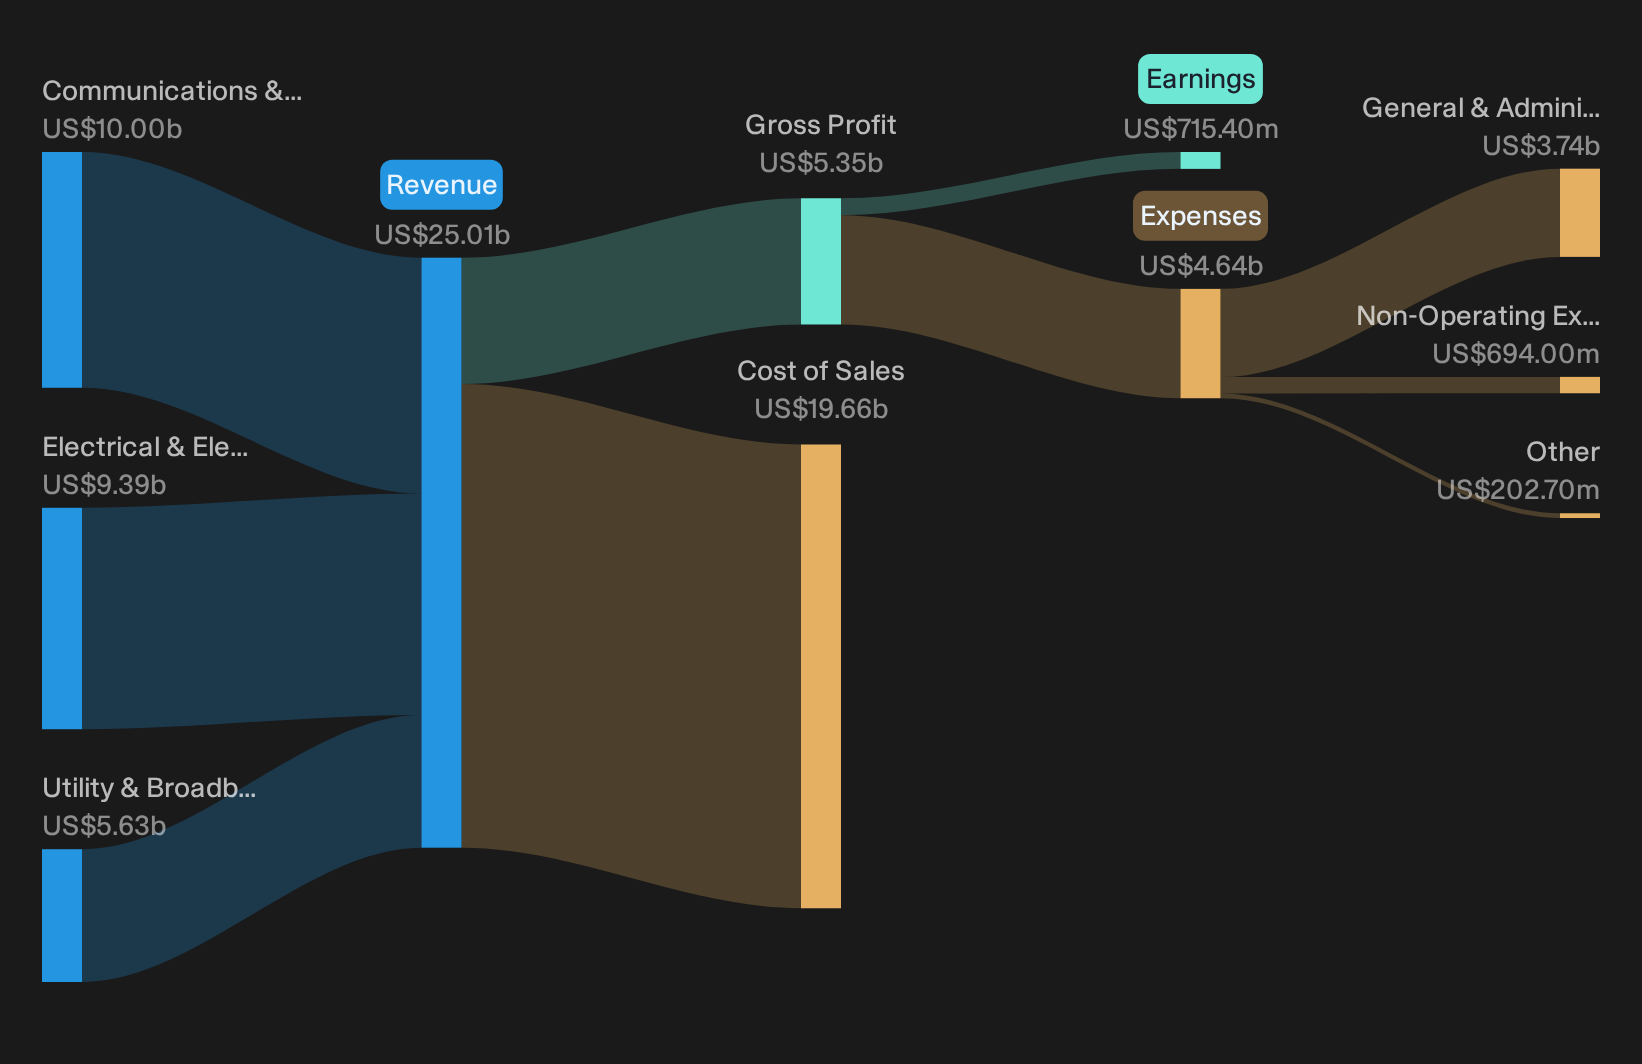
WESCO International generates about US$9.4b from Electrical & Electronic Solutions, roughly US$10.0b from Communications & Security Solutions and around US$5.6b from Utility & Broadband Solutions, and the distributor carries a market value of roughly US$16.4b.
For investors focused on US distributors that can potentially push through rising equipment and logistics costs, WESCO International offers a scaled network, MRO exposure and higher value services that make pricing conversations part of everyday business rather than an occasional negotiation.
"Power intensive AI and cloud data centers are a growing share of customer projects, and WESCO International now sells across the full data center life cycle through its Power to Compute model and recent Newark Engineering acquisition."
The real swing factor is what happens to WESCO International's margin headroom if one tightly watched cost and funding pressure moves in an unfavorable direction.
If that funding squeeze is what you care about, read the full narrative for WESCO International to see how WESCO International's pricing power and capital needs could be quietly decoupling.
Seeking Fresh Alternatives Before They Fly
Fresh opportunities can move quickly. Some are already building breakout momentum while they remain under the radar for now. Before the most attractive entry points are gone, consider acting in a timely way.
- Spot early movers in small caps that already generate real profits by scanning the 76 profitable AI stocks that aren't just burning cash before the crowd focuses on the next AI wave.
- Hunt for resilient payers with strong cash flows using the curated 6 dividend fortresses while elevated yields and dependable distributions continue to be priced cautiously.
- Track businesses building the backbone of tomorrow’s power grid through the focused 38 power grid technology and infrastructure stocks while infrastructure spending momentum develops and attention remains scattered.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com