
Iovance Biotherapeutics (IOVA) Stock Trades At A Premium As It Climbed 307%
Iovance Biotherapeutics has seen its share price move sharply in recent years, which puts fresh focus on a simple question for investors. Does the current valuation of the stock line up with the sales the business is generating today and is expected to produce ahead?
- Over the past year, Iovance Biotherapeutics has returned 307%, which puts a lot of pressure on the sales story to justify where the share price now sits.
- The business model depends heavily on turning its cell therapy pipeline into sustainable revenue, so expectations for future sales growth and the cash needed to reach that point are central to how the stock is priced.
- The analysts covering Iovance Biotherapeutics have run their own numbers. See what analysts think Iovance Biotherapeutics's shares could be worth.
The issue now is whether Iovance Biotherapeutics' current share price can be supported by its sales when viewed through this lens.
If you are questioning whether Iovance Biotherapeutics' 307% one year return is fairly supported by its sales, it can help to compare that sales story with 34 high quality undervalued stocks
Is Iovance Biotherapeutics Getting Expensive on Sales?
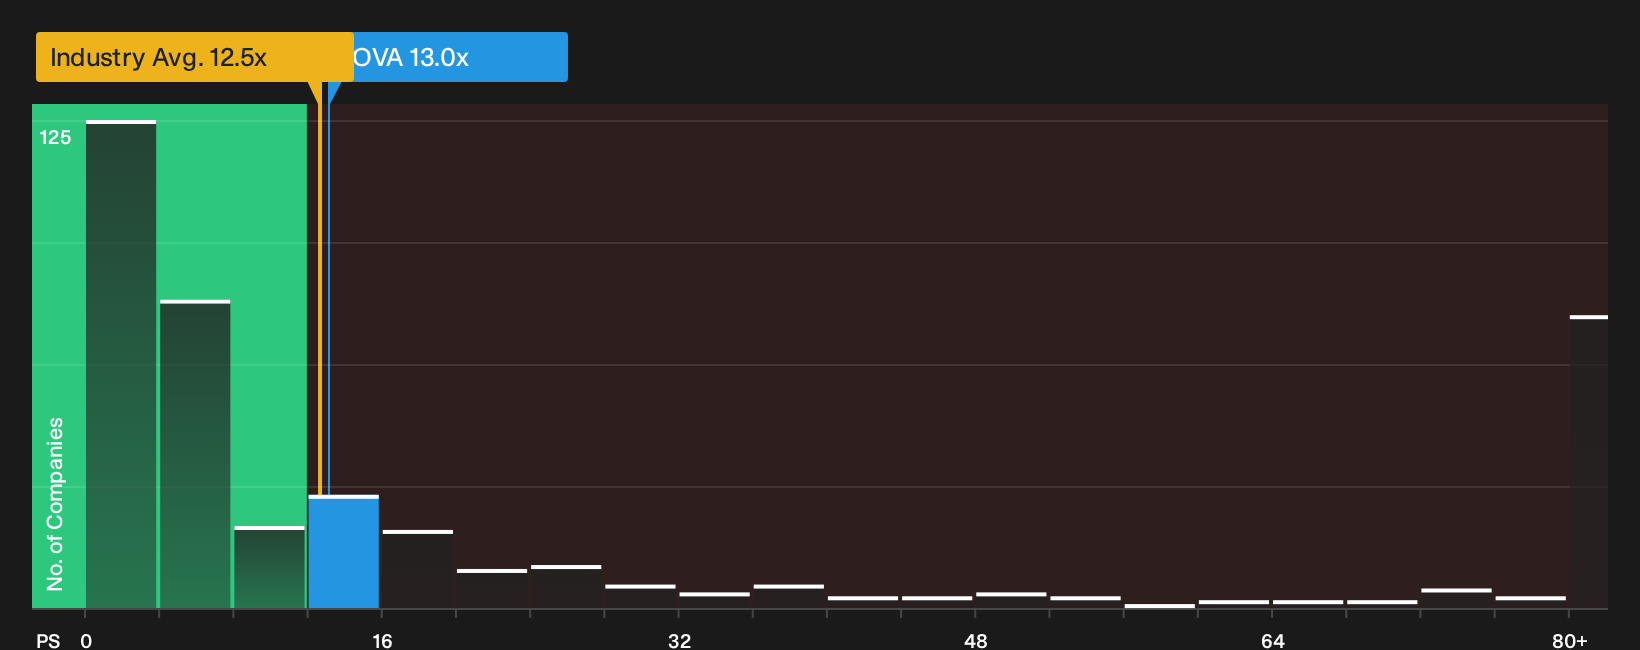
P/S makes sense for Iovance Biotherapeutics because investors are mainly weighing what future revenue from its cell therapies could look like, not current profits. The stock trades on a P/S of about 13.0x, which is close to both the Biotechs industry average of roughly 12.5x and a peer group closer to 13.5x. That cluster suggests the market is broadly valuing Iovance’s revenue in line with similar drug developers that are also working to convert pipelines into commercial products.
The fair P/S level that falls out of the cash flow model is lower than where the shares change hands today. As a result, the current multiple sits above what this framework implies for Iovance Biotherapeutics once its growth, margins and risk profile are all incorporated. For anyone weighing the recent 307% share price move against the sales story, the gap between the present 13.0x P/S and this tailored benchmark is the key figure to check next. Explore the numbers behind Iovance Biotherapeutics's P/S valuation.
The Iovance Biotherapeutics Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Iovance Biotherapeutics pick up exactly where this valuation puzzle leaves off by spelling out which paths for future growth, margins and eventual earnings would need to play out for the shares to be worth materially more or less than today’s price, and they sit on Simply Wall St's Community page. Instead of just giving you a single output from a ratio or model, they unpack the future that number relies on so you can watch how reality lines up with it over time.
The Iovance Biotherapeutics community is divided between investors who see more upside in the story and others who think expectations already look full.
Bull case: 48% undervalued
"Amtagvi is already approved in the United States and is the first TIL (tumor-infiltrating lymphocyte) therapy available for patients with advanced melanoma…"
Discover why this Narrative puts Iovance Biotherapeutics at 48% undervalued.
Bear case: roughly fairly valued
"The company remains highly dependent on Amtagvi, its lead (and only currently approved) product; any setbacks in demand, reimbursement, or competitive developments for this therapy could have an outsized negative impact on Iovance's revenue…"
Explore why this Narrative puts Iovance Biotherapeutics at roughly fairly valued.
Iovance Biotherapeutics' price is only one piece of the investment puzzle
Iovance Biotherapeutics’ valuation tells only part of the story, since the research checks behind this article have also flagged specific concerns that deserve your attention before you decide what to do next. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com