
Morinaga Milk Industry (TSE:2264) Could Be 47% Undervalued On Mixed Share Price Signals
Morinaga Milk Industry (TSE:2264) has drawn fresh attention after recent share performance showed a mixed pattern, with the price declining over the past month and past 3 months, but rising over the past year.
For Morinaga Milk Industry, the picture is of a stock that has cooled in the short term but still rewarded patient holders. The share price is at ¥1,122.5 after a 30 day share price return down 5.6%. However, a 1 year total shareholder return of 28.9% and a 3 year total shareholder return of 64.3% suggests earlier optimism about its prospects and risk profile has not fully reversed.
Compare Morinaga Milk Industry's recent swing between short term weakness and longer term strength with a hand picked set of resilient companies in the 12 resilient stocks with low risk scores.
Bulls point to Morinaga Milk Industry's solid multi year shareholder returns and ongoing revenue and net income growth, while bears focus on the recent pullback. Which side does the current valuation appear to support next?
Price-to-Earnings of 16.2x: Is it justified?
On current numbers, Morinaga Milk Industry trades on a P/E ratio of 16.2x, which lines up with a share price of ¥1,122.5 and appears inexpensive against several reference points.
The P/E ratio compares the stock price to earnings per share and gives a quick sense of how much investors are paying for each unit of profit. For a mature food and beverage group with established brands and steady demand, this kind of earnings-based yardstick often carries more weight than sales-based measures.
Analysts assess 2264 to be trading at good value relative to peers and industry averages, and the internal fair value work points in the same direction. Against a peer average P/E of 28.7x and a JP Food industry average of 17.3x, Morinaga Milk Industry trades at a clear discount. An estimated fair P/E of 21x is also above the current multiple, based on the present earnings profile.
Explore the SWS fair ratio for Morinaga Milk Industry.
Result: Price-to-Earnings of 16.2x (UNDERVALUED)
Still, Morinaga Milk Industry faces clear risks if revenue or net income growth stalls, or if the recent share price pullback signals waning investor conviction.
Find out about the key risks to this Morinaga Milk Industry narrative.
Another view using our DCF model
P/E suggests Morinaga Milk Industry looks inexpensive, yet the SWS DCF model goes even further. It values the shares at ¥2,118.18 based on future cash flows versus the current ¥1,122.5 price, which implies the stock trades at a steep discount. Which yardstick do you trust more when cash flow and earnings tell slightly different stories?
Look into how the SWS DCF model arrives at its fair value.
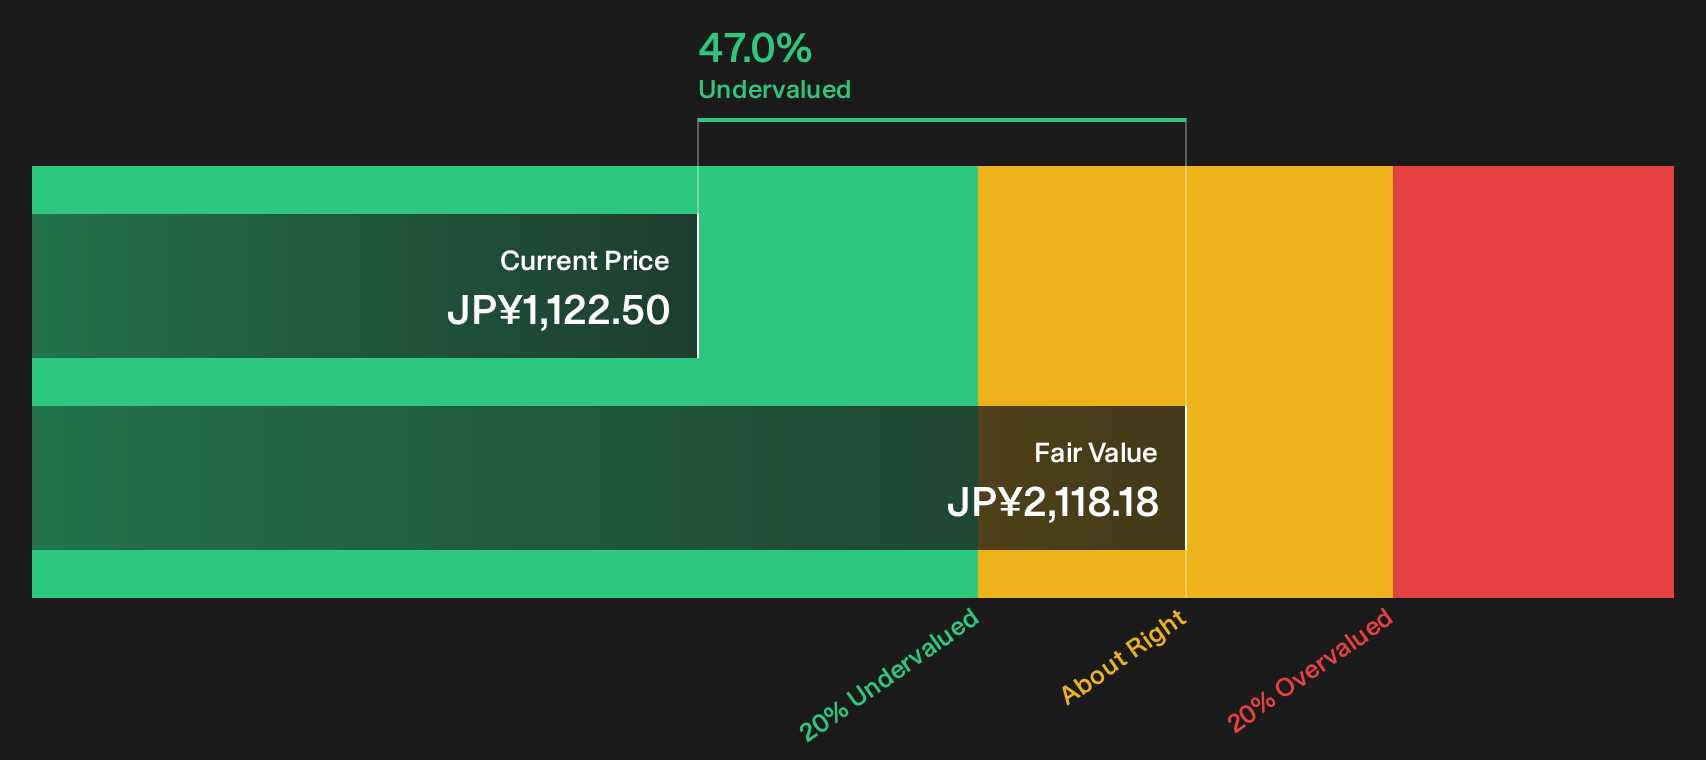
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Morinaga Milk Industry for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 18 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Morinaga Milk Industry's valuation and recent share price can feel confusing, so move quickly to review the data, weigh the potential upside and downside for yourself, and then dig into the 5 key rewards and 1 important warning sign.
Looking for more Morinaga Milk Industry style ideas?
If Morinaga Milk Industry has you thinking about what else might be mispriced, do not stop here. Broader research often uncovers opportunity others miss.
- Target underappreciated value by scanning companies that combine quality fundamentals with discounted prices through the 18 high quality undervalued stocks.
- Strengthen your downside protection by focusing on businesses with strong finances using the list of solid balance sheet and fundamentals (20 results).
- Get ahead of the crowd by researching potential future favourites drawn from the 74 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com