
Is Saia (SAIA) Undervalued On Strong July And August Operating Data?
Saia’s recent operating update
Saia (SAIA) has just given investors fresh operating data for July and August 2026, with LTL shipments per workday, tonnage per workday, and weight per shipment all higher than in the same months of 2025.
Saia’s share price has eased in recent months, with a 30-day share price return of down 7.9% and a 90-day share price return of down 16.9%. However, the year-to-date share price return is up 4.9% and the 5-year total shareholder return is 44.0%, suggesting long-term holders have still seen gains while shorter-term momentum has cooled.
Compare Saia’s recent pullback with other freight and logistics stocks that still show solid fundamentals by scanning our curated list of solid balance sheet and fundamentals (22 results) for potential ideas in the same space.
Saia’s share price has slipped while analyst targets sit higher and intrinsic models screen as rich. Where does fair value actually land in that gap?
Most Popular Narrative: 19% Undervalued
On the widely followed narrative, Saia’s fair value estimate of $438.19 sits well above the last close at $353.80, which puts the focus squarely on how that gap could close over time.
The ongoing expansion and maturation of Saia's national terminal network, combined with network densification, is starting to unlock cost efficiencies and higher shipment volumes in new and legacy markets. This is positioning the company for top-line revenue growth and improved operating margins as these facilities move toward scale.
See why 3 investors see Saia as 19% undervalued.
Result: Fair Value of $438.19 (UNDERVALUED)
Still, Saia’s story can crack if muted shipment growth persists or if heavy terminal spending fails to deliver enough volume to cover higher fixed costs.
Find out about the key risks to this Saia narrative.
Another View On Saia’s Valuation
The popular story around Saia leans on long term earnings power, yet the SWS DCF model paints a very different picture. On that framework, an estimated future cash flow value of $150.73 against a $353.80 share price screens as expensive rather than cheap. Which lens do you trust more for your own work?
Look into how the SWS DCF model arrives at its fair value.
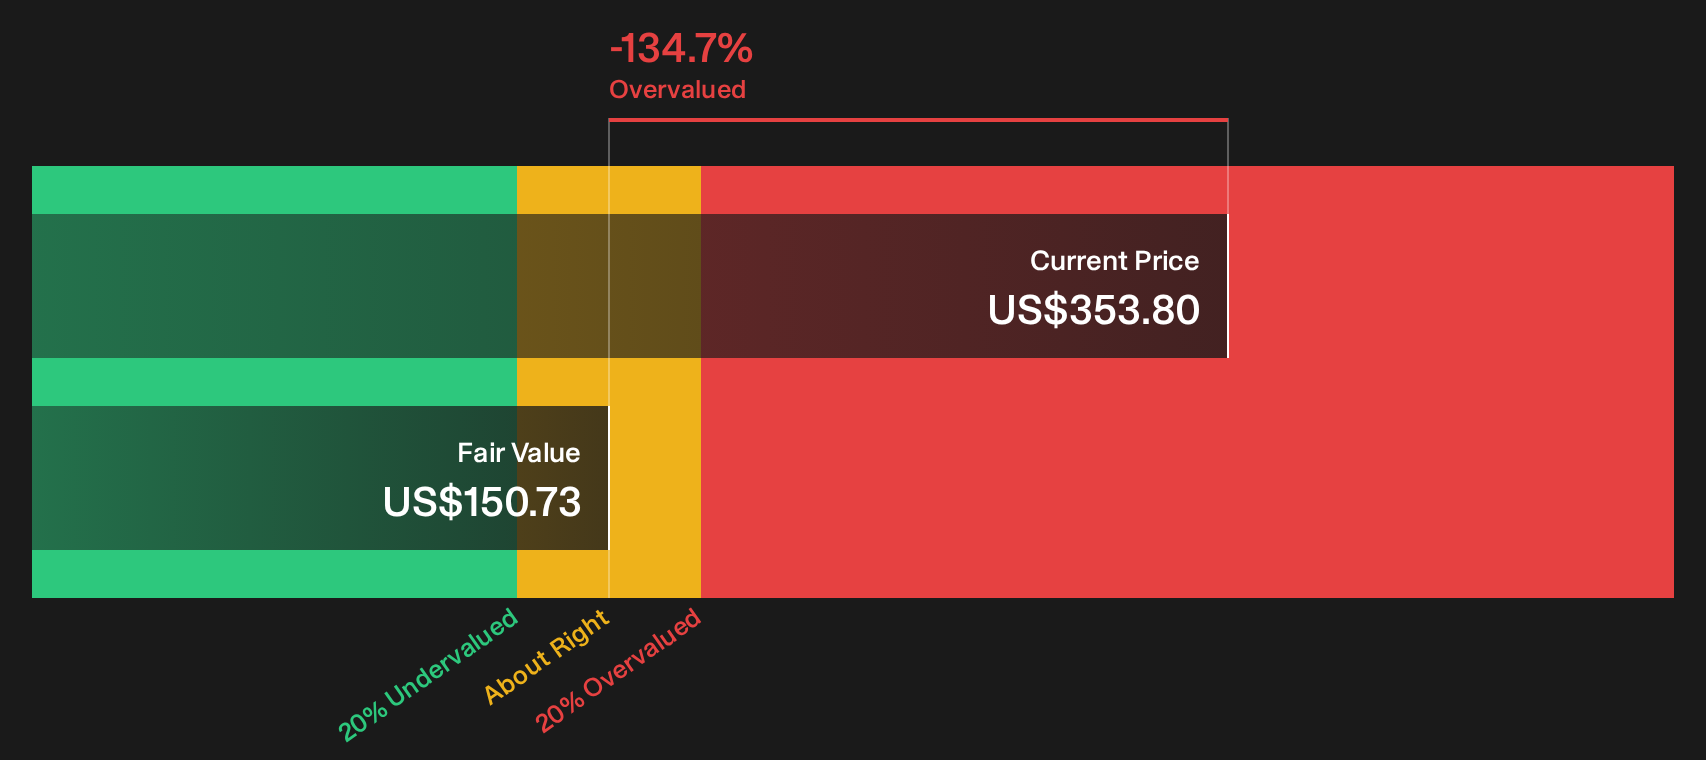
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Saia for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Saia can make the story feel messy, so move quickly, review the data directly, and weigh the potential opportunity yourself with 3 key rewards
Looking for more Saia-like investment ideas?
If Saia has you thinking harder about quality, do not stop here. Use the Simply Wall Street Screener to surface fresh opportunities that fit your style and risk comfort.
- Target resilient balance sheets and fundamentals by scanning our list of solid balance sheet and fundamentals (22 results) so you are not relying on just one stock to carry your portfolio.
- Hunt for mispriced quality by reviewing the 16 high quality undiscovered gems before others catch on and narrow the gap between market price and business strength.
- Prioritise stability and sleep-at-night income by lining up candidates from the 11 resilient stocks with low risk scores so your capital is not exposed only to higher volatility ideas.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com