
How Investors Are Reacting To Jacobs Solutions (J) Major Infrastructure Contract Wins
- Jacobs Solutions recently secured three contracts across rail, water and energy, including a joint venture role on Dublin’s MetroLink, wastewater operations and maintenance for Oklahoma City, and planning and regulatory work for a long duration energy storage project in the Irish Sea.
- These wins deepen Jacobs Solutions’ exposure to long-duration infrastructure and energy projects, increasing operational commitments across design, program management and outsourced utility operations for public sector clients in multiple regions.
- We will now look at how Jacobs Solutions’ expanded role on Dublin’s MetroLink may influence the broader investment narrative around the business.
Scan beyond Jacobs Solutions and see how other infrastructure focused contractors are positioned for the next wave of big public works with 38 power grid technology and infrastructure stocks
Jacobs Solutions Investment Narrative Recap
For a shareholder in Jacobs Solutions, the core belief is that long term infrastructure, water and energy work can support steadier earnings from a large, diversified project backlog. The latest rail, wastewater and energy storage wins add to that pipeline but do not change the near term picture that margins are thin, with net profit margin at 2.5% and debt levels flagged as high.
The key short term swing factor remains execution quality on large, complex public sector programs. Any cost overruns or delays could pressure already modest profitability. The biggest risk still sits with government budget decisions and funding timelines, which can affect the pace of project awards and revenue recognition.
The MetroLink program delivery role with AECOM is the announcement that most directly ties into this story. It leans into Jacobs Solutions’ strength in complex transportation and program management work and aligns with existing exposure to water utilities and long duration energy infrastructure rather than redirecting the business into a new area.
Operationally, a program of this size increases both opportunity and execution risk. MetroLink adds multi year visibility and deepens relationships with Transport Infrastructure Ireland, but also raises exposure to the classic problems of long rail builds, such as scope changes, regulatory shifts and interface management across multiple contractors, which investors already watch closely for Jacobs.
Jacobs Solutions' current narrative assumes annual revenue growth of 7.0%, with earnings moving from $359.3 million today to a consensus of $1.2b by 2029. That implies an earnings increase of about $840.7 million, with analysts expecting revenues of $17.4b and profits of $1.2b in 2029.
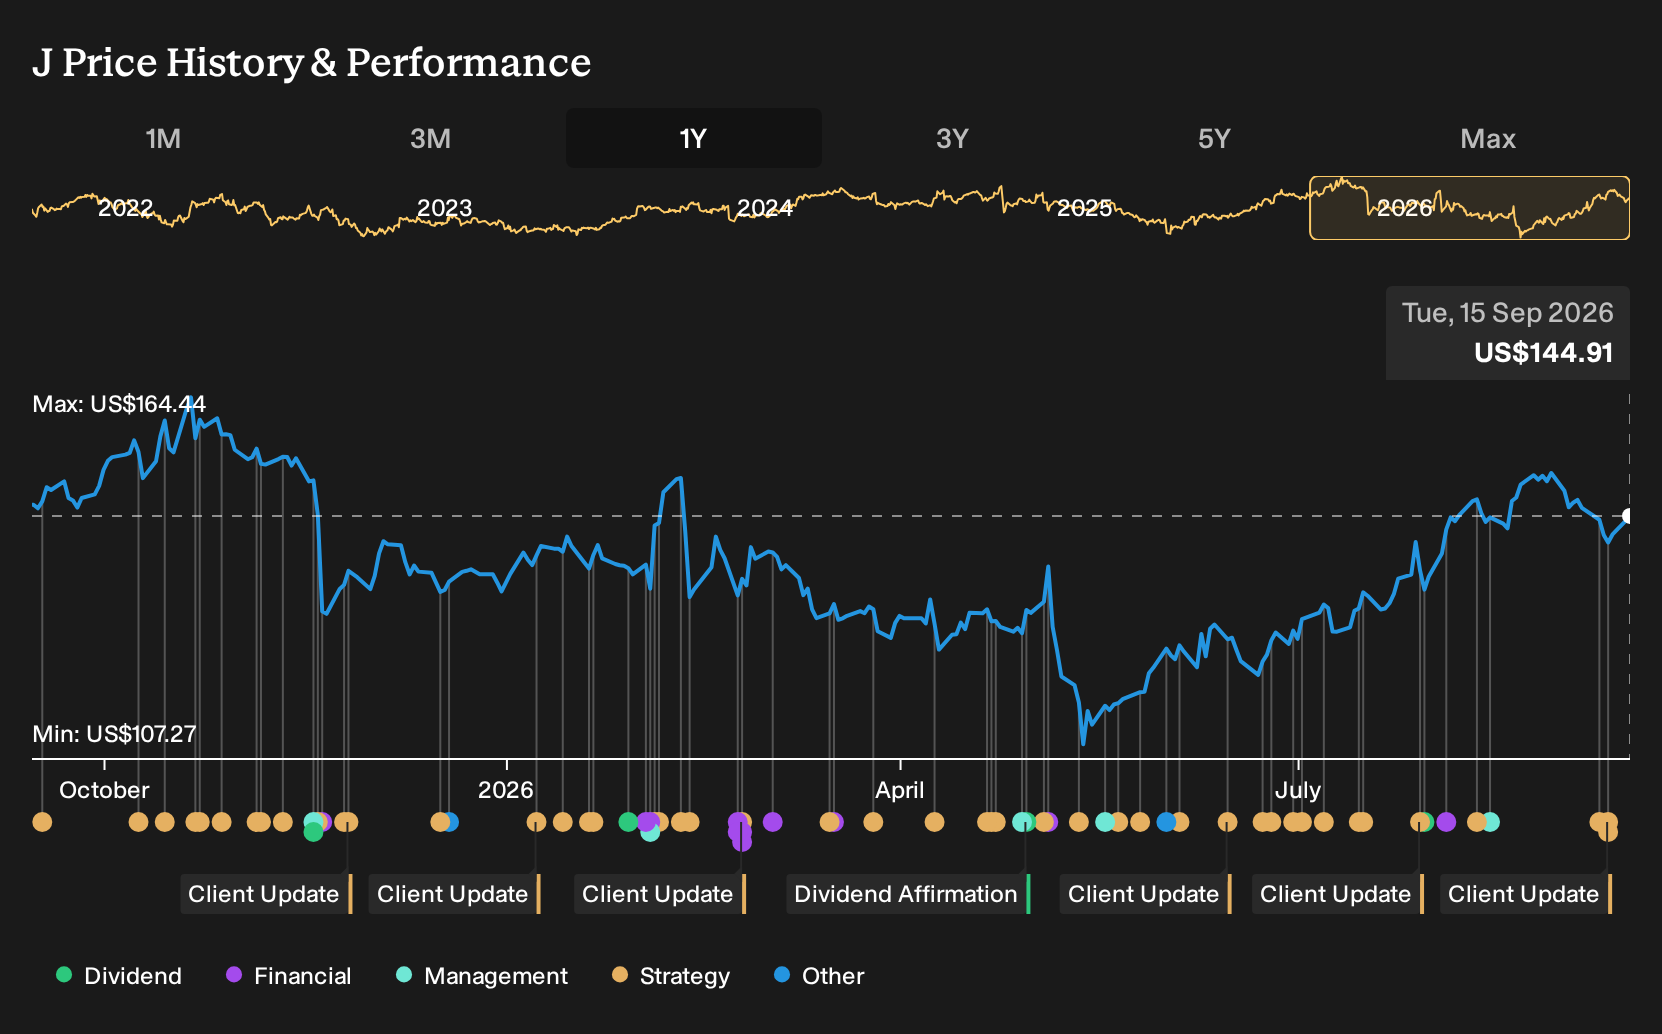
Uncover why Jacobs Solutions' fair value indicates a 12% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Four fair value views from the Simply Wall St Community span roughly US$110 to about US$278, so some retail analysts see Jacobs Solutions trading far below their own estimates, while others are much more cautious. Set those against risks around public budget pressure and long rail delivery complexity, and you get sharply different readings on future performance. Explore those contrasting viewpoints before anchoring on a single story.
Explore 3 other Jacobs Solutions fair value estimates, including one that suggests as much as 24% downside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Jacobs Solutions research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Jacobs Solutions. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Jacobs Solutions' overall financial health at a glance.
Looking for more investment ideas beyond Jacobs Solutions?
Once you have a view on Jacobs Solutions, it can help to widen the lens and see how other businesses stack up on income, value and resilience. The Simply Wall St Screener lets you move from a single ticker to a curated pool of stocks that match the traits you care about most.
- If you want income that aims for both size and staying power, scan through a group of potential 6 dividend fortresses that could suit a yield focused watchlist.
- For investors who care most about paying a sensible price for strong fundamentals, filter for companies in the 34 high quality undervalued stocks and see which ones deserve a closer look.
- If capital protection and balance sheet strength matter most to you right now, narrow the field to 11 resilient stocks with low risk scores that may offer a steadier ride through different market conditions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com