
Should New Sauce Launch Require Action From Campbell's (CPB) Investors?
- Campbell's has rolled out four ready-to-use Campbell's Sauces in Thai Curry, Butter Chicken, Creamy Lemon Garlic and Smothered Chicken, positioned as two-step, 20-minute meal solutions for households of up to four people at a suggested US$2.79 per pack.
- The launch, backed by a Two-Step Tuesdays campaign with pro dancer Witney Carson, signals Campbell's push to capture growing demand for convenient, quick meal helpers without requiring major changes to home cooking routines.
- We will now examine how Campbell's investment narrative could be influenced by this two-step sauces launch aimed at convenience seekers.
Scan how Campbell's push into faster home cooking compares with other packaged food players hunting for convenience driven momentum using our hand picked 34 high quality undervalued stocks.
Campbell's Investment Narrative Recap
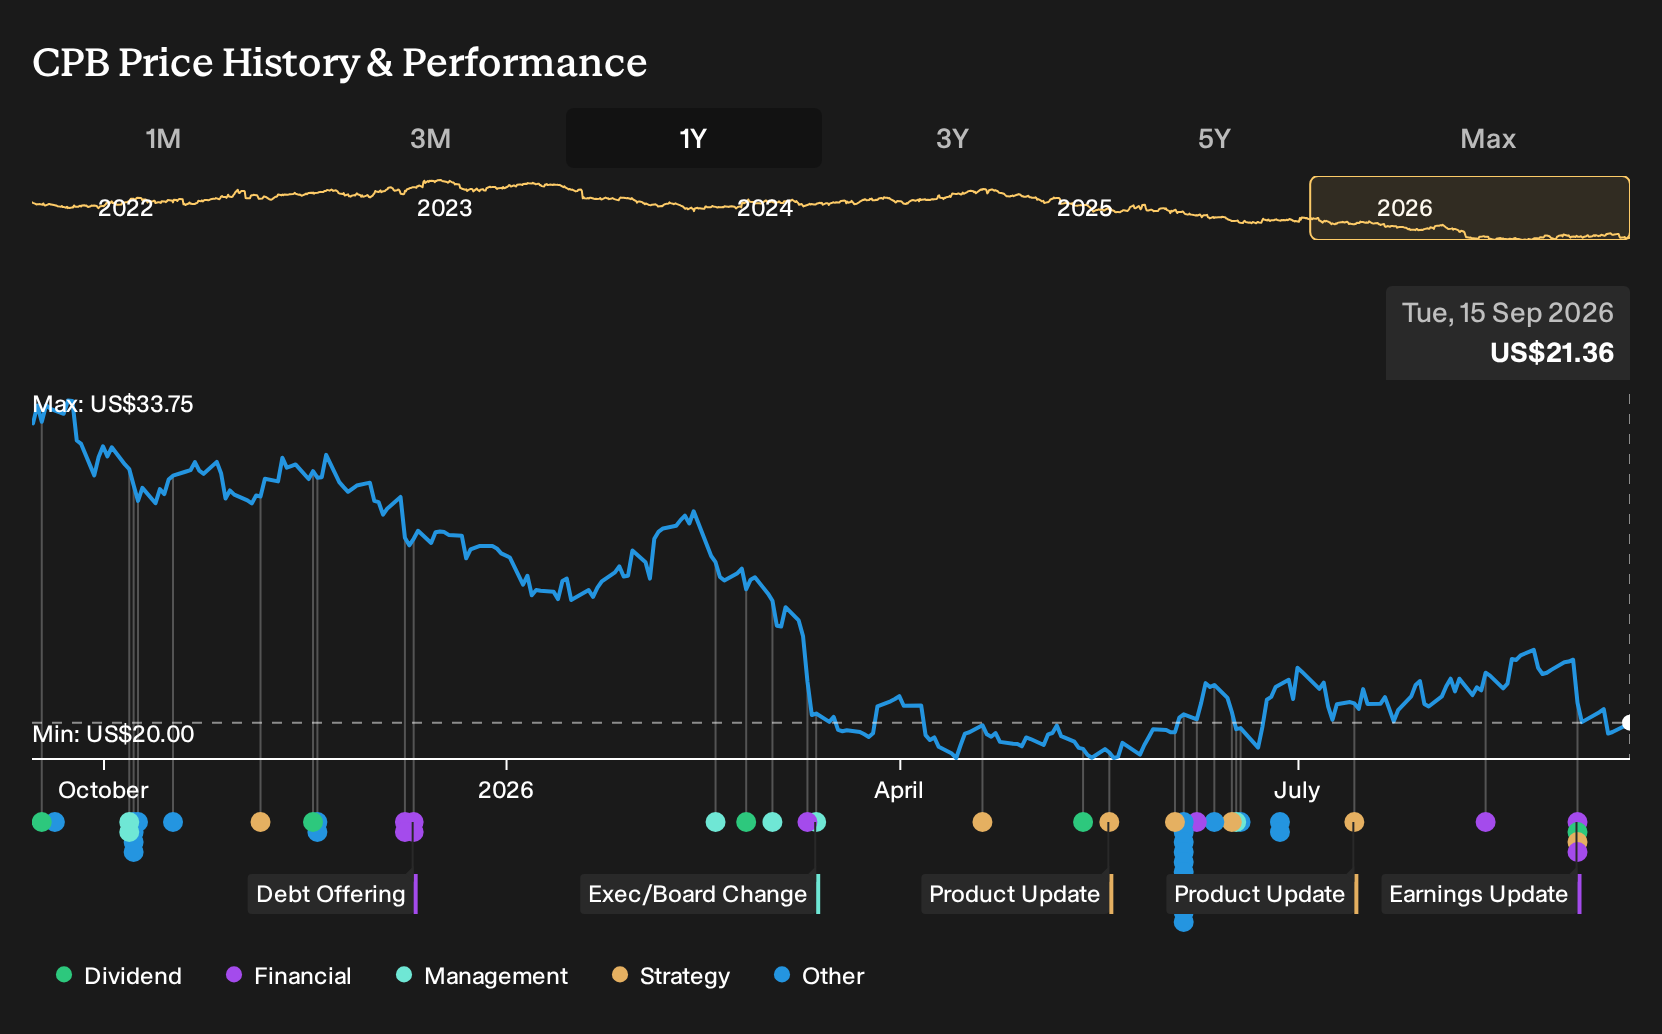
To own Campbell's, you need to be comfortable with a steady, low growth packaged food business that is working through margin pressure and softer demand in key categories. The near term story hinges on stabilising earnings after a tough fiscal 2026, with weaker Q4 results and lower net margins. The sauces launch speaks to convenience focused demand, but looks incremental rather than a major swing factor for the next few quarters.
The biggest near term risk is that volumes and pricing in core soups and snacks do not offset higher costs, especially with input cost and tariff pressures already weighing on profitability. A second concern is execution on cost savings without hurting brand health. In that context, the new two step sauces feel more like a test of Campbell's innovation muscle than a decisive earnings catalyst.
The most directly relevant recent announcement is the fiscal 2026 earnings release. Management reported Q4 sales of US$2,137 million versus US$2,321 million a year earlier, and a net loss of US$65 million compared with net income of US$145 million. For the full year, revenue was US$9,744 million and net income US$398 million, both below the prior year.
Those numbers frame why the sauces launch matters. Campbell's is looking to re energise Meals & Beverages after weaker snacks performance and impairment charges on Kettle Brand and Cape Cod trademarks. For you as an investor, the key question is whether convenience orientated products like these sauces can help support more resilient volumes while the business works through margin pressure, slower expected sales in fiscal 2027 and a lower dividend payout.
Campbell's narrative projects US$10.4b revenue and US$895.6 million earnings by 2029. This implies 1.5% yearly revenue growth and an earnings increase of about US$287.6 million from current earnings of US$608.0 million.
Discover why Campbell's fair value appears to be essentially in line with its current price.
Exploring Other Perspectives
One alternative view focuses on margin pressure rather than convenience upside. The most bearish analysts were modelling flat revenue around US$9.7b and earnings of only US$541.8 million by 2029, well below the consensus US$895.6 million. Those estimates came before this Campbell's Sauces launch, so you may see opinions shift as analysts reassess the story.
Explore 3 other Campbell's fair value estimates, including one that suggests as much as 34% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Campbell's research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Campbell's. The report includes a comprehensive fundamental analysis summarized in a single visual: the Snowflake, making it easy to evaluate Campbell's overall financial health at a glance.
Looking For More Campbell's Style Investment Ideas?
If Campbell's helps frame how a resilient, cash generative business can fit into your portfolio, it can be useful to compare that profile with other companies screened on fundamentals, income potential and risk.
- If you want dependable cash flows and strong balance sheets to sit alongside Campbell's, consider building a watchlist starting with a list of solid balance sheet and fundamentals (22 results).
- For investors focused on price discipline and quality, you might source fresh ideas from a carefully filtered set of 34 high quality undervalued stocks.
- Income orientated portfolios can benefit from broader diversification, so it may be worth scanning a curated group of 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com