
DXC Technology (DXC) Stock May Be Undervalued After A 65% Fall
DXC Technology has seen its share price move around in recent years, and the latest leg of trading leaves investors asking a simple question. Is the current US$12.04 price tag properly grounded in what the company actually earns.
- Over the past 5 years, DXC Technology shares have fallen 65.1%, which puts the current price debate squarely on whether the earnings story has changed enough to justify where the stock now trades.
- Recent commentary from DXC on AI security and tighter control over how AI agents access sensitive systems can shape expectations for future profitability if clients decide that this kind of offering supports more resilient demand and potentially steadier margins.
- Your read on DXC Technology is one view; the desks covering it have another. See what analysts think DXC Technology's shares could be worth.
The issue now is whether DXC Technology's current share price is reasonably aligned with its earnings when judged against the Fair Ratio benchmark.
If you are weighing whether DXC Technology's earnings justify its US$12.04 share price, it can help to compare that same question across 34 high quality undervalued stocks
Does DXC Technology Look Undervalued on Earnings?
For DXC Technology, the P/E ratio is a straightforward way to see what the market is willing to pay for its current earnings profile.
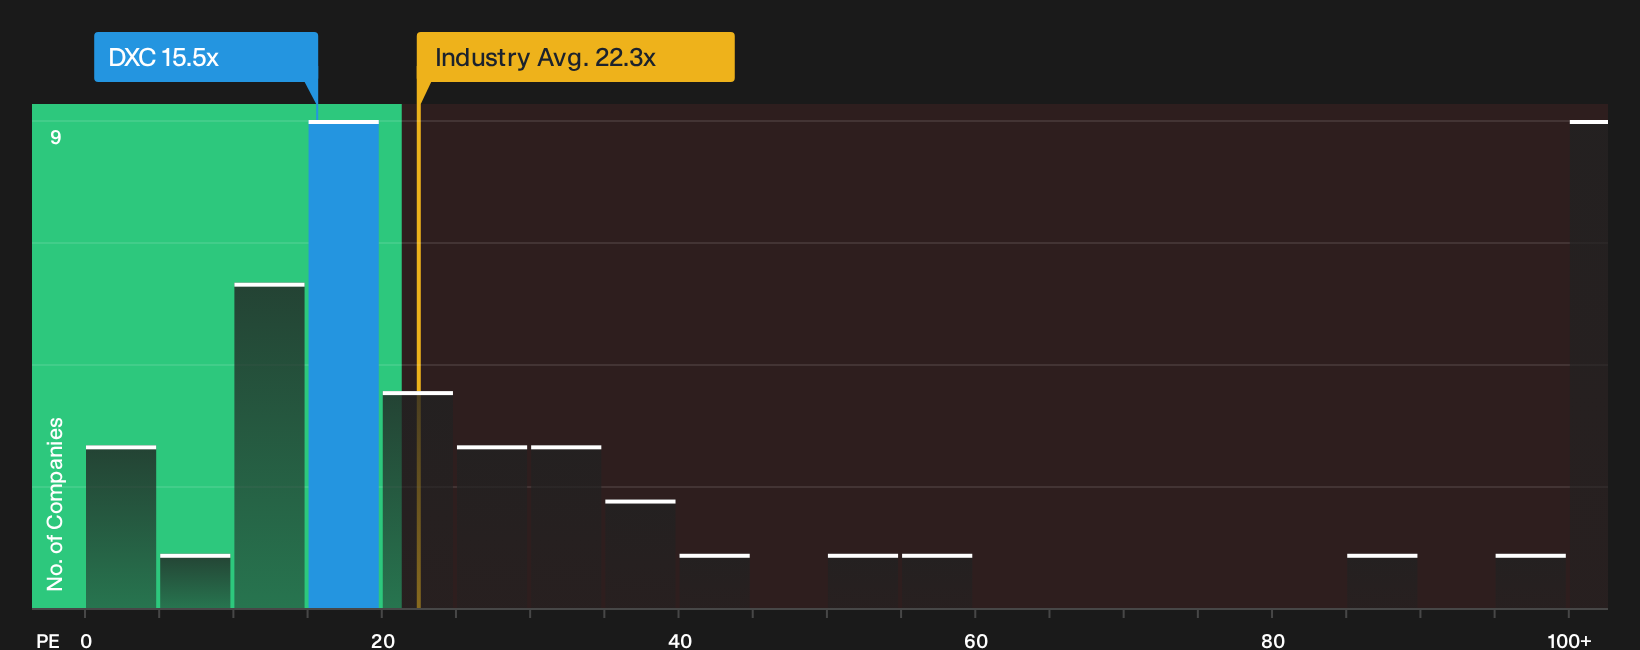
The stock trades on roughly 15.5x earnings, which sits below both the IT industry average of about 22.3x and the peer group near 19.8x. Based on the Fair Ratio, which reflects the kind of multiple that might fit DXC Technology given its business mix, scale and risk profile, the current P/E represents a discount rather than a premium. Because DXC has been talking up its AI security offering and action level controls, the gap suggests investor enthusiasm around that theme has not translated into a richer earnings multiple yet. Explore the numbers behind DXC Technology's P/E valuation.
The DXC Technology Narrative: What Would Justify Today's Price?
Narratives on DXC Technology pick up where the valuation puzzle leaves off and explain which growth, margin and earnings paths would need to align for the stock to be worth meaningfully more or less than today’s price. These narratives live on Simply Wall St’s Community page as concrete, trackable views on where DXC Technology's growth, profitability and risks might head next, and you can revisit them as fresh information becomes available.
The community is split on DXC Technology, with one group seeing potential upside in AI-heavy contracts and another concerned that legacy pressures still have a greater impact.
Bull case: 14% undervalued
"DXC's unique end-to-end capabilities across cloud, infrastructure, applications, and cybersecurity, together with heightened global demand for digital transformation and managed hybrid IT environments…"
Discover why this Narrative puts DXC Technology at 14% undervalued.
Bear case: 34% overvalued
"The rapid acceleration of digital transformation and automation among enterprise clients is increasingly shifting preference toward cloud-native and digital-first competitors, which poses a substantial risk…"
Explore why this Narrative puts DXC Technology at 34% overvalued.
DXC Technology's price is only one piece of the decision
Valuation tells you what investors are paying today, but the research community is also mapping out where DXC Technology could be a few years from now, and that second lens can change how you read the current multiple. Explore where analysts expect DXC Technology to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com