
Lumentum Holdings (LITE) Could Be 84% Undervalued Following Its 7.5% Selloff
Lumentum Holdings (LITE) remains in focus after a 7.5% share price drop during a sector-wide selloff in communication equipment stocks, a move that mirrored peers without fresh company specific headlines.
The latest 7 day share price return of down 14.3% for Lumentum Holdings sits against a year to date share price return of 117.3%. The 1 year total shareholder return of about 4x hints that momentum has cooled recently but remains very strong over a longer horizon as investors reassess growth potential and risk around AI driven optics demand.
Scan how Lumentum Holdings fits into the wider AI hardware story by comparing it with hand picked 60 AI infrastructure stocks that are riding the same data center optics theme.
Lumentum Holdings now combines a fast growing AI optics business with a share price that just pulled back hard. The real tension is whether that recent wobble leaves the stock still rich or finally reasonable.
Most Popular Narrative: 84% Undervalued
Lumentum Holdings last closed at $838.96, while the most followed narrative pegs fair value far higher at $5,085.95. That gap frames the whole AI optics debate around how much of the turnaround is already embedded in the share price.
The numbers look dramatic: revenue has surged, gross margins have vaulted into the mid-40s, and the market now values Lumentum at $73.67 billion. Yet the prior sections paint a grittier picture, one of a heavy-asset components manufacturer in the path of a massive but lumpy AI infrastructure cycle.
See why 27 investors see Lumentum Holdings as 84% undervalued.
Result: Fair Value of $5,085.95 (UNDERVALUED)
Still, the Lumentum Holdings story can flip quickly if hyperscaler orders slow, or if rare earth supply disruptions squeeze margins and unsettle that undervalued narrative.
Find out about the key risks to this Lumentum Holdings narrative.
Another View: Lumentum Holdings Through Market Multiples
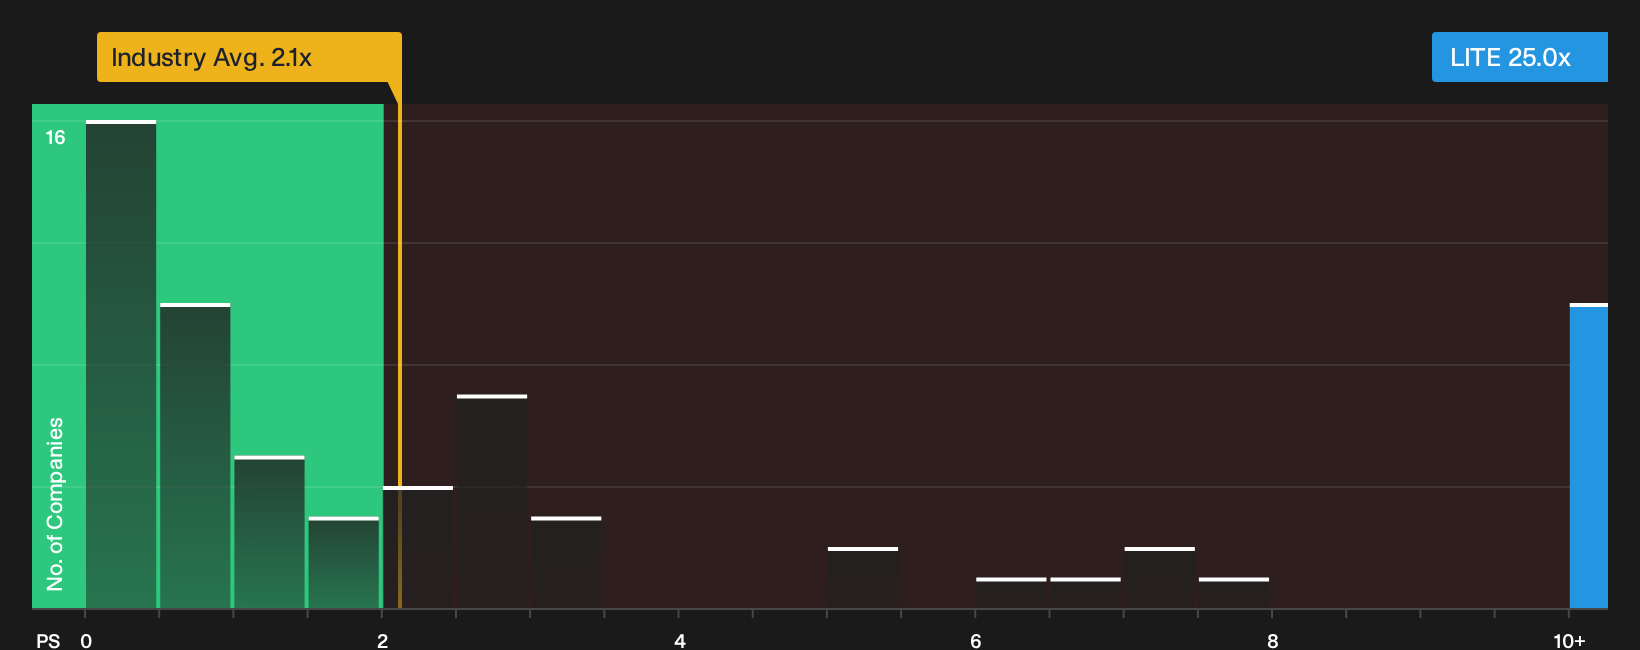
Lumentum Holdings looks very different once you switch from the SWS DCF model to simple sales-based pricing. The stock trades on a P/S ratio of 25x, compared with a fair ratio of 20x and a US Communications industry average of 2.1x, while peers sit around 11.9x. That kind of gap increases valuation risk if there is any setback in the AI optics story.
Investors who rely on ratios rather than cash flow models may want to consider what the numbers imply before taking a strong view. This is particularly relevant when the current P/S sits above the fair ratio that the market could move toward over time, which is unpacked in See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals across Lumentum Holdings can be confusing, so move quickly from headline takes to your own judgment using the underlying numbers and narratives. To see both sides of the argument in one place and pressure test your view against the data, check out the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Lumentum Holdings?
If Lumentum Holdings has sharpened your curiosity, do not stop here. Use focused screeners to spot other opportunities that fit your style before the crowd does.
- Target potential mispricing by scanning a curated set of 34 high quality undervalued stocks that pair quality fundamentals with prices that may not fully reflect them yet.
- Prioritise resilience by focusing on companies with a list of solid balance sheet and fundamentals (22 results) so you are not relying only on hope when conditions get tougher.
- Hunt for fresher stories with a 16 high quality undiscovered gems list that highlights financially sound businesses still flying under most investors' radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com