
Can SeSa (BIT:SES) Stock Justify Its Premium With A 2% Margin?
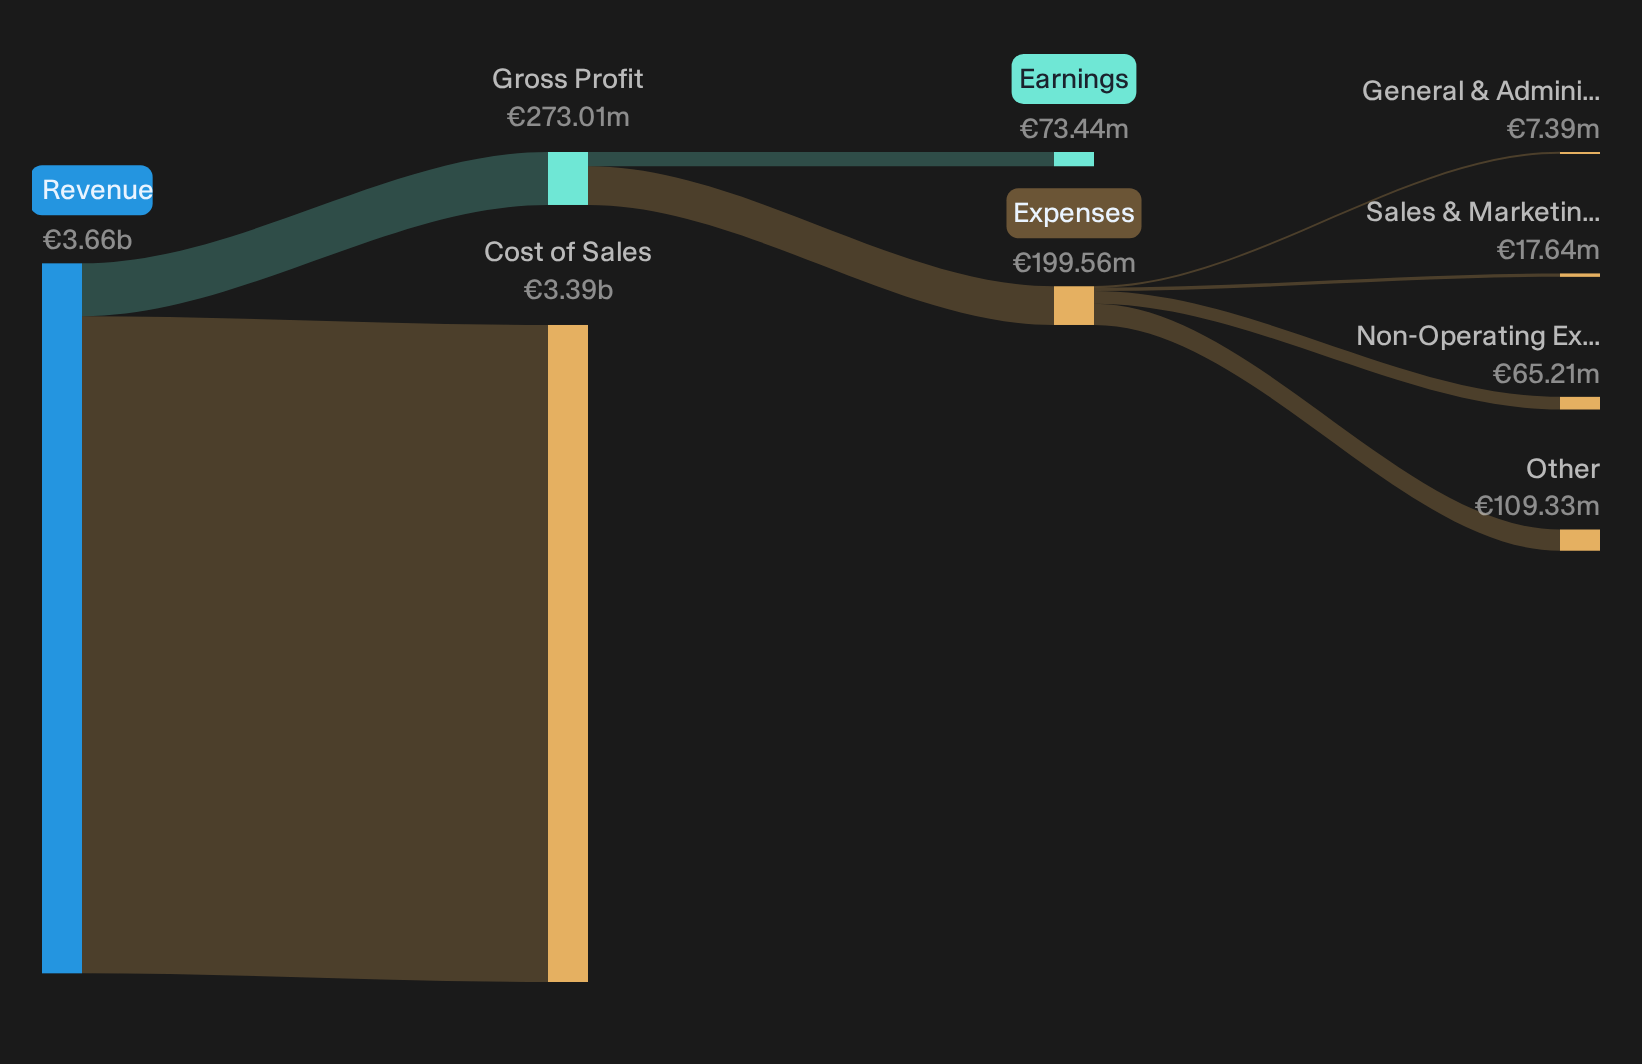
SeSa stock has cooled off in recent months, drifting about 5% lower over the past quarter to close near €94.5 on Tuesday. The share price looks tired, yet the latest quarter lands with a very different message. Q1 2027 delivered roughly €896 million in sales and about €23 million in underlying profit, and the real story sits on the income statement.
The key plot point is margin pressure. Earnings are still positive but thin, and at a P/E of about 19.5x investors now have to decide whether a modest 2% net margin justifies paying a premium to many peers.
Love SeSa’s scale and steady profits but worried about that slim 2% net margin at a mid-teens P/E? Check out our screener of sturdier businesses with wider earnings spreads in the list of solid balance sheet and fundamentals stocks (195 results)
Q1 2027 Earnings Summary
- Revenue (Q1 2027 vs Q1 2026): €896.451 million vs. €838.129 million (up about 7.0%)
- Net Income (Excl. Extra Items, Q1 2027 vs Q1 2026): €23.336 million vs. €21.583 million (up about 8.1%)
- Basic EPS (Trailing 12 Months to Q1 2027 vs TTM to Q1 2026): €4.70962 vs. €4.040843 (up about 16.6%)
- Net Profit Margin (TTM to Q1 2027 vs TTM to Q1 2026): 2.0% vs. 1.9% (a modest improvement of 0.1 percentage points)
Prefer clean visuals instead of another dense wall of earnings tables and raw figures? See SeSa’s full financial picture, including a clear view of its profitability trend and income statement strength, in the company report for SeSa.
SeSa bull case meets key margin tests
Bulls argue SeSa can shift from hardware distribution toward richer digital services while keeping the income statement intact. Q1 FY27 goes some way to backing that up. ICT VAS, Green VAS and Business Services all posted higher EBITDA and healthier margins, with Green VAS at about 6.0% and Business Services near 21%. That mix leans toward the higher recurring and platform style revenues the upbeat story relies on. Management also kept guidance for FY27 revenue, EBITDA and adjusted EAT unchanged, which supports the claim that the industrial plan is tracking to schedule. Net debt of €23.4m, alongside roughly €200m of operating cash flow over the last year and around €80m of free cash flow, shows the balance sheet absorbing both capex and shareholder payouts without strain.
Bear case on margins and execution still alive
Skeptics worry that SeSa’s margin pressure, vendor dependence and patchy segment performance will keep earnings fragile. The quarter does not knock that concern out. Net margin on a trailing basis is still about 2.0%, only slightly higher than 1.9%, so profitability at group level remains thin. Software & System Integration recorded revenue that declined about 3% and EBITDA that fell roughly 2.5%. That is exactly the kind of uneven performance bears point to when they flag execution and acquisition integration risk. Hardware commoditization fears are not resolved either. ICT VAS margin sits in the mid single digits near 4.6%. This leaves limited room if pricing tightens or cloud and as a service models shift mix further. Higher compliance and cybersecurity investment also appear in the backdrop through ESG programs and ISO27001 rollout, which can keep operating costs elevated.
Compare SeSa’s internal progress on mix, margins and cash generation with how the street frames the risk and reward. See the consensus price target analysis for SeSa to check where analysts are setting their targets after this latest quarter.Own Your Next Investing Move
If SeSa’s thin 2% net margin and premium P/E have you watching closely rather than rushing in, register for free with Simply Wall St and add it to a Watchlist to track the share price against fair value and spot a price that fits your plan. After you take a position, use the Portfolio Command Center to cut through market noise and focus on the most important developments that affect your holdings. For long term decisions, lean on the Community to see how other investors interpret new data and emerging trends around SeSa and similar stocks. By surfacing hidden catalysts and risks early, Simply Wall St helps you stay ahead of the market instead of reacting after the fact.
Seeking Alternatives Beyond SeSa?
Fresh ideas tend to move first, not last. New themes can build momentum, then become crowded and priced in quickly. Scan these curated stock lists before they are fully caught, and consider them promptly.
- Explore durable cash engines with healthy balance sheets and pricing power by scanning our curated list in the list of solid balance sheet and fundamentals stocks (195 results)
- Identify early leaders in AI infrastructure where demand may develop before the broader market fully focuses on them by reviewing the hand picked group inside the 60 AI infrastructure stocks
- Look at resilient power grid opportunities connected to energy transition spending and grid upgrades by running through the carefully filtered stocks in the 38 power grid technology and infrastructure stocks
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com