
How Investors May Respond To Vaisala Oyj (HLSE:VAIAS) Data Center Service Launch
- Vaisala Oyj has launched Vaisala Care for Data Centers, a dedicated service portfolio that supports lifecycle calibration, verification and uptime for measurement systems across hyperscale, colocation and enterprise facilities, including options that extend to approved third party devices.
- The service suite adds a recurring support and calibration layer on top of Vaisala Oyj’s Indigo, Origo and compact probe hardware. This could influence how much of the data center opportunity comes from ongoing service relationships rather than one off equipment sales.
- We will now explore how Vaisala Oyj’s data center focused service model could reshape the investment narrative around recurring revenue and resilience.
Scan how Vaisala Oyj’s new service layer fits into a broader uptime theme across critical infrastructure by tracking peers in our 38 power grid technology and infrastructure stocks.
Vaisala Oyj Investment Narrative Recap
To own Vaisala Oyj, you need to believe its measurement expertise can keep finding new, resilient end markets while cyclical drag in renewables and public meteorology eventually eases. The key near term driver is whether Industrial Measurements and higher quality recurring revenue can offset any softer project demand and currency pressure on a euro cost base.
Vaisala Care for Data Centers fits that belief only at the margin right now. The launch broadens recurring service exposure and leans into uptime sensitive infrastructure, but the immediate financial impact is unclear. The main risk remains prolonged weakness in wind, aviation and public sector orders that keeps earnings growth below expectations.
The Vaisala Care portfolio for data centers lines up cleanly with the push toward more subscription like and service based income, similar to what investors already see in Xweather and other digital offerings. This provides another concrete example of the company tilting away from one off hardware toward lifecycle support in a mission critical setting.
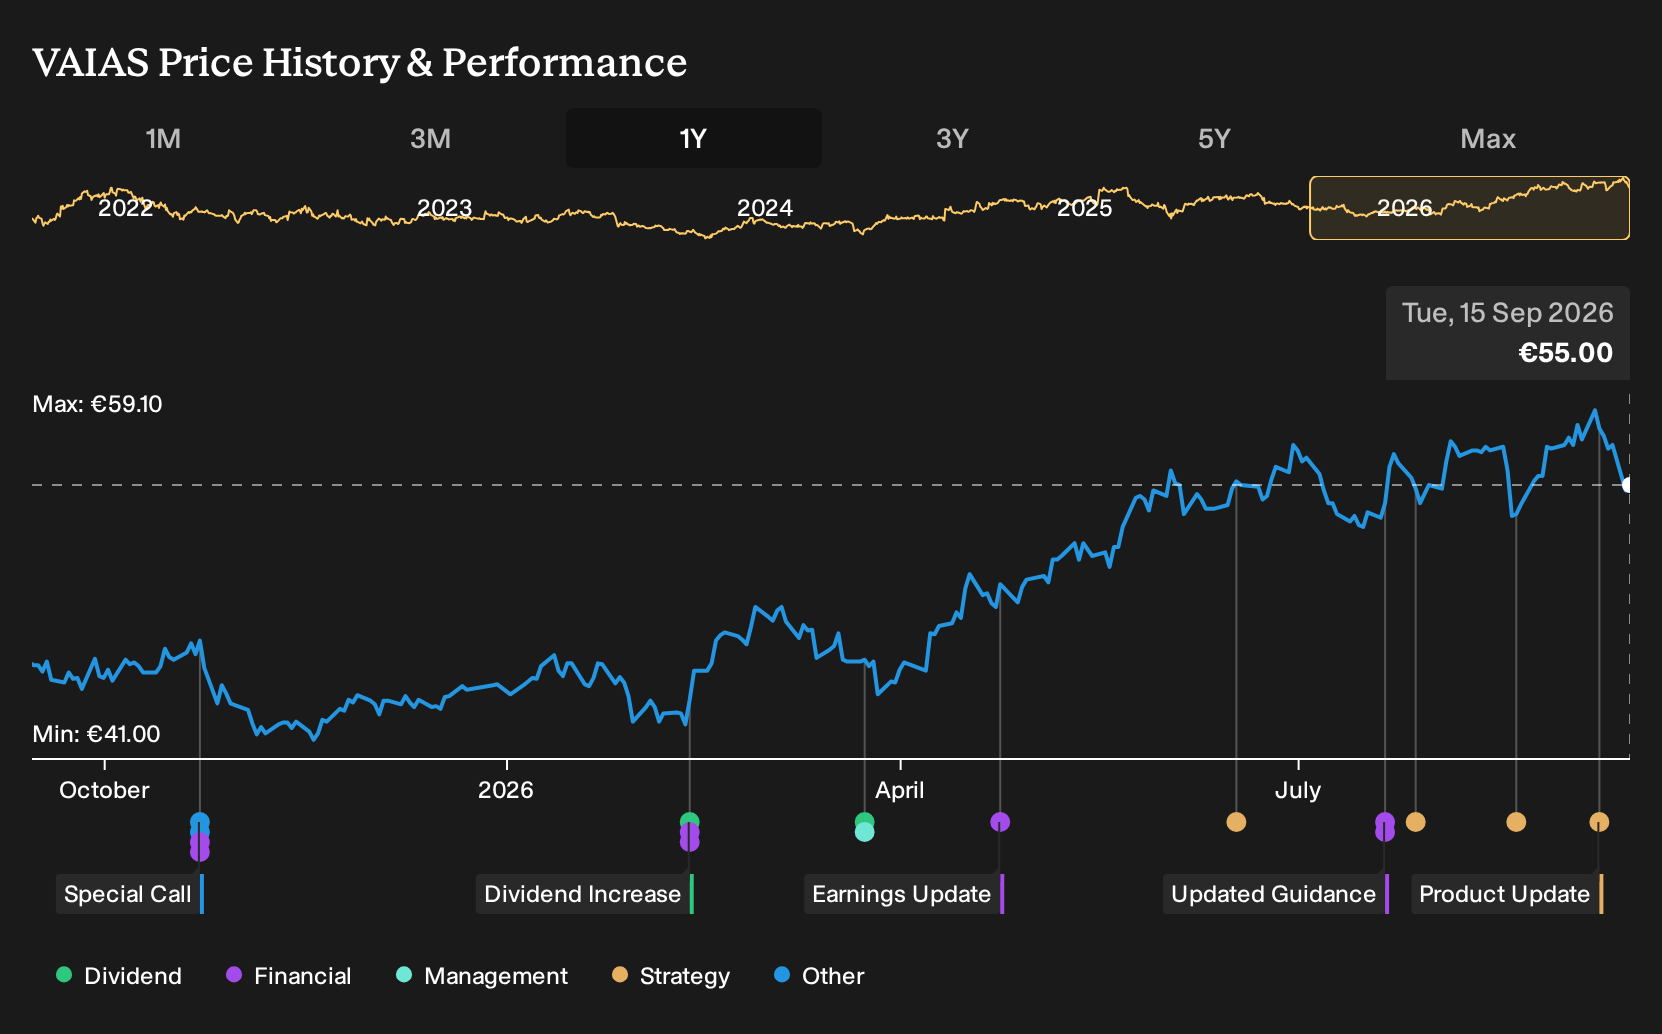
This move also interacts with valuation. The stock trades on a premium P/E versus European electronics peers, while analysts model mid teens earnings growth and 6.3% annual revenue expansion. For that multiple to remain comfortable, execution on offerings such as Vaisala Care would need to show up in steadier orders, a healthier mix and less earnings volatility through cycles.
Vaisala Oyj's current analyst narrative points to revenues of €713.4 million and earnings of €93.4 million by 2029, based on an assumed 6.0% yearly revenue growth rate and an earnings increase of about €31.9 million from €61.5 million today.
Uncover why Vaisala Oyj's fair value indicates a 4% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community cluster tightly between €57.2 and €59.2, so none flag extreme mispricing yet. Those opinions still ignore Vaisala Oyj’s new data center services. If you factor in potential pressure from weaker renewables or support from expanding digital and lifecycle offerings, you may arrive at very different conclusions. Consider reading several community viewpoints before deciding how this fits your own thesis.
Explore 2 other Vaisala Oyj fair value estimates, including one that suggests up to 8% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Vaisala Oyj research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Vaisala Oyj. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vaisala Oyj's overall financial health at a glance.
Looking For More Ideas Beyond Vaisala Oyj?
Once you have a view on Vaisala Oyj, it can help to compare it with other opportunities that match different goals, risk levels and income needs. The Simply Wall St Screener can surface companies that fit tight criteria so you can focus on a shorter, more relevant watchlist instead of wading through the whole market.
- If capital preservation and smoother return profiles matter most to you, start with a basket of 102 resilient stocks with low risk scores that may better match a more defensive approach.
- If balance sheet strength is non negotiable, consider filtering for a list of solid balance sheet and fundamentals (195 results) so you can focus on businesses with sturdier financial footing.
- If you want to widen the opportunity set beyond well known stocks, cast the net over a 622 high quality undiscovered gems that could sit under the radar but still have meaningful fundamentals behind them.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com