
How Investors May Respond To T1 Energy (TE) Clearway Supply Deal
- T1 Energy reported second-quarter 2026 results in August, with higher net sales and module output but continued net losses, alongside new TOPCon patents and the completed KORE Power acquisition.
- The long-term Clearway Energy Group module supply deal, supported by domestic-cell production at the G2_Austin facility, shifts T1 Energy further toward a vertically integrated, U.S.-focused solar and storage platform.
- We will now explore how T1 Energy's Clearway supply agreement could reshape the investment narrative around its policy-backed expansion.
T1 Energy Investment Narrative Recap
To own T1 Energy, you need to believe the policy backed U.S. solar and storage buildout will translate into sustained demand for its modules and cells, and that domestic manufacturing can support acceptable unit economics. The latest quarter showed higher net sales and output but continuing losses, so the near term story is still about scaling production while containing cash burn.
Right now, the key catalyst is execution at G2_Austin and G1_Dallas, backed by long term contracts. The biggest risk is that capital needs, policy shifts, or pricing pressure in a competitive solar market undercut that ramp. The recent results and announcements meaningfully sharpen both sides of that equation.
The Clearway Energy Group module supply agreement looks most relevant here. It ties 641 MW of demand directly to T1 Energy’s planned domestic cell production at G2_Austin, giving clearer visibility on how new capacity could be absorbed once construction progresses and lines begin to run at scale.
For you as a shareholder, that contract helps anchor the growth side of the story, while the ongoing net loss and intensive working capital needs keep funding risk front and center. The Clearway deal does not remove reliance on U.S. incentives or volatile module pricing. It shows that large utility buyers are willing to commit to T1 Energy’s U.S. focused platform, which is important for the next few years of execution.
T1 Energy's current analyst narrative projects US$1.9b in revenue and US$172.0 million in earnings by 2029. This projection assumes revenue growth of 23.3% per year and an earnings change of about US$502.1 million from a current loss of US$330.1 million.
Uncover why T1 Energy's fair value indicates a 115% potential upside to its current price, which could narrow quickly.
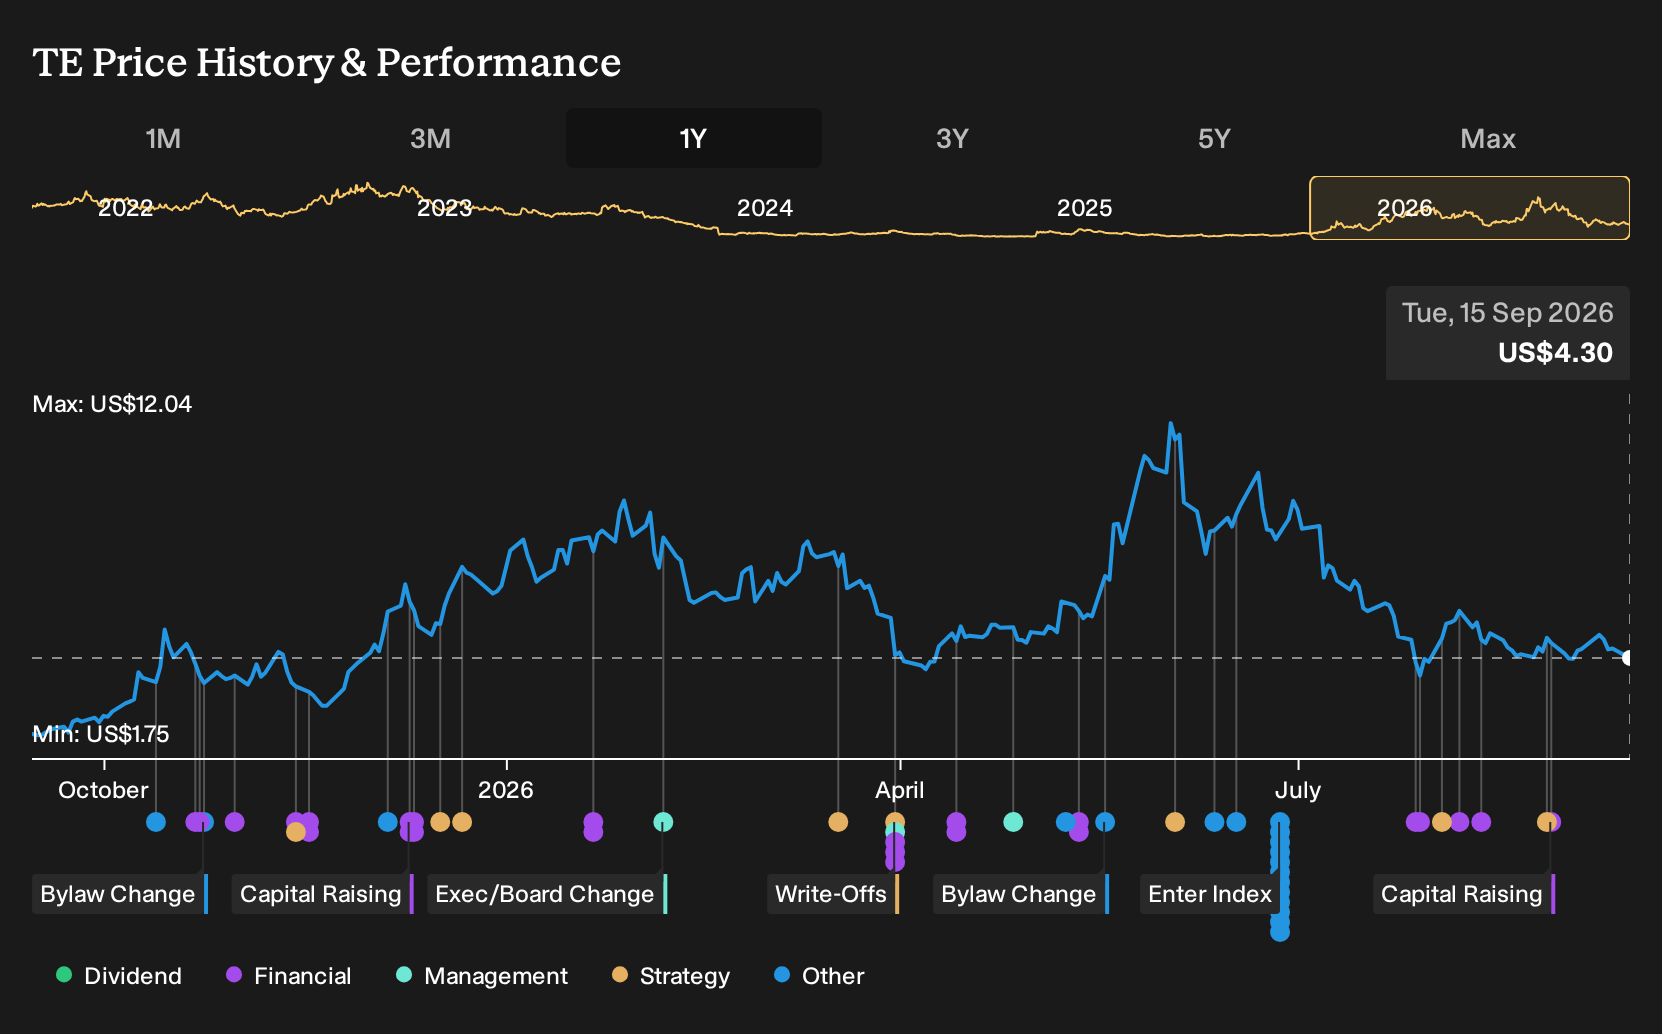
Exploring Other Perspectives
One alternate view on T1 Energy leans hard into utilization risk. In that story, U.S. power demand plateaus, G1 and G2 capacity sits underused, and the lowest analysts work off leaner numbers. They were pencilling in about US$1.8b of 2029 revenue and US$125.0 million of earnings before this news. That gap shows how widely opinions can vary, so it makes sense to weigh several angles and decide which narrative feels closer to yours, especially as the Clearway deal and KORE Power acquisition start to filter into future models.
Explore 3 other T1 Energy fair value estimates, including one that suggests it could be worth just $9.25!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your T1 Energy research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for T1 Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate T1 Energy's overall financial health at a glance.
Looking For More Ideas Beyond T1 Energy?
If the T1 Energy story has you thinking about how policy backed themes, cash flow resilience, or income potential fit into your wider portfolio, it can help to line it up against a wider bench of candidates using the Simply Wall St Screener.
- For investors hunting for potential upside in beaten down areas, scan a focused group of 2 elite penny stocks with strong financials that already show stronger financial underpinnings than the typical micro-cap.
- If capital preservation sits high on your priority list, weigh T1 Energy against a curated pool of 11 resilient stocks with low risk scores that pair steadier balance sheets with more measured risk profiles.
- For those building an income stream alongside growth ideas, round out your watchlist with 6 dividend fortresses that combine higher yields with more resilient fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com