
GoDaddy (GDDY) Stock May Be Below Fair Value On Earnings Power
GoDaddy shares closed at US$102.38 recently, after a mixed run that includes a strong multi year gain alongside a weaker stretch over the past year. With that backdrop, the question for you is whether this price is still supported by the company’s earnings power.
- Over the past 5 years the stock has returned 45.2%, which puts real weight on whether the current earnings justify the compounding already in the share price.
- The business generates its revenue from subscription style services and add ons for online presence, which can support more predictable earnings and puts the spotlight on how efficiently those profits are converted into cash.
- Your read on GoDaddy is one view; the desks covering it have another. See what analysts think GoDaddy's shares could be worth.
The issue now is whether GoDaddy’s current share price is justified by the earnings that the business is producing today.
If you are weighing whether GoDaddy's earnings still support a US$102 share price, it can help to compare that question across 34 high quality undervalued stocks.
Is GoDaddy Still Cheap on Earnings?
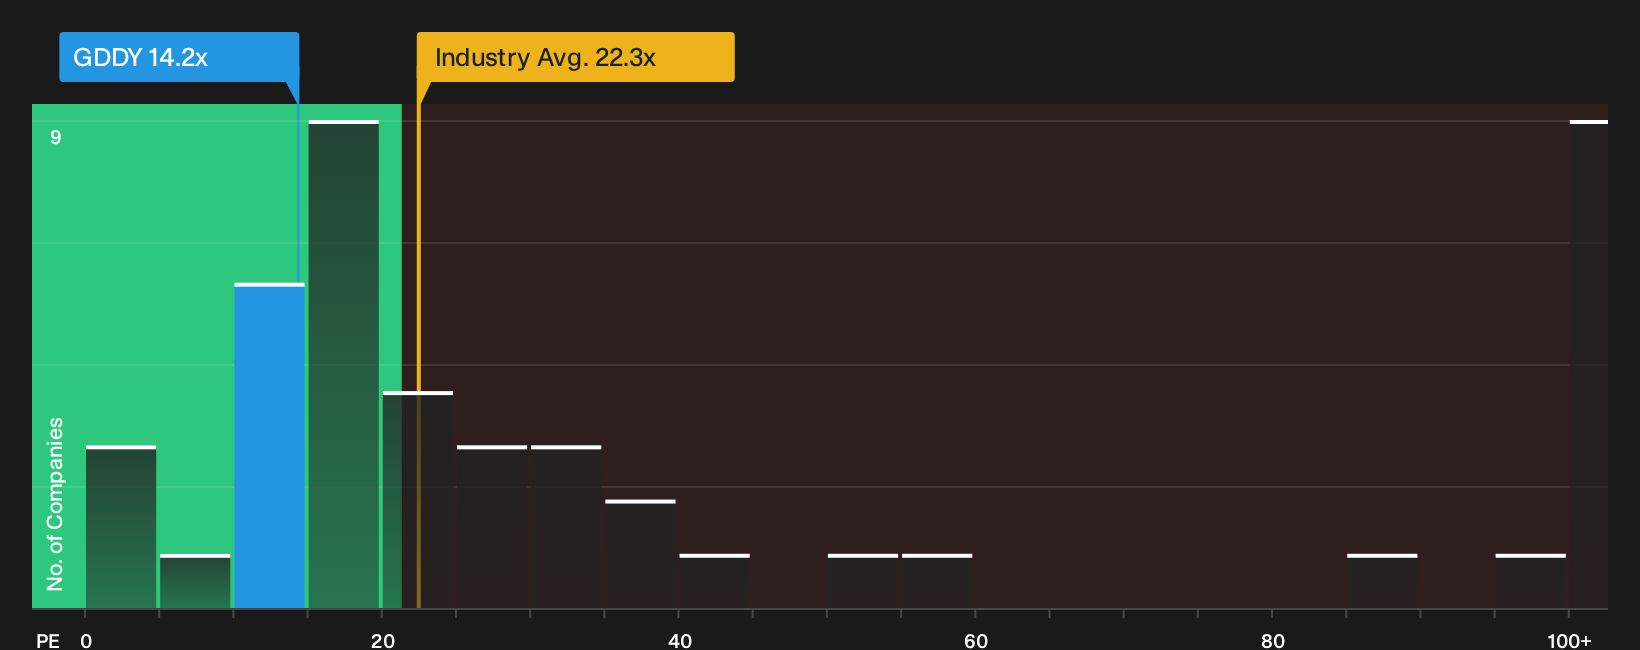
The P/E ratio works well for GoDaddy because earnings are a key driver for a subscription heavy software business. On this metric, GoDaddy trades on a P/E of 14.2x, compared with an IT industry average of about 22.3x and a peer group around 34.6x. That is a clear gap between what the market pays for each dollar of GoDaddy’s earnings and what it pays for many other software and internet services stocks.
The Fair Ratio, which adjusts for factors like GoDaddy’s profit profile, size and sector, points to a higher P/E than the market is currently assigning. That puts the stock in undervalued territory on this framework, because the price looks low relative to the earnings level implied by that tailored benchmark. For anyone weighing whether US$102 per share is still underpinned by profits, the current P/E suggests the market is not charging a premium for GoDaddy’s earnings power. Explore the numbers behind GoDaddy's P/E valuation.
The GoDaddy Narrative: What Would Justify Today's Price?
Narratives for GoDaddy pick up where the P/E puzzle leaves off by setting out the specific paths for growth, margins, and earnings that would need to occur for the current share price to look meaningfully higher or lower than it is today. Instead of a single valuation output, they translate that figure into a clear set of future checkpoints so you can watch how GoDaddy's actual progress lines up with the expectations embedded in the stock.
GoDaddy attracts two sharply different read throughs right now, with one camp seeing meaningful upside and another arguing expectations have run ahead of execution.
Bull case: 32% undervalued
"The unprecedented scale and automation achievable through Agentic AI, from customer onboarding to ongoing SEO and marketing optimization, will allow GoDaddy to deliver enterprise-grade services to SMBs at mass-market economics…"
Discover why this Narrative puts GoDaddy at 32% undervalued.
Bear case: 35% overvalued
"Bearish analysts highlight that GoDaddy is facing market share risk as AI overviews and large language models gain share in search discovery, while the company’s domain pricing sits above peers and is flagged as a reason AI search tools may point users to competitors…"
Explore why this Narrative puts GoDaddy at 35% overvalued.
One more GoDaddy signal worth checking before you move on
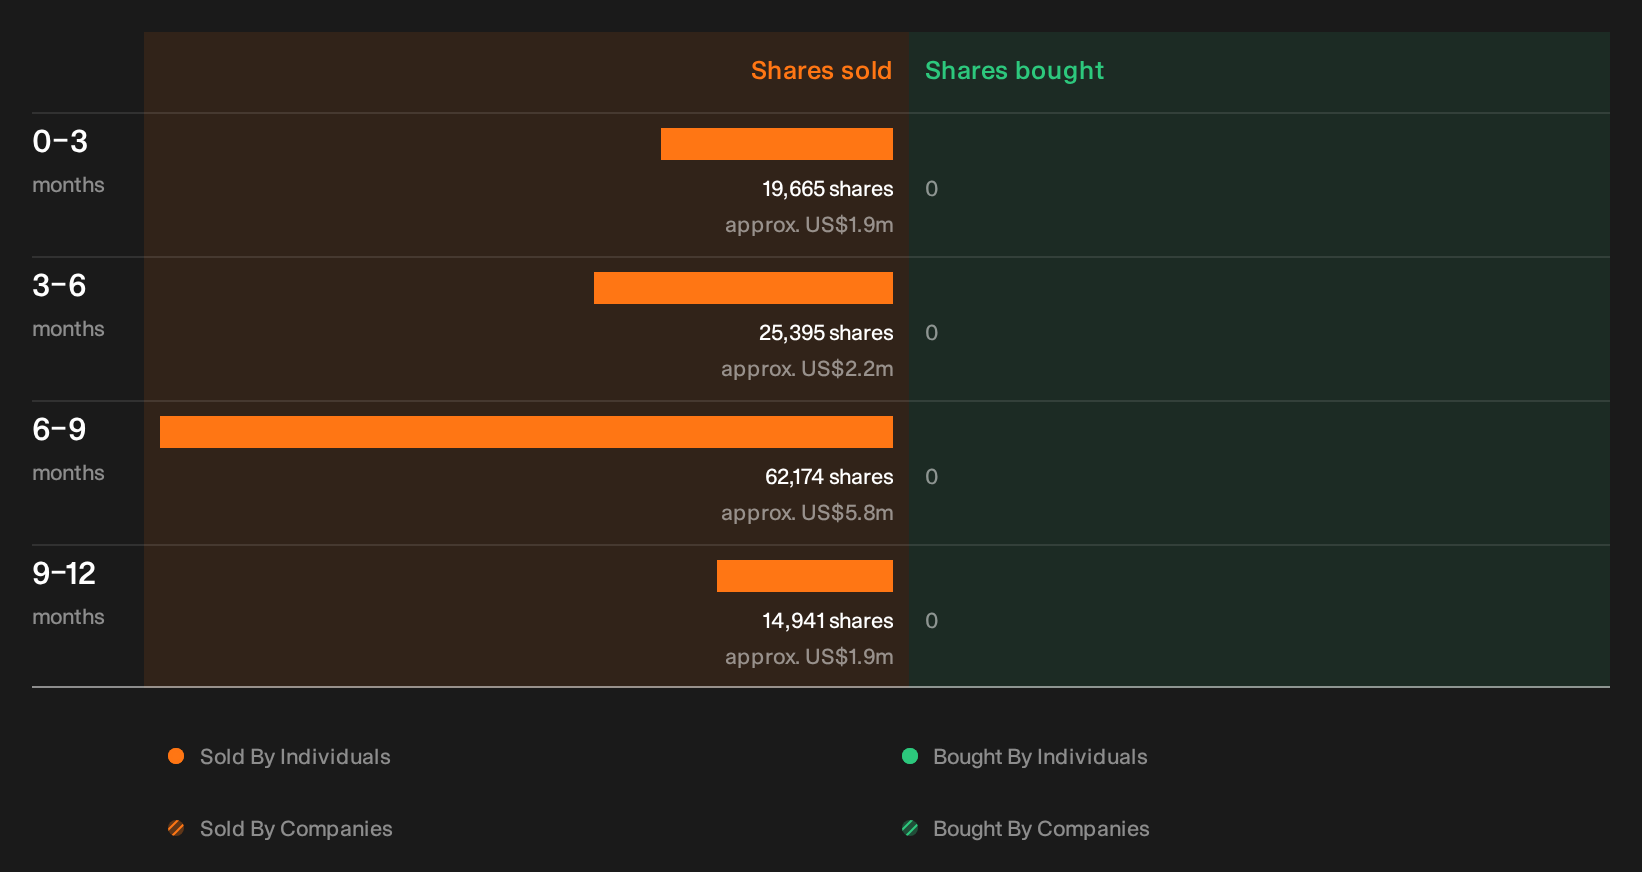
Before you close the book on GoDaddy, it is worth knowing that recent trading by those inside the business has been flagged, with the specific sellers, sizes and possible read throughs left for you to review. See the recent insider selling flagged for GoDaddy.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com