
GEO Group (GEO) Stock Could Look Pricey Despite Its Earnings Base
GEO Group has been on a striking multi year run, and with the stock changing hands at around US$31.26, the key question now is whether that price can be explained by its earnings power. The valuation puzzle for GEO Group today is less about the past share price path and more about how much profit the current business can reliably support.
- GEO Group has delivered a 344.0% return over the past 5 years, which puts real weight on whether the current earnings base can shoulder that kind of rerating.
- The business depends heavily on converting contracted correctional and monitoring services into stable profit, so the durability of those earnings streams may shape how much investors are prepared to pay for each dollar of income.
- There is a second opinion on GEO Group worth weighing. See what analysts think GEO Group's shares could be worth.
For investors, the debate is whether GEO Group's current share price is justified by the earnings it is generating today and is expected to produce over time.
If you are weighing whether GEO Group's 5 year rerating lines up with its earnings, a focused stock screen can give you more context through 34 high quality undervalued stocks.
Does GEO Group Look Pricey on Earnings?
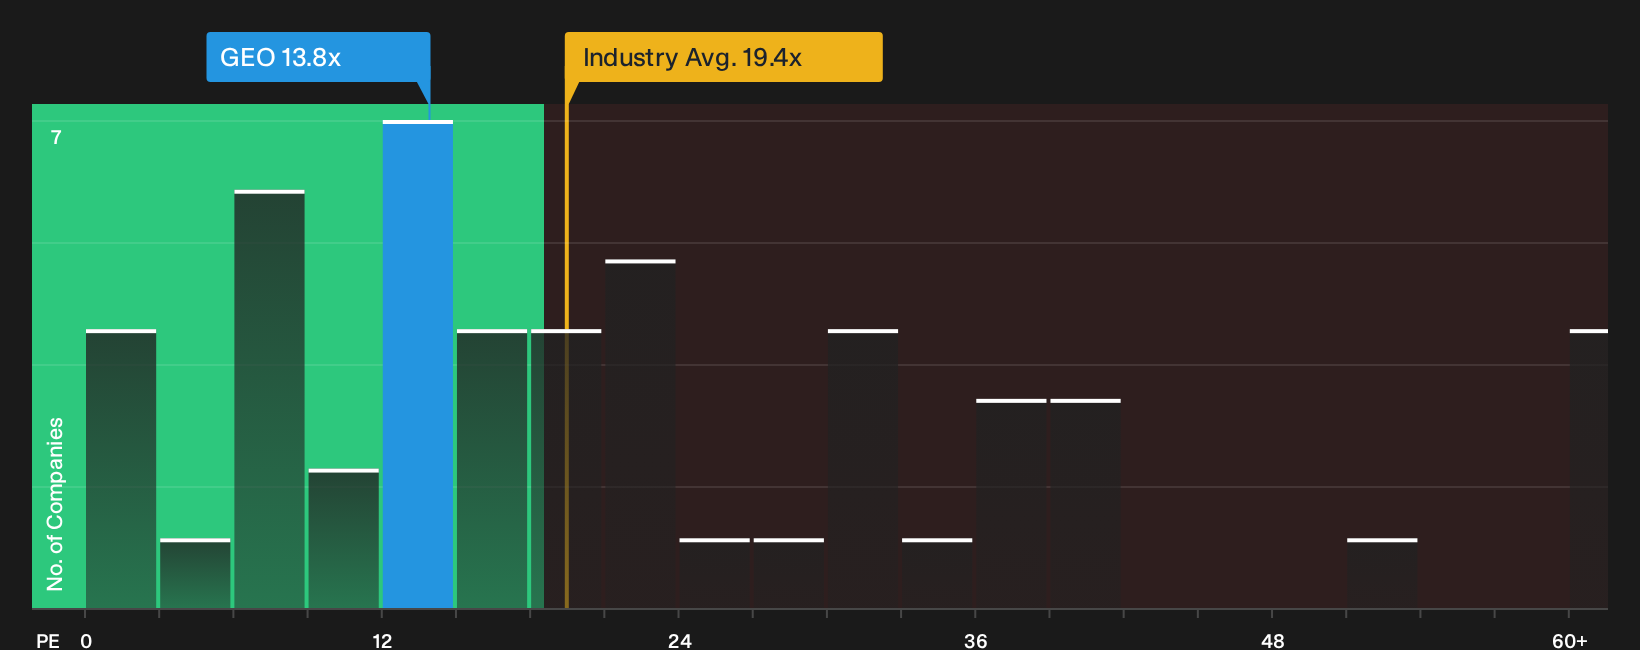
The P/E ratio is usually a straightforward way to think about what you are paying for each dollar of GEO Group earnings. At around 13.8x, GEO Group trades well below the broader Commercial Services industry average of about 19.4x, and also below the peer group average near 28.4x. This indicates the market is putting a noticeably lower earnings tag on this correctional services specialist than on many service sector stocks.
The Fair Ratio model, which adjusts the benchmark multiple for GEO Group's own size, profitability profile and risk, points to a lower figure than where the shares trade today. On this specific framework, the current 13.8x screens as overvalued. That gap suggests investors are already paying up for the existing earnings stream, so you would need to be comfortable that the quality and resilience of GEO Group's profits justify paying more than this tailored benchmark while still sitting at a discount to broad industry and peer P/E levels. Explore the numbers behind GEO Group's P/E valuation.
The GEO Group Narrative: What Would Justify Today's Price?
Narratives on GEO Group pick up where the P/E debate leaves off by spelling out which paths for future growth, profit margins and earnings would need to play out for today’s valuation to look either stretched or conservative. Each scenario on Simply Wall St’s Community page treats GEO Group's implied worth as a thesis about how the business might perform over time, so you can watch how that idea holds up against new information.
Community views on GEO Group are split between investors who see more upside in its contracted assets and those who focus on policy and contract risk.
Bull case: 17% undervalued
"Investment and inventory build-up for GPS tracking and electronic monitoring solutions position GEO as a primary provider to meet future shifts towards non-custodial immigration supervision…"
Discover why this Narrative puts GEO Group at 17% undervalued.
Bear case: roughly fairly valued
"Reliance on government funding and contract expansions is tempered by high execution risks, political shifts, and ongoing criminal justice reform pressures threatening future demand…"
Explore why this Narrative puts GEO Group at roughly fairly valued.
Before acting on GEO Group's valuation, there is one more piece to check
Share prices reflect earnings today, but over time the outcome often traces back to who is making the decisions and how that leadership is rewarded, which is a separate question entirely. See who runs GEO Group and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com