
STEF (ENXTPA:STF) Following Strong Half Year Earnings Still Looks Cheap On Valuation
STEF (ENXTPA:STF) is back in focus after its half year 2026 earnings update, with sales of €2,687.14 million and net income of €55.92 million drawing close attention from investors.
STEF’s share price has been choppy in the short term, with the stock down 3.48% over the past week and 4.64% over the past month. However, the 90 day share price return of 7.24% and 1 year total shareholder return of 8.50% suggest that longer term momentum has been stronger than the recent pullback implies.
Compare STEF’s earnings-driven move with other transport and logistics specialists that screen well on cash flows and balance sheets by scanning our hand picked list of solid balance sheet and fundamentals (195 results) today.
Impressive half year earnings, a mixed share price and a value score of 4 put STEF at an interesting crossroads. Does that combination still tilt the risk reward towards buyers, or has most of the easy upside already been taken?
Price-to-Earnings of 13x: Is it justified for STEF?
On a simple snapshot, STEF trades on a P/E of 13x, while analysts see only a limited gap between the current €127.4 share price and their €149 price target. This places the stock somewhere between clear bargain territory and outright enthusiasm.
The P/E ratio compares what you pay today for each euro of earnings. For a transport and logistics group like STEF, which depends heavily on steady contract volumes and efficient asset use, this measure gives a direct sense of how much the market is paying for its profitability profile.
STEF screens as good value versus both its own fair P/E estimate and its peer set. The stock trades on 13x earnings compared with a peer average of 16.6x. This points to a meaningful discount relative to similar French companies, while the estimated fair P/E of 16.1x suggests the current rating sits below a level the market could reasonably move toward if sentiment and fundamentals stay aligned.
At the same time, the comparison against the broader European transportation group points in a different direction. The same 13x multiple sits above the European Transportation industry average of 11.7x. This signals that investors are already assigning STEF a richer tag than many regional rivals, likely reflecting its high quality past earnings, improving margins and outperformance versus both the French market and the local transportation sector over the past year.
Explore the SWS fair ratio for STEF.
Result: Price-to-Earnings of 13x (UNDERVALUED)
Still, the short term share price weakness and STEF’s premium to the wider European transportation P/E leave the story exposed to any disappointment in earnings momentum.
Find out about the key risks to this STEF narrative.
Another View on STEF’s Valuation
The P/E check presents STEF as attractively priced, while the SWS DCF model points to something stronger. At €127.4, the shares are assessed as trading about 40.7% below an estimated future cash flow value of €214.94. If cash flows are the anchor, is the current quote still conservative?
Look into how the SWS DCF model arrives at its fair value.
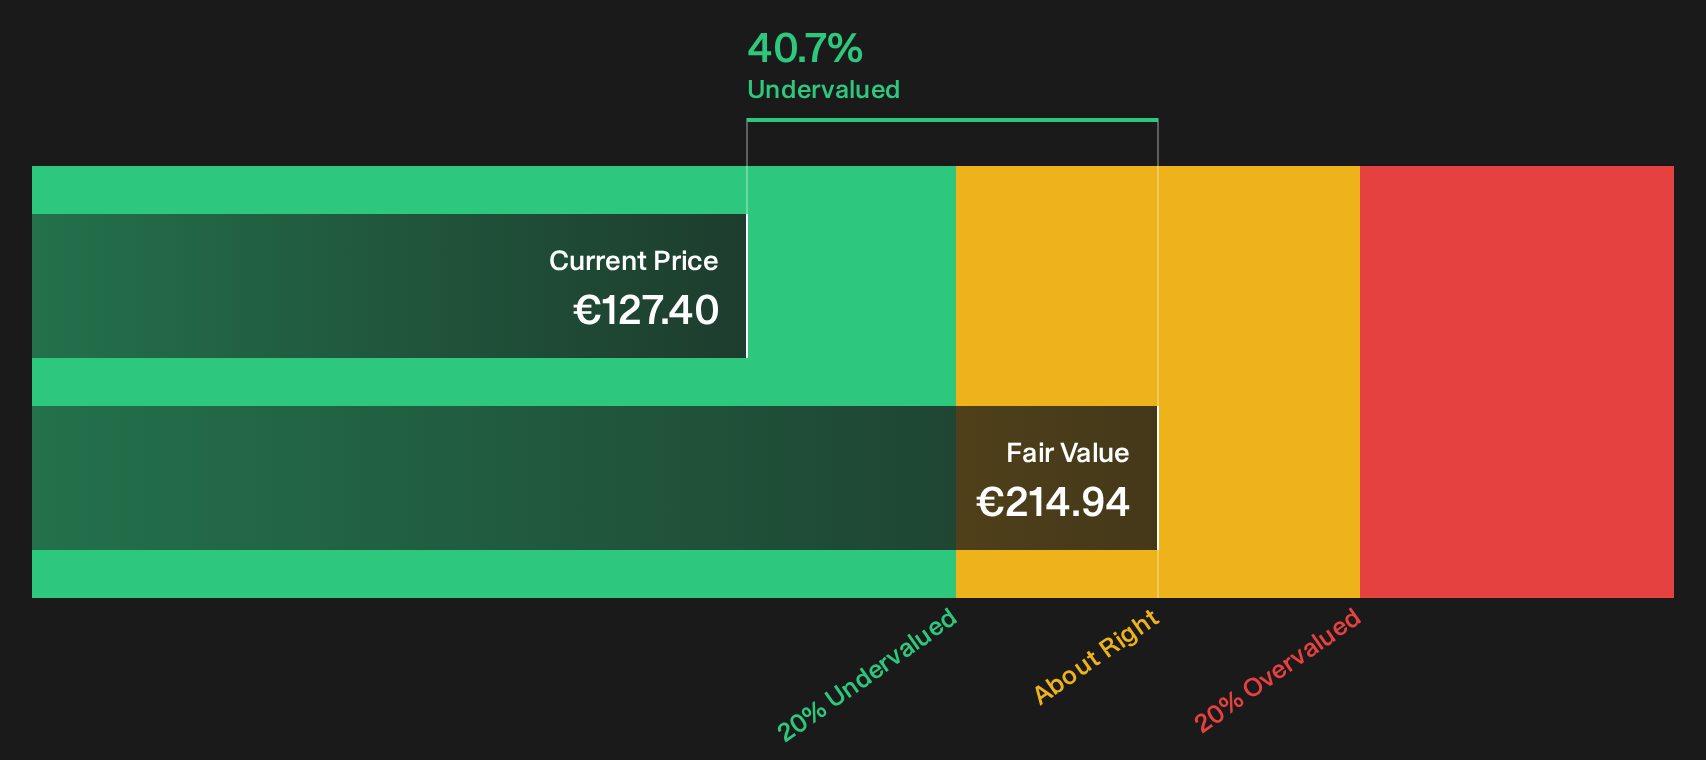
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out STEF for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 194 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Plenty of signals around STEF point in different directions, so the most useful next step is to test the numbers yourself and decide where you land. To weigh both sides of the story in one place, start with our breakdown of 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond STEF?
If STEF has sharpened your focus on valuation and quality, do not stop here. The broader market still holds plenty of opportunities you might miss.
- Target potential mispricing by screening for companies that combine resilient fundamentals with attractive valuations through our curated 194 high quality undervalued stocks.
- Strengthen your income stream by highlighting businesses that offer higher yields and robust payout profiles using the focused 160 dividend fortresses.
- Prioritise resilience by filtering for companies with strong balance sheets and dependable financial footing through the specialist 102 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com