
Loss-Making The Metals Royalty Company Inc. (NASDAQ:TMCR) Expected To Breakeven In The Medium-Term
With the business potentially at an important milestone, we thought we'd take a closer look at The Metals Royalty Company Inc.'s (NASDAQ:TMCR) future prospects. The Metals Royalty Company Inc. engages in the acquisition and management of metals and mineral royalties, streams, and other related interests in North America. With the latest financial year loss of US$6.8m and a trailing-twelve-month loss of US$23m, the US$331m market-cap company amplified its loss by moving further away from its breakeven target. Many investors are wondering about the rate at which Metals Royalty will turn a profit, with the big question being “when will the company breakeven?” In this article, we will touch on the expectations for the company's growth and when analysts expect it to become profitable.
According to the 3 industry analysts covering Metals Royalty, the consensus is that breakeven is near. They anticipate the company to incur a final loss in 2027, before generating positive profits of US$250k in 2028. The company is therefore projected to breakeven around 2 years from now. How fast will the company have to grow each year in order to reach the breakeven point by 2028? Working backwards from analyst estimates, it turns out that they expect the company to grow 77% year-on-year, on average, which is extremely buoyant. If this rate turns out to be too aggressive, the company may become profitable much later than analysts predict.
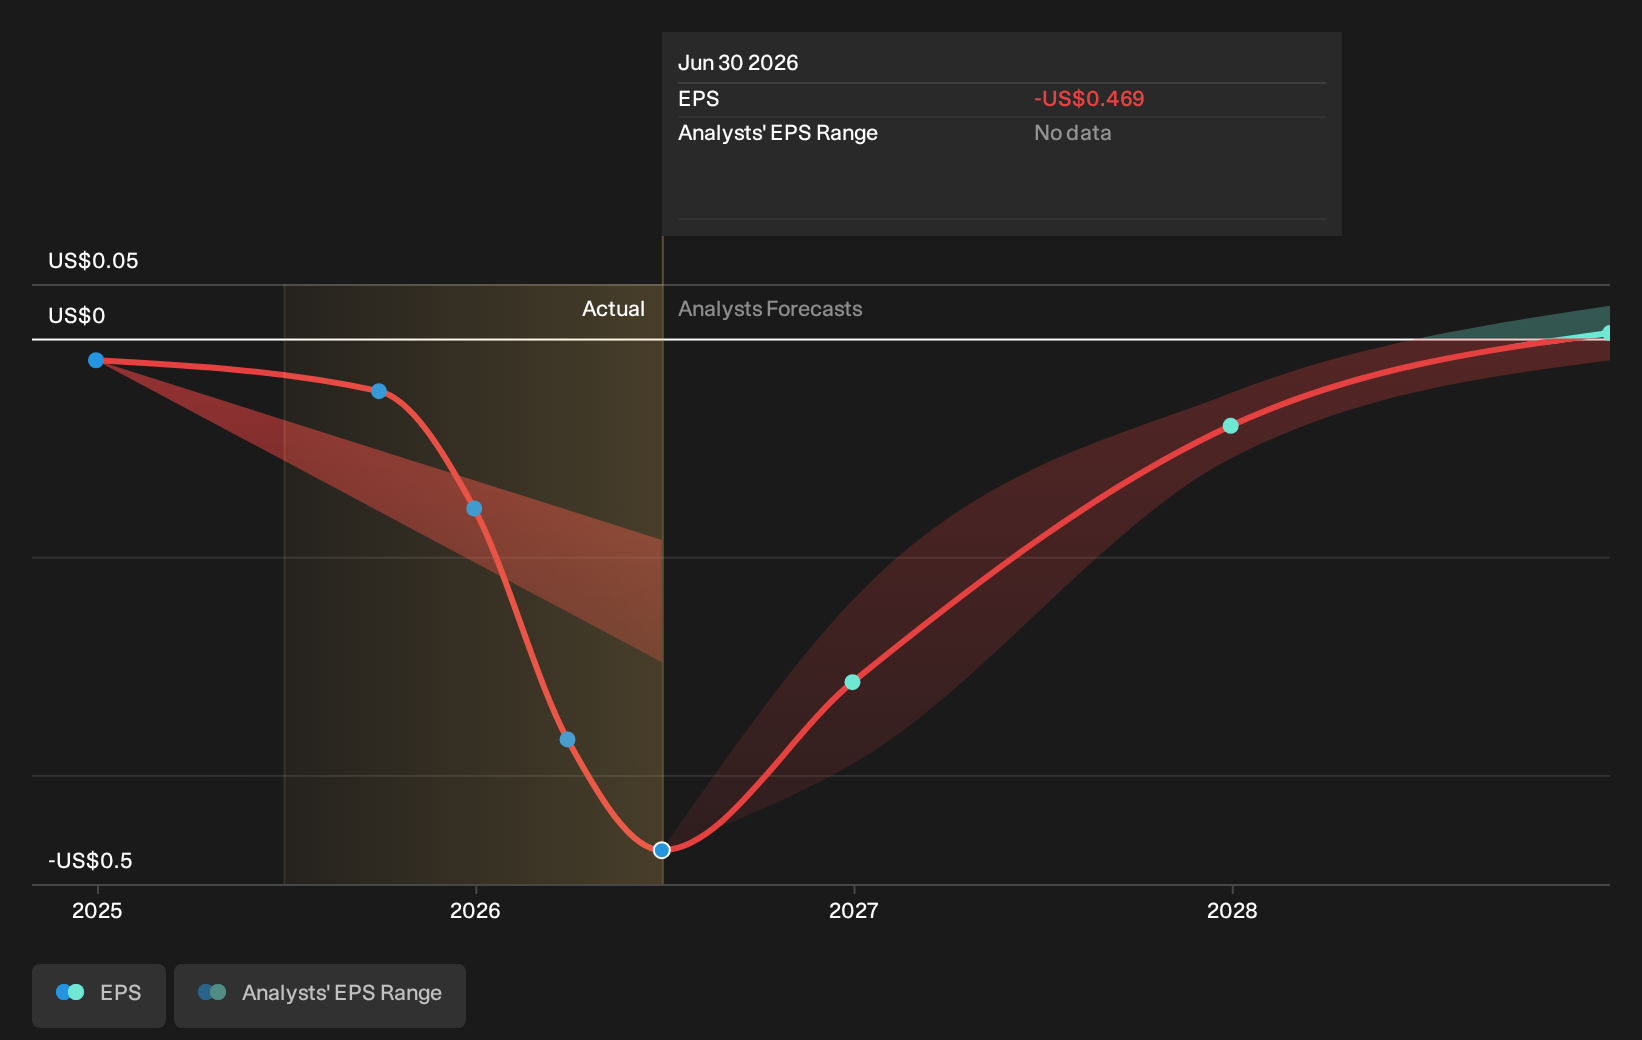
Underlying developments driving Metals Royalty's growth isn’t the focus of this broad overview, however, keep in mind that by and large a metal and mining business has lumpy cash flows which are contingent on the natural resource mined and stage at which the company is operating. This means, large upcoming growth rates are not abnormal as the company is beginning to reap the benefits of earlier investments.
Check out our latest analysis for Metals Royalty
Before we wrap up, there’s one aspect worth mentioning. The company has managed its capital judiciously, with debt making up 35% of equity. This means that it has predominantly funded its operations from equity capital, and its low debt obligation reduces the risk around investing in the loss-making company.
Next Steps:
This article is not intended to be a comprehensive analysis on Metals Royalty, so if you are interested in understanding the company at a deeper level, take a look at Metals Royalty's company page on Simply Wall St. We've also put together a list of key factors you should look at:
- Valuation: What is Metals Royalty worth today? Has the future growth potential already been factored into the price? The intrinsic value infographic in our free research report helps visualize whether Metals Royalty is currently mispriced by the market.
- Management Team: An experienced management team on the helm increases our confidence in the business – take a look at who sits on Metals Royalty’s board and the CEO’s background.
- Other High-Performing Stocks: Are there other stocks that provide better prospects with proven track records? Explore our free list of these great stocks here.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.