
Seagate Stock Has Already Exploded. Here’s What Could Send It 99% Higher to $1,600.
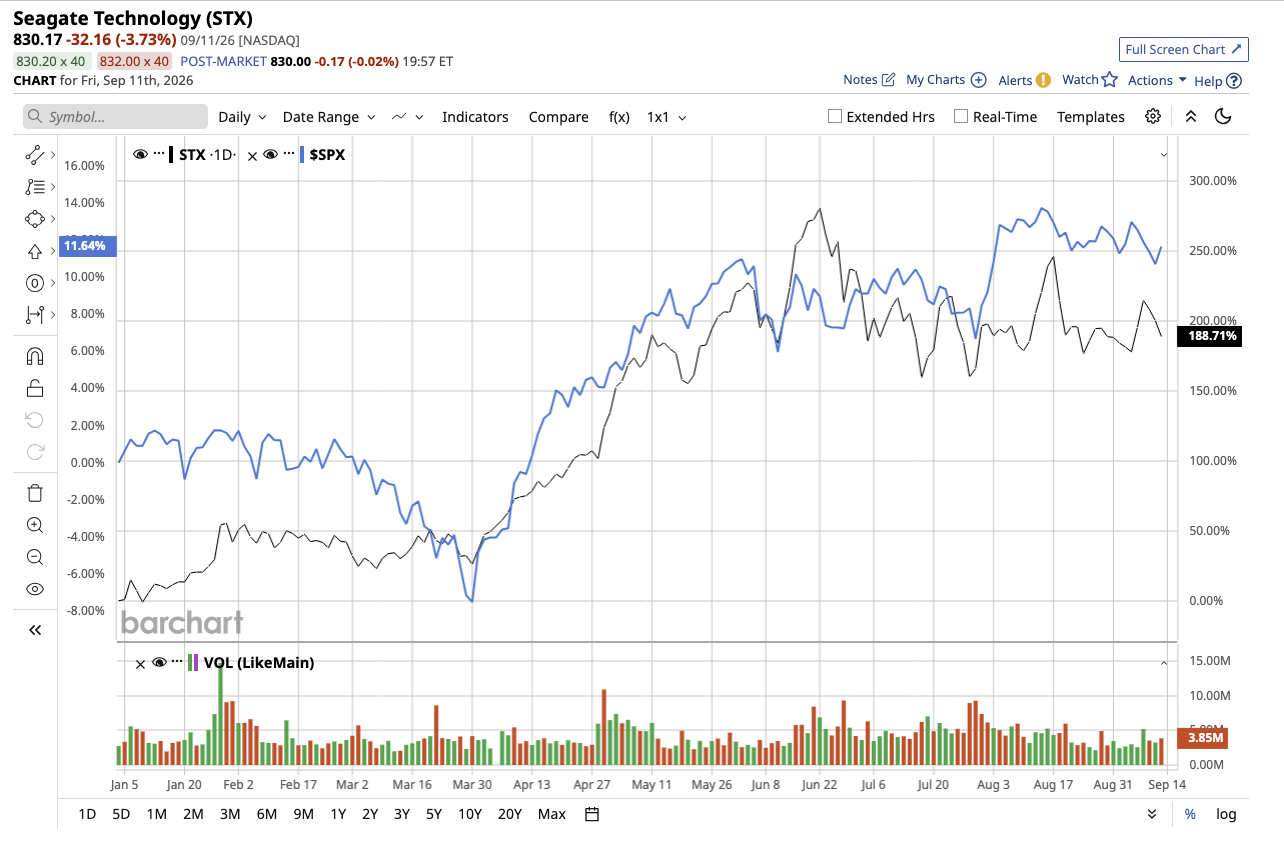
Seagate Technology (STX) stock has exploded this year, climbing 174% and outperforming the broader market by a wide margin. But now the question is: what happens next if the company turns the AI data boom into something bigger than a temporary storage cycle? Wall Street believes the stock can soar to $1,600. Let’s find out what catalysts could propel the stock to that target.
A Strong End to Fiscal 2026 Convinced Investors to Jump Into the Stock
Seagate ended fiscal 2026 with numbers that were hard to overlook. Revenue increased 34% from the year earlier to $12.2 billion, beating the consensus estimate by $137.7 million. Adjusted earnings per share (EPS) rose a staggering 92.3% to $15.58. In the June quarter alone, revenue jumped 48% year-over-year (YOY) to $3.6 billion, while adjusted EPS more than doubled to $5.71. Adjusted gross margin reached 52.7%, while operating margin climbed to 44.6%. The company entered fiscal 2027 with a much more profitable financial model than it had a year ago.
The obvious AI winners have been companies selling processors and data center infrastructure. But Seagate argues that the next winners will be the ones storing everything AI creates. Storage demand will potentially become crucial rather than purely cyclical. And Seagate believes that hard drives can serve as a low-cost storage layer behind faster memory and SSDs, allowing AI systems to keep more data without relying solely on expensive computational resources.
Then there is the HAMR opportunity. Seagate’s new technology allows it to put substantially more data onto each disk. This will allow the company to increase the amount of storage it ships without needing to increase the number of physical drives created. Management expects this to contribute to a mid-20% increase in nearline exabytes over the next few years as HAMR adoption grows. “Nearline” storage refers to a data storage tier that bridges the gap between fast, expensive online storage and slow, cheap offline backup.
HAMR-based drives had reached roughly 40% of Seagate’s nearline exabyte shipment volume by the end of fiscal 2026. Mozaic 3 products have been qualified by key cloud customers, and Mozaic 4 is currently ramping up with the two largest global cloud service providers. Mozaic 4 can accommodate drives up to 44 terabytes, and Seagate expects that platform to account for half of its HAMR exabytes by the end of calendar 2026.
Another Reason Wall Street Believes Seagate’s Boom Could Last
There is another reason why analysts believe the current boom could last. Seagate’s business is now heavily concentrated in data centers, which generate about 90% of its exabyte shipments. The company also has unusually strong visibility into future demand, with most of its nearline capacity already committed through 2028 under long-term agreements. Some customers are even looking further ahead, with discussions now extending into 2029 and later.
Basically, if customers commit capacity well ahead of production, Seagate can plan manufacturing around it rather than waiting for demand to arrive. A company with committed demand, rising prices, and increasing capacity per drive has more ways to expand profit. This gives investors visibility into the future, assuring them that this wasn’t just a typical storage upcycle.
Furthermore, Seagate pointed to robotics and autonomous vehicles as potential sources of another surge in data creation because these systems rely on huge quantities of historical and synthetic video to build models of the physical world. While the effect of this won’t be seen in the next quarter, it strengthens Seagate’s long-term case.
The balance sheet is another reason for Wall Street to be bullish. Seagate ended fiscal 2026 with $1.7 billion of cash and about $3.6 billion of gross debt, down $1.4 billion from a year earlier. The company also generated free cash flow of $3.1 billion. Management said it planned to retire another $1.2 billion of debt in the September quarter, including the remaining balance on its convertible notes. A stronger balance sheet gives Seagate more flexibility to reinvest in its business while also leaving room for shareholder returns.
What Could Turn Seagate’s $1,600 Target From a Stretch Into Reality?
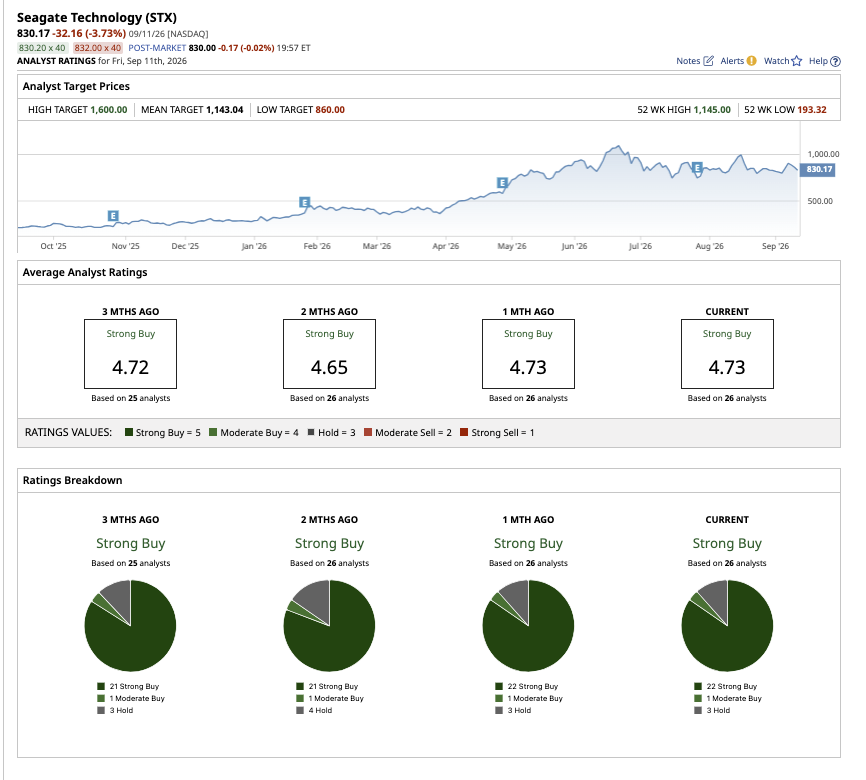
Melius Research initiated coverage of Seagate stock with a “Buy” rating and a high price target of $1,600, which implies roughly 99% upside from current levels. Essentially, these few catalysts could help the company reach this target price. First, AI-driven data creation and retention would need to remain structurally strong. Second, Seagate would need to keep moving customers toward higher-capacity HAMR products without losing its pricing power. Third, exabyte growth would have to remain in the mid-20% range that management is targeting. And finally, the company would need to keep converting that growth into expanding margins and enormous free cash flow.
For Seagate to be able to hit this target, it needs to convince investors that its AI-driven storage opportunity is translating into sustained earnings growth, not just higher revenue. The company enters fiscal 2027 with considerable demand visibility, with management expecting revenue growth to surpass the 34% rate shown in fiscal 2026. HAMR will be central to that story.
Analysts, on the other hand, expect much higher growth. Revenue is expected to increase 54%, followed by an earnings increase of 129.6%. In fiscal 2028, revenue and earnings are expected to increase further by 33.6% and 54.7%, respectively. Trading at 23x forward earnings, Seagate is still a reasonable buy. If AI keeps driving data creation and retention and Seagate continues executing as planned, $1,600 is not a far-fetched target.
Overall, the consensus on Seagate stock is a “Strong Buy” from 22 out of 26 analysts covering the stock. Meanwhile, one rates it a “Moderate Buy,” while three say it is a “Hold.” The average target price for the stock stands at $1,143.04, which is 37.7% above current levels.
On the date of publication, Sushree Mohanty did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.