
Repsol (BME:REP) Could Be 40% Undervalued As Valuation Views Split
Repsol (BME:REP) has drawn fresh attention after its recent share price move, with the stock closing at €29.38. That shift puts the current performance and the wider multi-energy business mix back in focus for investors.
For context, Repsol’s recent 1-month share price return of 9.67% and 90-day gain of 34.65% point to building momentum. The 79.04% year-to-date share price return and 107.03% 1-year total shareholder return indicate that this latest move extends a much stronger run rather than breaking a quiet stretch.
Scan beyond Repsol’s sharp run and line up other potential momentum trades with the hand picked 195 high quality undervalued stocks that may be priced below their underlying fundamentals.
Repsol’s surge has already rewarded holders in a big way, yet the share price still screens at a sizeable intrinsic discount. Is most of the upside already in the rear-view mirror, or does the valuation still leave room on the table?
Most Popular Narrative: 6% Overvalued
The most followed narrative puts Repsol’s fair value at €27.63, which sits below the last close of €29.38. That gap frames the current rally as slightly ahead of the underlying valuation work rather than lagging it.
Repsol's continued expansion and asset rotations in renewable energy (notably wind, solar, and renewable fuels) are poised to diversify revenue streams, lessen earnings volatility, and capture higher-margin growth in low-carbon markets; this is strengthened by increasing policy support for renewables and rising demand in both the U.S. and Spain, directly impacting future revenue and net margins.
See why 76 investors see Repsol as 6% overvalued.
The fair value estimate is built using a 7.4% discount rate and assumes revenue growth of about 2.35% a year in euro terms with future net profit margins near 5.65%. That framework also applies a future P/E of roughly 9.15x on those earnings, which is slightly lower than the previous multiple used in this narrative.
Analysts feeding into this view are effectively saying the current price already reflects much of Repsol’s multi-energy repositioning, while still assigning value to the renewable and low carbon projects described in the narrative. The modest revision of fair value from €27.08 to €27.63, alongside a share price above both levels, points to limited implied upside within this specific model at today’s quote.
Result: Fair Value of €27.63 (OVERVALUED)
Still, any acceleration in carbon pricing or a slower shift into renewables than analysts expect could pressure Repsol’s cash generation and challenge this valuation story.
Find out about the key risks to this Repsol narrative.
Another View On Repsol’s Valuation
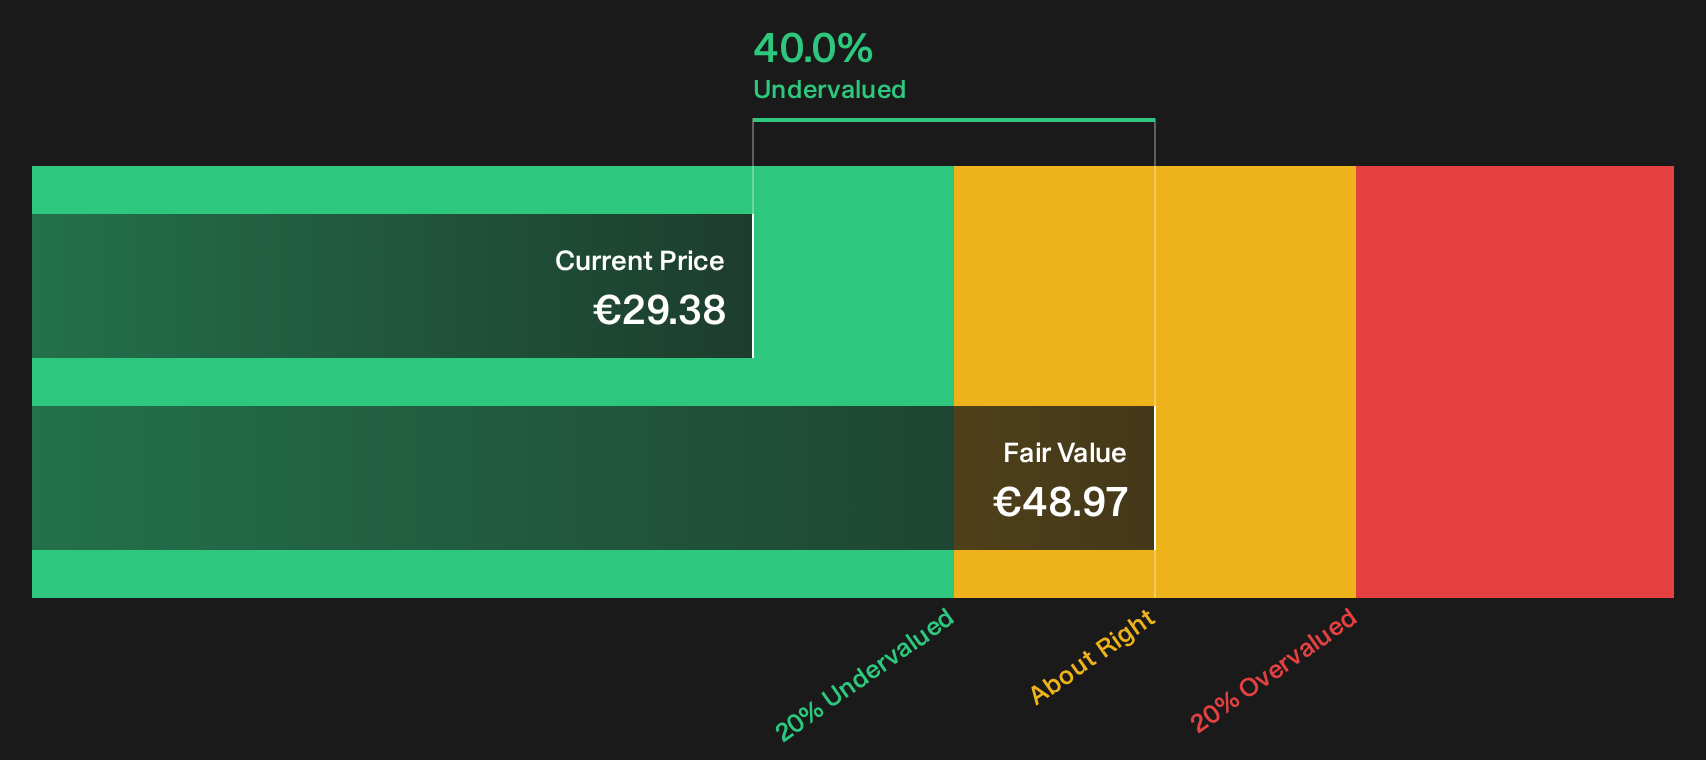
Against the analyst fair value of €27.63, the SWS DCF model paints a very different picture. On that framework, Repsol at €29.38 trades well below an estimated future cash flow value of €48.97, which suggests the company’s cash generation profile may not be fully reflected in today’s price.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment around Repsol is split between optimism and caution. Move quickly, review the numbers yourself, and weigh both sides of the story with the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Repsol?
If you stop at Repsol, you only see one part of the opportunity set. Broaden your watchlist with focused screeners that surface very different types of potential ideas.
- Hunt for higher income potential by scanning a curated set of strong yield opportunities with the 160 dividend fortresses.
- Prioritise resilience in tougher markets and zero in on companies that pair durable balance sheets with steady fundamentals using the list of solid balance sheet and fundamentals (195 results).
- Spot future leaders early and comb through under-the-radar businesses with solid metrics via the 621 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com