
3 U.S. Oil And Gas Stocks With The Most Direct Exposure To Higher Crude Prices
Interest rate odds near 94%, inflation running at 3.4%, and crude around $108 have pushed energy back into the spotlight as higher fuel costs ripple through everything from household budgets to corporate balance sheets. Some large U.S. oil and gas producers may feel that pressure. Others could see stronger cash flow. This article walks through three stocks from our screener that appear especially exposed to these crosscurrents right now.
The three stocks below are a sample pulled from a much wider field, and the full screen surfaced 10 more large U.S. oil and gas businesses with equally compelling narratives that are not covered here. To identify and analyze potential high-conviction ideas that fit this theme directly, head straight into the U.S. Large-Cap Oil & Gas Producers and Integrated Energy Stocks screener.
Weatherford International (WFRD)
Weatherford International plugs into this large cap energy screen as a global oilfield services player that gives you indirect exposure to higher oil prices through drilling and production activity rather than owning the barrels itself.
Weatherford International, a Houston based oilfield services group, supports drilling, completion and production across the well life cycle. Revenue is spread across Drilling and Evaluation at about US$1.3b, Well Construction and Completions at roughly US$1.9b, Production and Intervention at around US$1.3b, plus US$335 million from other lines, and a market value near US$6.1b.
"Weatherford's expanding portfolio of advanced technologies (e.g., managed pressure drilling, TITAN RS for well abandonment, CO2 storage project contracts) is positioning the company to benefit as oilfield operations become more complex and customers seek solutions for challenging reservoirs, supporting future revenue and margin expansion as global energy producers prioritize efficiency."
Weatherford International’s appeal within this theme ultimately hinges on how one unseen pressure shapes the balance between higher activity and pricing power.
That hidden pressure point is exactly what the full narrative for Weatherford International unpacks, showing where Weatherford International’s story could be accelerating and where risks might be quietly building.

Archrock (AROC)
Archrock slots into this large cap energy screen as a Houston based natural gas compression specialist, giving you exposure to higher U.S. oil and gas activity through the infrastructure that keeps molecules moving rather than through direct commodity production.
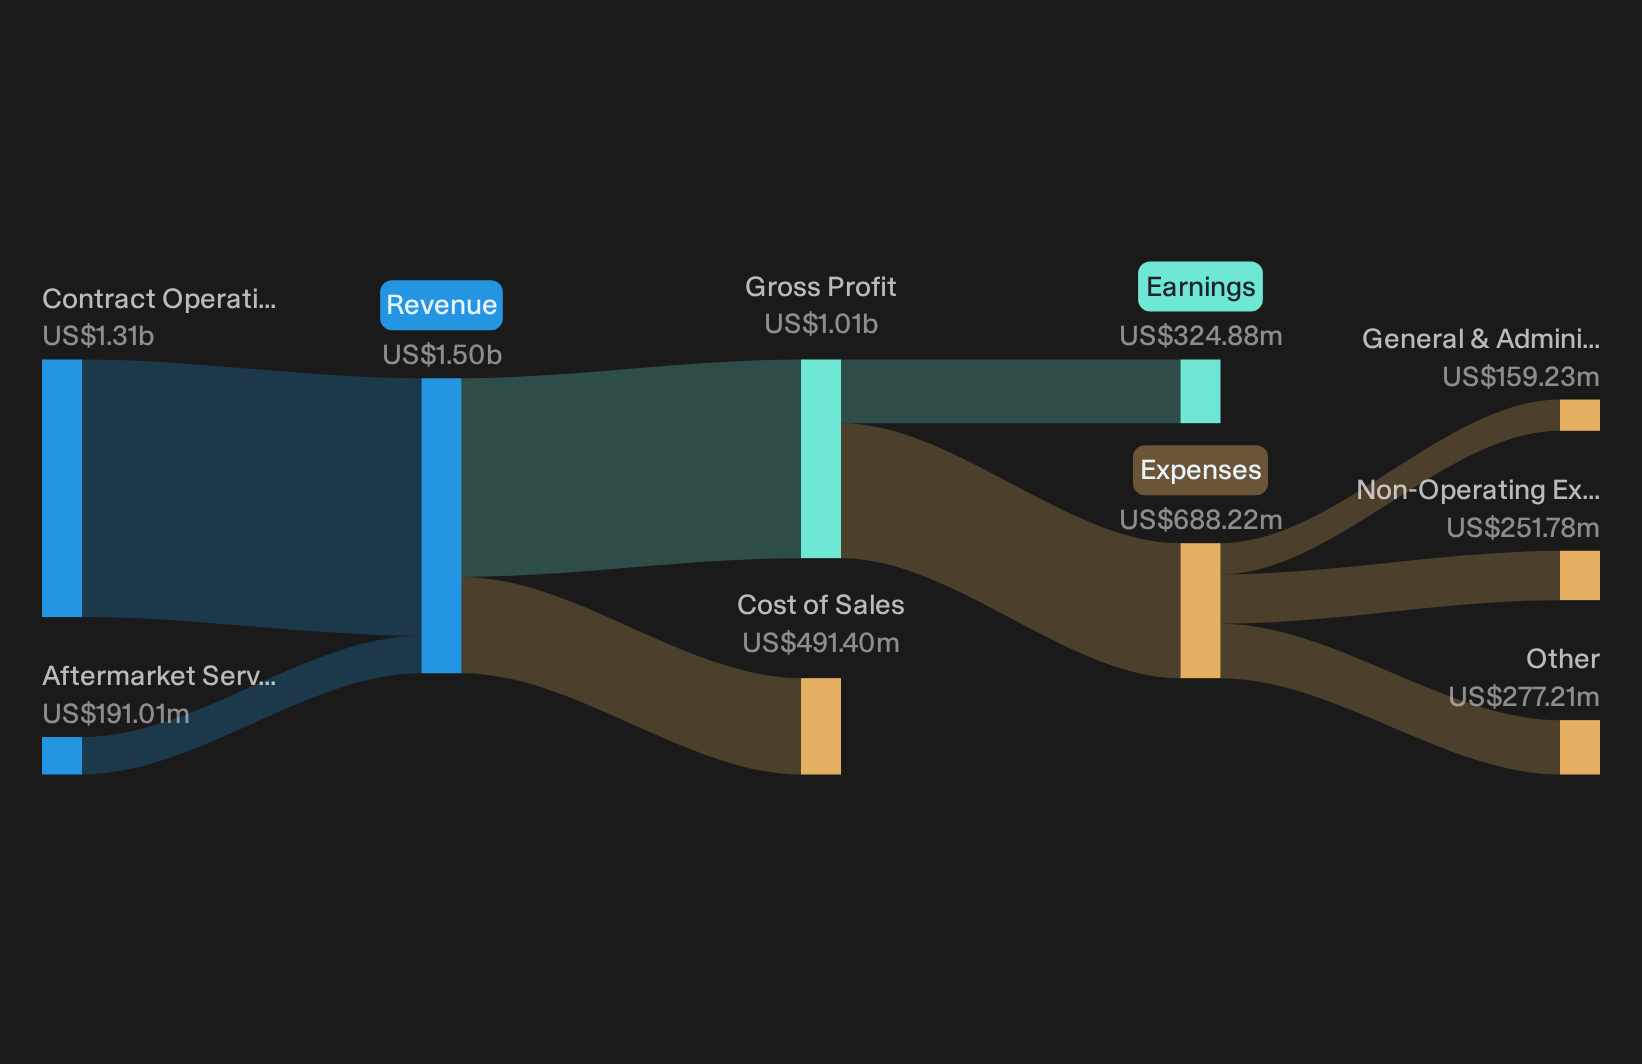
Archrock runs a U.S. focused energy infrastructure business built around natural gas compression services, with Contract Operations generating about US$1.3b and Aftermarket Services around US$191 million in revenue, and the stock valued near US$5.3b.
"Caterpillar G3600 series gas engines ... lead time for a new Caterpillar G3600 engine from order to delivery has reached 195 to 200 weeks (approximately 4 years). This extreme supply delay creates an insurmountable 'entry barrier' for competitors seeking to enter the market or for smaller companies looking for aggressive growth."
For investors tracking Archrock, what happens to one underlying driver of pricing and contract renewals could end up mattering far more than headline volume trends.
That pressure point is exactly what the full narrative for Archrock lays out in detail, showing where Archrock’s pricing power could be accelerating and where contract risk might be quietly building.
SM Energy (SM)
SM Energy plugs directly into this large cap U.S. oil and gas theme as a pure exploration and production player, giving you straightforward exposure to crude and natural gas liquids pricing rather than refining margins or complex integrated models.
SM Energy Company is an independent producer focused on acquiring, drilling and operating oil, gas and NGL wells across the Midland Basin, South Texas, Uinta Basin and DJ Basin, generating about US$4.96b from exploration and production in the United States and carrying a market value near US$9.3b.
In a world of higher fuel prices, SM Energy is a relatively direct expression of the screener’s idea, where cash from wellhead production can potentially fund dividends and buybacks if oil prices remain supportive.
"Prudent balance sheet management with leverage near 1x, combined with a clear commitment to opportunistic share buybacks and capital discipline, informs the outlook for EPS and shareholder returns."
What happens to one critical cost pressure in SM Energy’s key shale basins could end up influencing how much of that potential ultimately reaches investors.
Those cost swings are exactly where the full narrative for SM Energy drills in, mapping how SM Energy’s capital choices could turn that pressure into accelerating or stalled shareholder payouts.

Seeking Fresh Alternatives With Real Edge
Fresh ideas move first. Screens fill with new breakouts, fading momentum and under the radar stories that can be caught early, before the crowd, while it matters. Act now.
- Zero in on potential breakout compounders by scanning a curated set of 34 high quality undervalued stocks that could reward patient capital once the rest of the market finally catches up.
- Chase early-cycle upside in critical materials by reviewing a focused group of 29 top copper producer stocks tied to long term electrification and infrastructure build outs.
- Hunt for durable income streams by sifting through a hand picked pool of 6 dividend fortresses that aim to keep yields flowing even when sentiment drops.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com