
PBF Energy (PBF) Stock Could Trade At A Discount To Earnings
PBF Energy has delivered a very strong run over the past few years, and the share price strength now puts a spotlight on what investors are paying for its earnings. With the stock trading around US$74.72 after a sharp climb, the question is how that performance lines up with what the business is currently generating in profit.
- The stock has returned roughly 7x over 5 years, which raises the issue of how much of that move can be traced back to sustainable earnings power rather than sentiment.
- Recent reports of record profitability, lower net debt and refinanced obligations may support a view that earnings quality and balance sheet flexibility could be stronger than in the past.
- Your read on PBF Energy is one view; the desks covering it have another. See what analysts think PBF Energy's shares could be worth.
The issue now is whether PBF Energy's current share price is appropriately aligned with its earnings when viewed through this lens.
To evaluate whether PBF Energy's recent performance is unique or part of a broader earnings-driven trend, compare it against solid balance sheet and fundamentals stocks screener (22 results).
Does PBF Energy Look Undervalued on Earnings?
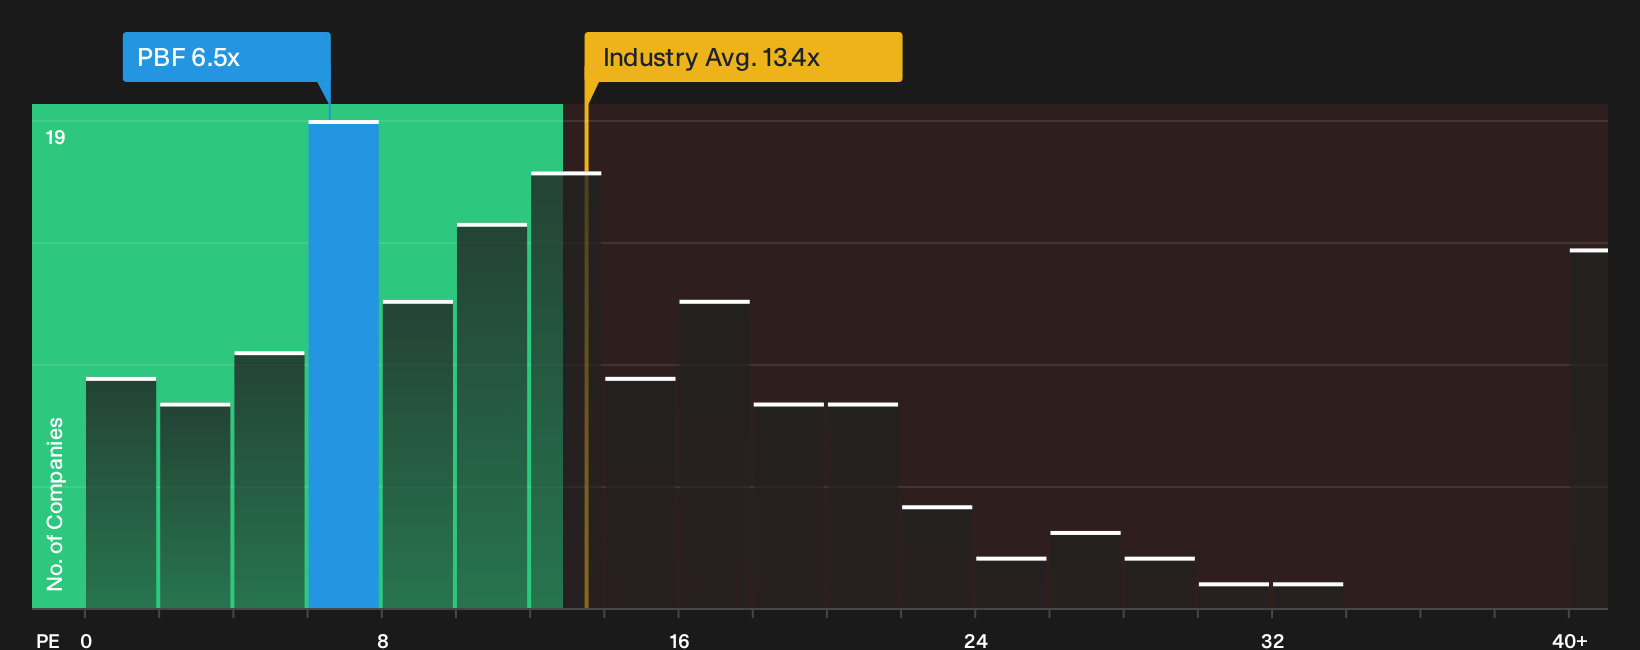
The P/E ratio fits PBF Energy well because recent headlines and investor attention have all focused on earnings power. On that yardstick, the stock trades on roughly 6.5x earnings, which is well below the Oil and Gas industry average of about 13.4x and far under a broader peer group near 31.3x. Compared with what a tailored model suggests as a more fitting multiple for a business with PBF Energy’s profile, the current figure sits on the cheaper side and implies that the market is attaching a relatively low price tag to each dollar of profit.
Because record profitability in 2024 has pushed the share price to new highs, yet the P/E has stayed this far under those benchmarks, the recent surge in PBF Energy still leaves the stock screening at a discount on earnings. That gap invites investors to weigh whether today’s profits and balance sheet improvements can justify a higher earnings multiple over time or whether the low P/E already bakes in the sector’s usual risks. Explore the numbers behind PBF Energy's P/E valuation.
The PBF Energy Narrative: What Would Justify Today's Price?
For PBF Energy, Simply Wall St Narratives pick up where this valuation puzzle leaves off. They spell out the specific growth, margin and earnings paths that would need to hold for the stock to be worth meaningfully more or less than today’s price. Each one treats its fair value as a thesis about PBF Energy's business that you can revisit over time rather than a one-off snapshot, all housed on the Community page.
Community views on PBF Energy are split around how durable today’s refining setup and cost savings really are.
Bull case: 11% undervalued
"PBF is uniquely positioned to benefit from sustained global demand growth and inadequate capacity additions, as capacity rationalizations and refinery closures accelerate in both North America and Europe…"
Discover why this Narrative puts PBF Energy at 11% undervalued.
Bear case: 11% overvalued
"Persistent operational and regulatory risks at key refineries, especially Martinez, expose PBF to ongoing revenue volatility and higher repair and maintenance capex…"
Explore why this Narrative puts PBF Energy at 11% overvalued.
One more PBF Energy check before you move on
Price ratios and balance sheet trends only tell you where PBF Energy stands today. The next layer is how professional analysts currently see the profit picture a few years from now. Explore where analysts expect PBF Energy to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com