
Is Rollins Stock Underperforming the Dow?
Rollins, Inc. (ROL) is a global pest control services company based in Atlanta, Georgia, operating through more than 60 brands, including Orkin, Critter Control and Saela. It provides residential and commercial pest and wildlife control, termite protection, and related services across approximately 70 countries. The company has a market capitalization of approximately $17 billion.
Companies worth between $10 billion and $200 billion are generally classified as “large-cap stocks,” and Rollins comfortably fits this category. Its substantial market capitalization reflects its size, influence and established position within the personal services industry. Rollins stands out through its powerful Orkin brand and proprietary technologies that make pest control services more efficient. Its strong market position, customer loyalty, diverse brand portfolio, and expanding international presence provide a solid foundation, while investments in employee training and development could further support long-term growth.
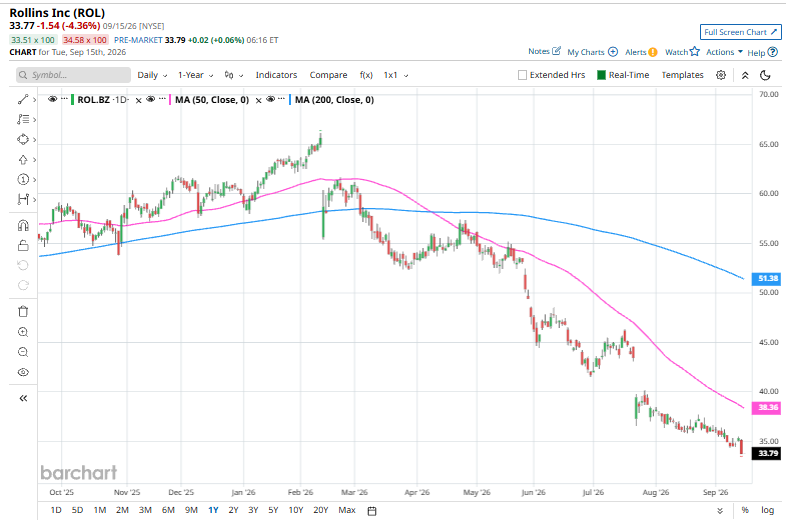
Despite these notable strengths, ROL has slipped 48.9% from its 52-week high of $66.14, reached on February 11, 2026. Over the past three months, ROL shares have dipped 28%, underperforming the Dow Jones Industrial Average ($DOWI), which has gained marginally over the same period.
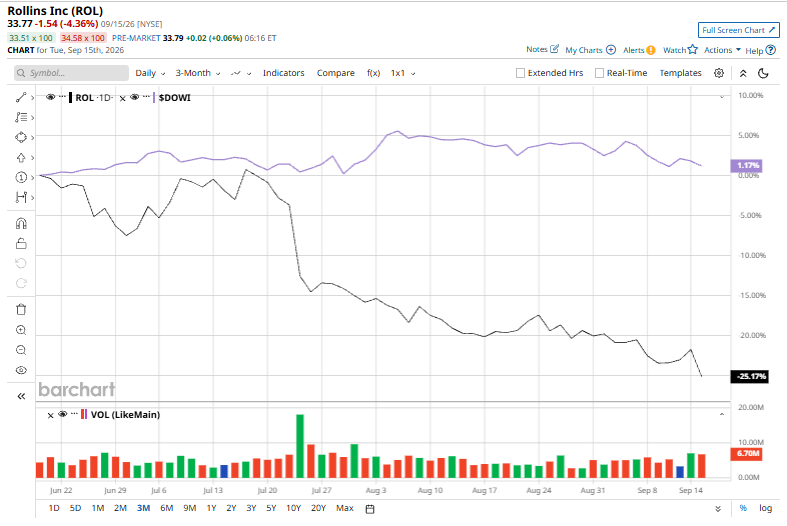
Shares of ROL have dipped 43.7% year-to-date and 40.2% over the past 52 weeks, trailing the Dow’s 8.4% year-to-date gain and 13.5% return over the past year.
Shares of ROL have been trading below their 200-day moving average since early March and below their 50-day moving average since late April, suggesting a sustained downtrend.
Rollins’ underperformance may partly reflect slower organic growth in its core business and weaker recent quarterly results. Organic revenue grew 7% year over year on average over the past two years, slightly lagging the sector, which could indicate moderating underlying demand.
More recently, on July 22, the company reported disappointing second-quarter results, with adjusted EPS, revenue and adjusted EBITDA all falling short of Wall Street’s expectations. The following day, ROL shares fell 9.3% in the afternoon session. Although revenue increased 7.9% year over year, operating margin declined to 18.7% from 19.8%, while free cash flow margin fell 1.4 percentage points, which may have added to investor concerns.
In the competitive personal services industry, top rival Service Corporation International (SCI) has shown resilience, outperforming ROL year to date with a 4.1% gain and a 1.9% gain over the past 52 weeks.
Wall Street analysts remain somewhat bullish on ROL’s prospects. The stock carries a consensus “Moderate Buy” rating from the 17 analysts covering it. The mean price target of $44.93 suggests potential upside of 33% from current ROL levels.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.