
Is Investment Grade Upgrade Altering The Investment Case For Renault Stock (ENXTPA:RNO)?
- Moody's has upgraded Renault SA to an investment grade long-term credit rating of Baa3 with a stable outlook, citing in-depth transformation, a resilient business model, prudent financial management and a reinforced balance sheet.
- The investment grade rating underscores how Renault's value-focused commercial approach, dual electrification strategy and strong liquidity profile support its ability to fund operations and future projects on potentially more favorable terms.
- We will now look at how Renault's upgraded investment grade rating reshapes the investment narrative built around transformation and resilience.
Renault Investment Narrative Recap
To own Renault, you need to believe the turnaround around electrification, cost discipline and product refresh can keep translating into healthier earnings and cash generation. The Moody's upgrade supports that story by pointing to a sturdier balance sheet and funding access, which matters if you care about how the group finances Ampere, new models and ongoing restructuring.
In the short term, the key swing factor remains execution on EV and hybrid volumes without eroding margins through heavy incentives to meet 2025 regulations. The biggest risk still looks like pressure on profitability from regulatory costs and volatile markets, rather than anything fundamentally changed by the rating move.
The appointment of Jean-Pierre Diernaz as Chief Branding Officer across all brands appears closely tied to the current catalyst mix. Renault is focusing on brand realignment and product positioning to support EV adoption and pricing power. Stronger, more coherent marketing could help differentiate Renault, Dacia and Alpine in crowded segments where incentives can quickly eat into profitability.
This move can also be read alongside the futuREady plan and the Ampere ambitions. Tighter integration of brand, customer experience and commercial performance places more weight on execution in digital marketing and data use. If this leadership change accelerates that shift, it could support the EV rollout, while any missteps would amplify existing risks around margins and regulatory deadlines.
What The New Renault Rating Implies For Forecasts And Valuation
Renault's narrative projects €62.6 billion revenue and €2.0 billion earnings by 2029. This assumes 2.6% yearly revenue growth and an earnings swing of €12.9 billion from a loss of €10.9 billion today to the 2029 consensus level.
Uncover how Renault's fair value indicates a 31% potential upside to its current price before buying interest closes that gap.
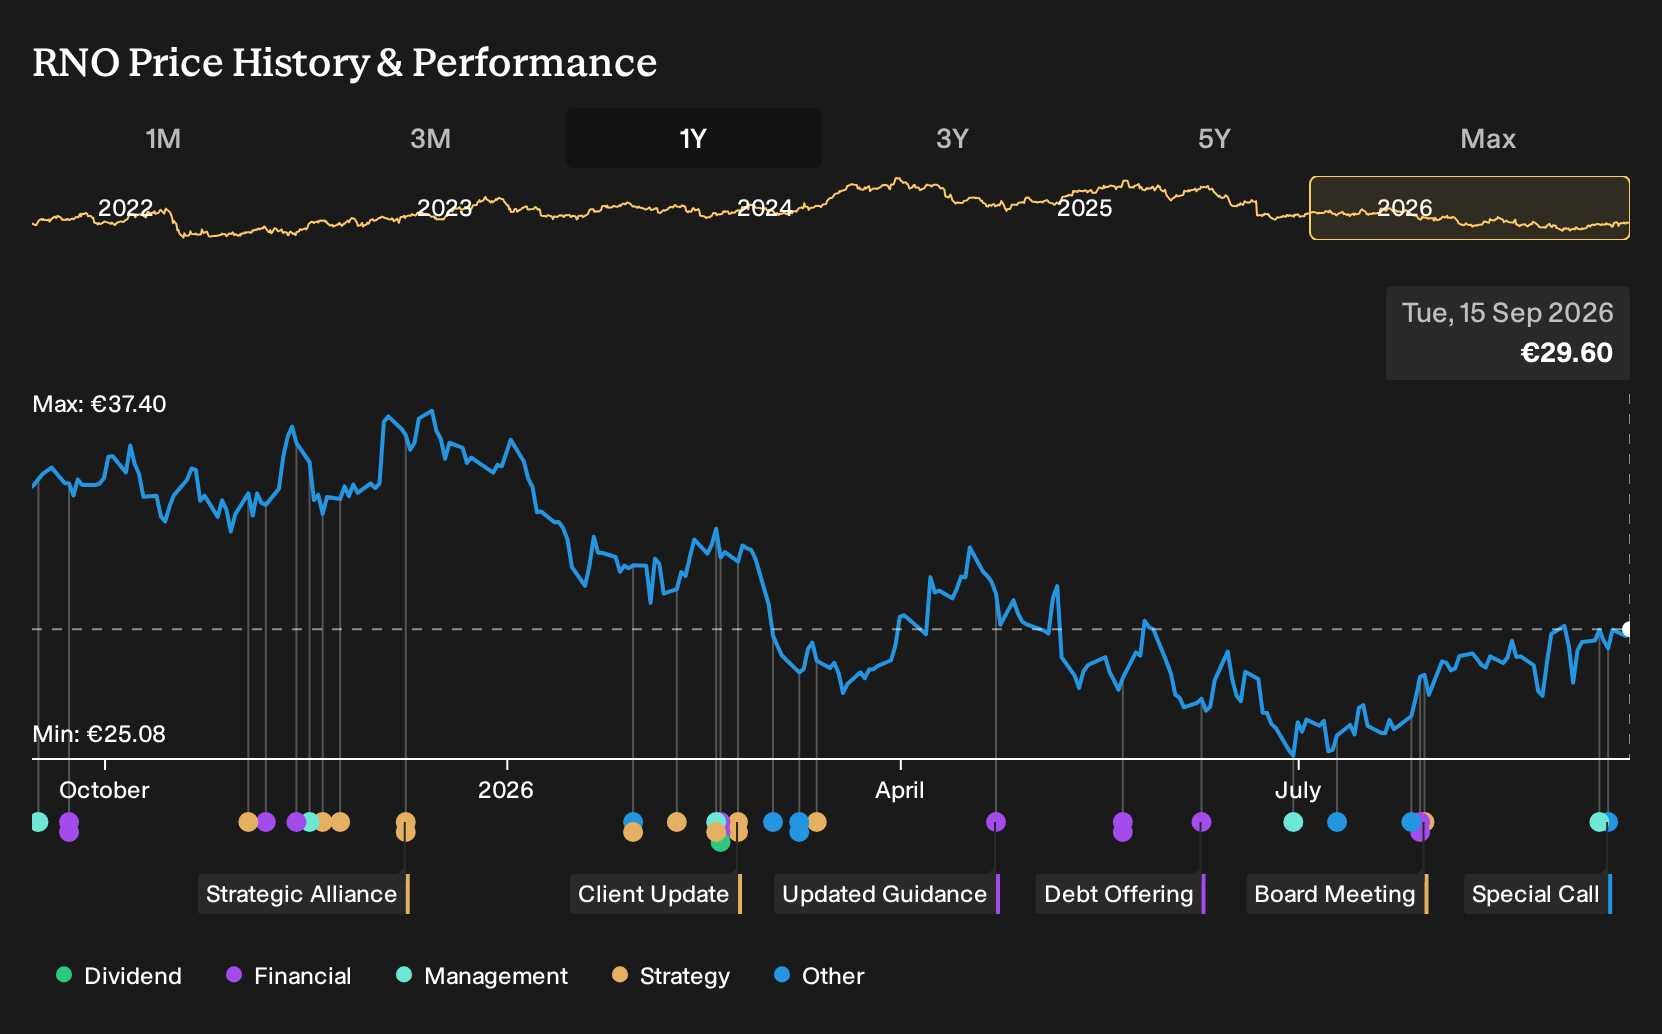
Exploring Other Perspectives
Some of the most optimistic analysts focus on Renault’s product surge as the real swing factor. Before this rating news, the bullish camp was already pencilling in revenue of about €63.9b and earnings of €5.4b by 2028. That is a far brighter story than consensus, and it might shift again as fresh information lands.
Explore 3 other Renault fair value estimates, including one that suggests as much as 96% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Renault research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Renault. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Renault's overall financial health at a glance.
Looking For More Ideas Beyond Renault?
Once you have a view on Renault, it can help to compare that thesis with other companies that share similar qualities around balance sheet strength, income potential or perceived mispricing. The Simply Wall St Screener lets you quickly filter the market using these themes so you can pressure test your thinking and spot fresh ideas that match your risk profile.
- If you want companies that appear mispriced relative to fundamentals, use the screener focused on undervalued quality and scan a curated set of 195 high quality undervalued stocks that might merit a closer look.
- For investors who care most about reliable income, filter for high-yield opportunities and review a focused group of 160 dividend fortresses that meet strict payout and stability criteria.
- Risk control can matter as much as return, so narrow your watchlist to sturdier balance sheets by screening across a list of solid balance sheet and fundamentals (195 results) that pass tough financial health filters.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com