
The Case for Selling CrowdStrike Stock
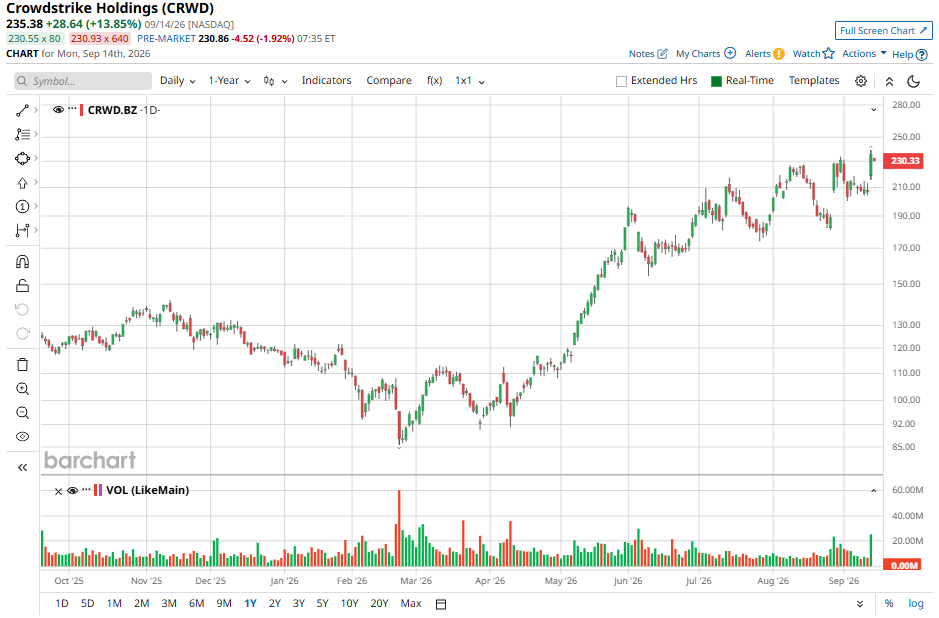
CrowdStrike (CRWD) has been one of the cybersecurity sector’s strongest performers this year. CRWD recently climbed to an all-time high of $239.37 before ending Monday’s session up roughly 10.5%. Year to date, shares have gained more than 100%.
A broader rotation within the technology sector has partly driven the rally. Comments from AI industry leaders calling for a more measured approach to frontier AI development have contributed to weakness in some high-flying AI chip stocks. At the same time, investors have turned toward cybersecurity companies that could benefit from the risks created by rapid AI adoption.
That shift makes sense. As AI models, autonomous agents, and AI-powered applications grow, they create more opportunities for cyberattacks. More AI systems mean more data, identities, permissions, and connections that need to be protected. As a result, cybersecurity is increasingly becoming an essential component of the AI infrastructure stack.
CrowdStrike is well positioned to benefit from that trend. While the opportunity remains big for CrowdStrike, that does not necessarily make a stock a good buy at any price.
AI Could Become a Major Growth Driver
The rapid adoption of AI agents is creating a new security challenge for enterprises. CrowdStrike is positioning itself to capitalize on this emerging opportunity.
At its Fal.Con conference, the company introduced two AI-focused products designed to protect AI agents operating within enterprise environments. The strategy reflects CrowdStrike’s belief that securing AI systems could become an important source of future growth.
The opportunity is potentially enormous. CrowdStrike estimates the broader AI security opportunity could reach $215 billion by 2034. That provides a significant potential runway.
CrowdStrike's Fundamentals Remain Strong
CrowdStrike is executing well. In its second quarter, revenue increased 26% year over year to $1.47 billion. Subscription revenue rose 27% to $1.40 billion, while professional-services revenue reached a record $71 million.
One of the most encouraging metrics was net new annual recurring revenue (ARR). The company generated a record $333 million of net new ARR, representing a 51% year-over-year increase.
Ending ARR climbed more than 25% to $5.84 billion, with the growth rate accelerating for the fourth consecutive quarter.
The Falcon Platform Is Increasing Customer Spending
CrowdStrike’s platform strategy positions it well for continued growth. As enterprises consolidate cybersecurity spending with fewer vendors, Falcon benefits by offering multiple security capabilities through one integrated ecosystem.
Customer adoption supports this strategy. Notably, 51% of subscription customers used six or more Falcon modules, 35% used seven or more, and 26% used at least eight. Falcon Flex is also driving higher spending, with customers switching from standard subscriptions generating an average ARR increase of more than 40% during the quarter.
Expanding revenue within the existing customer base increases average revenue per customer, lowers customer acquisition cost, and drives retention.
Management Continues to Raise Expectations
CrowdStrike's strong performance has prompted management to lift its outlook. The company raised its fiscal 2027 net new ARR forecast to approximately $1.36 billion at the midpoint. That is around $116 million above its original outlook and implies approximately 34% year-over-year growth, compared with the initial expectation of 22.5%.
Management has also raised its longer-term outlook, targeting $10 billion in ARR by fiscal 2030 and $20 billion by fiscal 2035.
The Problem Is CrowdStrike’s Valuation
While CrowdStrike’s fundamentals remain solid, the stock is pricey. After gaining more than 100% this year and hitting a record high, the stock appears to have already priced in significant future growth.
CrowdStrike's price-to-sales ratio is around 44. That represents a substantial premium to cybersecurity competitor Palo Alto Networks (PANW), whose P/S ratio is approximately 23.6.
CrowdStrike's long-term prospects remain attractive. AI adoption should increase the complexity of enterprise cybersecurity, while growing numbers of AI agents could create new vulnerabilities and security requirements. The company's platform strategy also gives it multiple avenues for increasing revenue from existing customers. But those positives are already reflected in CRWD stock.
The Bottom Line
CrowdStrike remains one of the strongest growth stories in cybersecurity, with accelerating ARR, expanding customer adoption, and an enormous AI-security opportunity. However, the stock’s valuation suggests investors who already own it could lock in gains, even though CrowdStrike's underlying business remains fundamentally attractive.
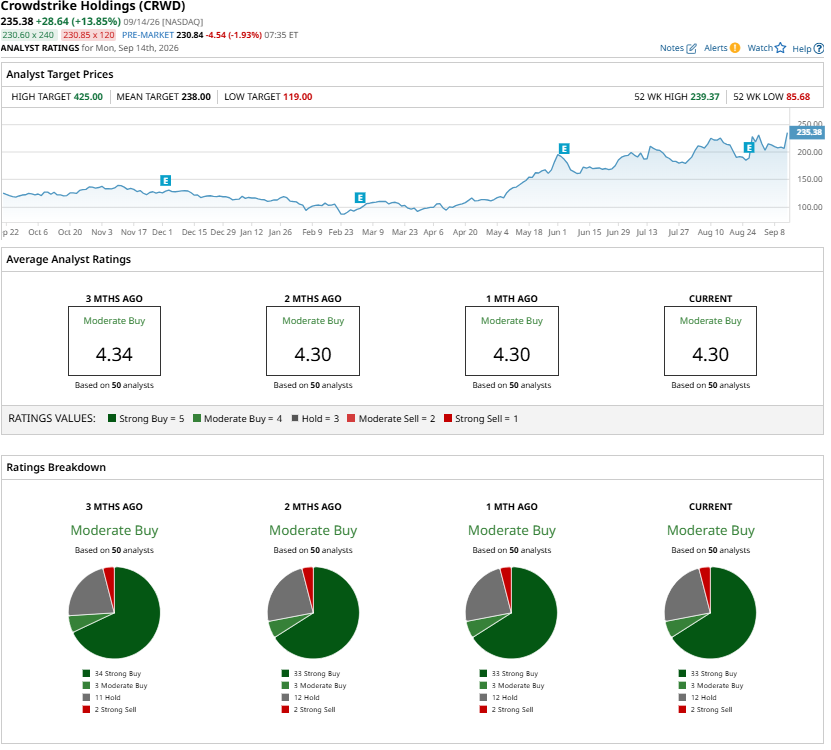
Given CrowdStrike’s elevated valuation, not all analysts remain bullish. Overall, analysts maintain a “Moderate Buy” consensus rating on CrowdStrike stock.
On the date of publication, Amit Singh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.