
Universal Health Services (UHS) Stock Looks Like A Bargain At Today’s Price
Universal Health Services has delivered a 40.2% gain over the past three years, yet its share price has fallen this year, which puts fresh focus on what investors are really paying for its earnings today. With the company also expanding its behavioral health footprint, the key issue is whether the current valuation lines up with the profits the business is generating.
- A 40.2% return over three years puts real weight on whether Universal Health Services' current valuation is still grounded in its earnings power.
- The completed US$835 million purchase of Talkspace links virtual and inpatient behavioral care, which can reshape expectations for how quickly earnings from mental health services flow through to shareholders.
- There is a second opinion on Universal Health Services worth weighing. See what analysts think Universal Health Services's shares could be worth.
For investors, the central question is whether Universal Health Services' recent share price level is fully supported by the earnings the company is producing today.
If you are comparing Universal Health Services with other options that have a similar earnings focus, a targeted screen of 34 high quality undervalued stocks can provide another starting point for more detailed research.
Is Universal Health Services a Bargain on Earnings?
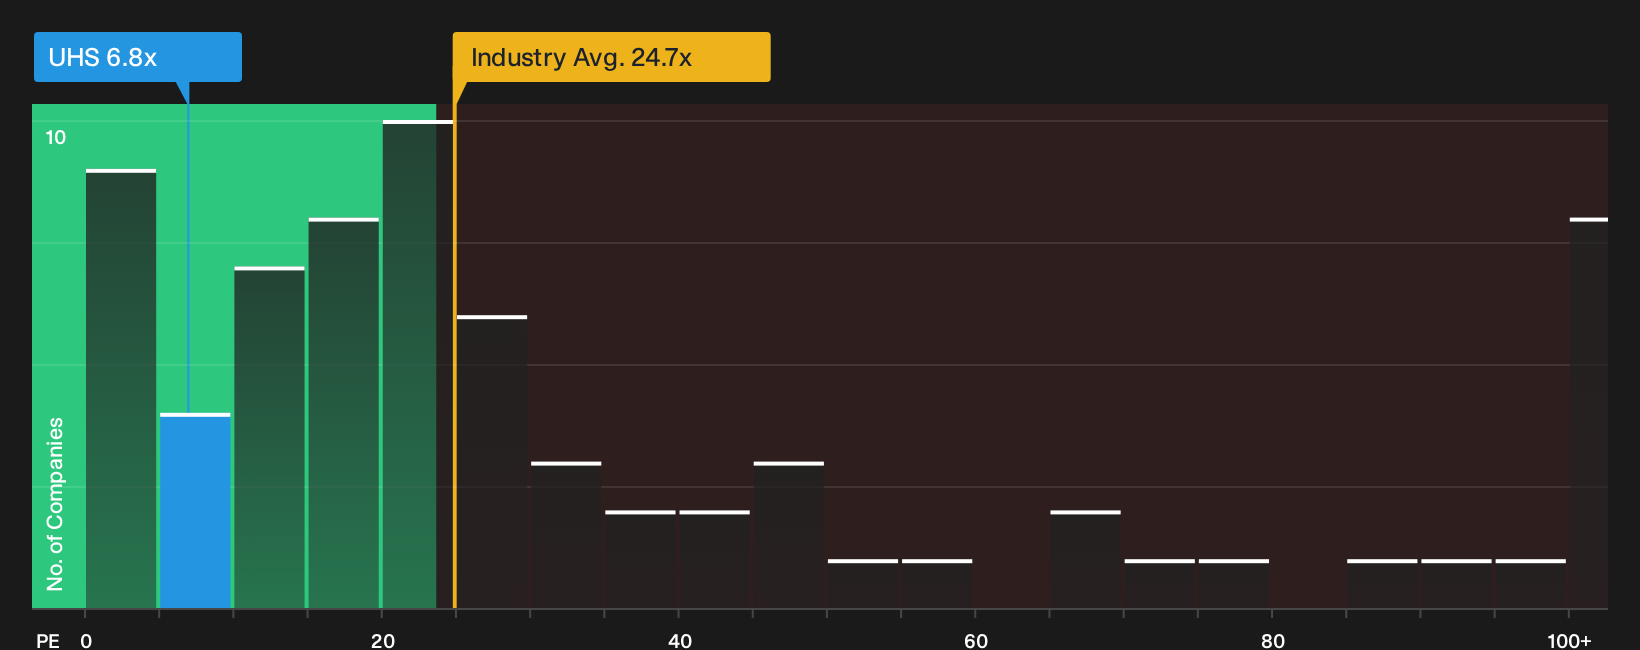
P/E fits Universal Health Services because earnings are the main anchor for how investors value large hospital and behavioral health operators. On that yardstick, the stock trades on roughly 6.8x earnings, while the broader Healthcare group sits around 24.7x and close peers average about 20.1x. Because the completed US$835 million Talkspace deal has sharpened focus on the company’s behavioral health exposure, this gap indicates that the market is still applying a steep discount even as the business leans further into mental health services.
The fair multiple that reflects Universal Health Services' profile of growth drivers, profitability, scale and risk is meaningfully above the current P/E. On this framework, the shares appear undervalued. For investors comparing options in the sector, the combination of a single digit P/E and a higher modelled fair ratio suggests that sentiment toward this company has been more cautious than those valuation inputs alone would imply. Explore the numbers behind Universal Health Services's P/E valuation.
The Universal Health Services Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Universal Health Services pick up where the valuation puzzle leaves off. They explain which expectations for future growth, profitability and earnings would need to occur for the stock to appear meaningfully cheaper or more expensive than today’s price. Each narrative links its figures to a specific view on where Universal Health Services' growth, margins and risk profile might go next, so you can revisit that stance as new information appears on the Community page.
Community views on Universal Health Services split between those who see behavioral health scale as a long-term asset and those who focus on reimbursement and cost pressure.
Bull case: 21% undervalued
“Organizations that can offer structured, evidence-based treatment at scale are becoming increasingly vital to the healthcare ecosystem…”
Discover why this Narrative puts Universal Health Services at 21% undervalued.
Bear case: 7% overvalued
“Persistent labor shortages and wage inflation, particularly among nurses and behavioral health therapists, are likely to continue outpacing reimbursement growth…”
Explore why this Narrative puts Universal Health Services at 7% overvalued.
One more Universal Health Services signal to weigh before you move on
Before you lean too hard on today’s P/E and narrative cases, it helps to see where professional forecasts expect Universal Health Services to be a few years from now, and how that compares with the current share price. Explore where analysts expect Universal Health Services to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com