
Learn Why The Bull Case For GM Stock Could Change Following Digital Revenue Growth
- General Motors is promoting its connected car and software platforms as a core business line, with management and recent commentary highlighting recurring revenue from services such as OnStar, Super Cruise and broader digital offerings, alongside updates on EV batteries and U.S. cell sourcing.
- Analysts are increasingly treating GM’s software subscriptions and digital services as a separate profit engine, focusing on digital revenue contributions that sit alongside manufacturing, cost control and factory efficiency gains from technologies like Stratasys additive manufacturing.
- This article examines how General Motors' expanding digital subscriptions, especially OnStar, could influence the broader investment narrative for the business.
Scan beyond General Motors and compare its push into software and subscriptions with other companies on our curated list of 34 high quality undervalued stocks.
General Motors Investment Narrative Recap
To own General Motors, you need to believe the shift from pure hardware to a mix of trucks, EVs and high margin software can offset pressure from tariffs, intense competition and heavy capex. The near term swing factor is execution on profitability, especially as net margins sit near 1% and warranty costs remain a drag.
The biggest operational risk is that high EV and battery investment, plus quality issues, keep cash flow tight while debt is not well covered by operating cash flow. Recent updates on digital revenue and a resilient third quarter trajectory do not fundamentally change that risk and opportunity balance in the short term.
The clearest operational link to this story is GM’s push to scale OnStar and Super Cruise into a US$3b digital revenue stream this year. UBS highlighting those services as high margin and recurring ties directly into management’s own focus on software subscriptions sitting alongside traditional manufacturing earnings.
For you, the question is whether that subscription engine can grow fast enough to offset tariff headwinds, warranty costs and heavy EV spend over the next few years. If GM executes on expanding connected services while improving quality and controlling capital intensity, the software side could become a more meaningful catalyst than any single vehicle launch.
General Motors Forecasts Behind the Software Story
General Motors' broader pitch on digital subscriptions and connected services rests on some specific analyst assumptions about where the whole business could be heading by the late 2020s. Those projections matter if you are trying to judge whether the software narrative is a side show or a material earnings swing factor.
Analysts in the consensus set expect GM's revenue to grow by 1.8% each year over the next three years, while profit margins are modeled to move from 1.0% today to 4.2% over the same period. Current earnings are quoted at US$1.9b, with forecasts pointing to US$8.2b of earnings by 2029 and earnings per share of US$9.95. That implies an earnings increase of about US$6.3b from today's base.
On those estimates, the group of covering analysts suggest that by 2029 General Motors could be generating about US$195.5b of revenue and US$8.2b of earnings. The same consensus assumes the stock would then trade on a P/E ratio of 12.7x, compared with 39.6x today and a current US auto industry P/E of 15.4x, using a discount rate of roughly 12.5% to bridge from that future year back to today.
General Motors' narrative projects US$195.5b revenue and US$8.2b earnings by 2029. This requires 1.8% yearly revenue growth and an earnings increase of about US$6.3b from US$1.9b today.
For investors weighing the software story, these earnings and revenue paths frame how much OnStar, Super Cruise and other subscription lines would need to contribute on top of trucks and EVs. If profit margins are expected to rise from 1.0% to 4.2% while EV and battery spending stays heavy, then a larger slice of that margin uplift likely has to come from recurring, higher margin services rather than just better pricing on vehicles.
Uncover why General Motors' fair value indicates a 17% potential upside to its current price before the discount closes.
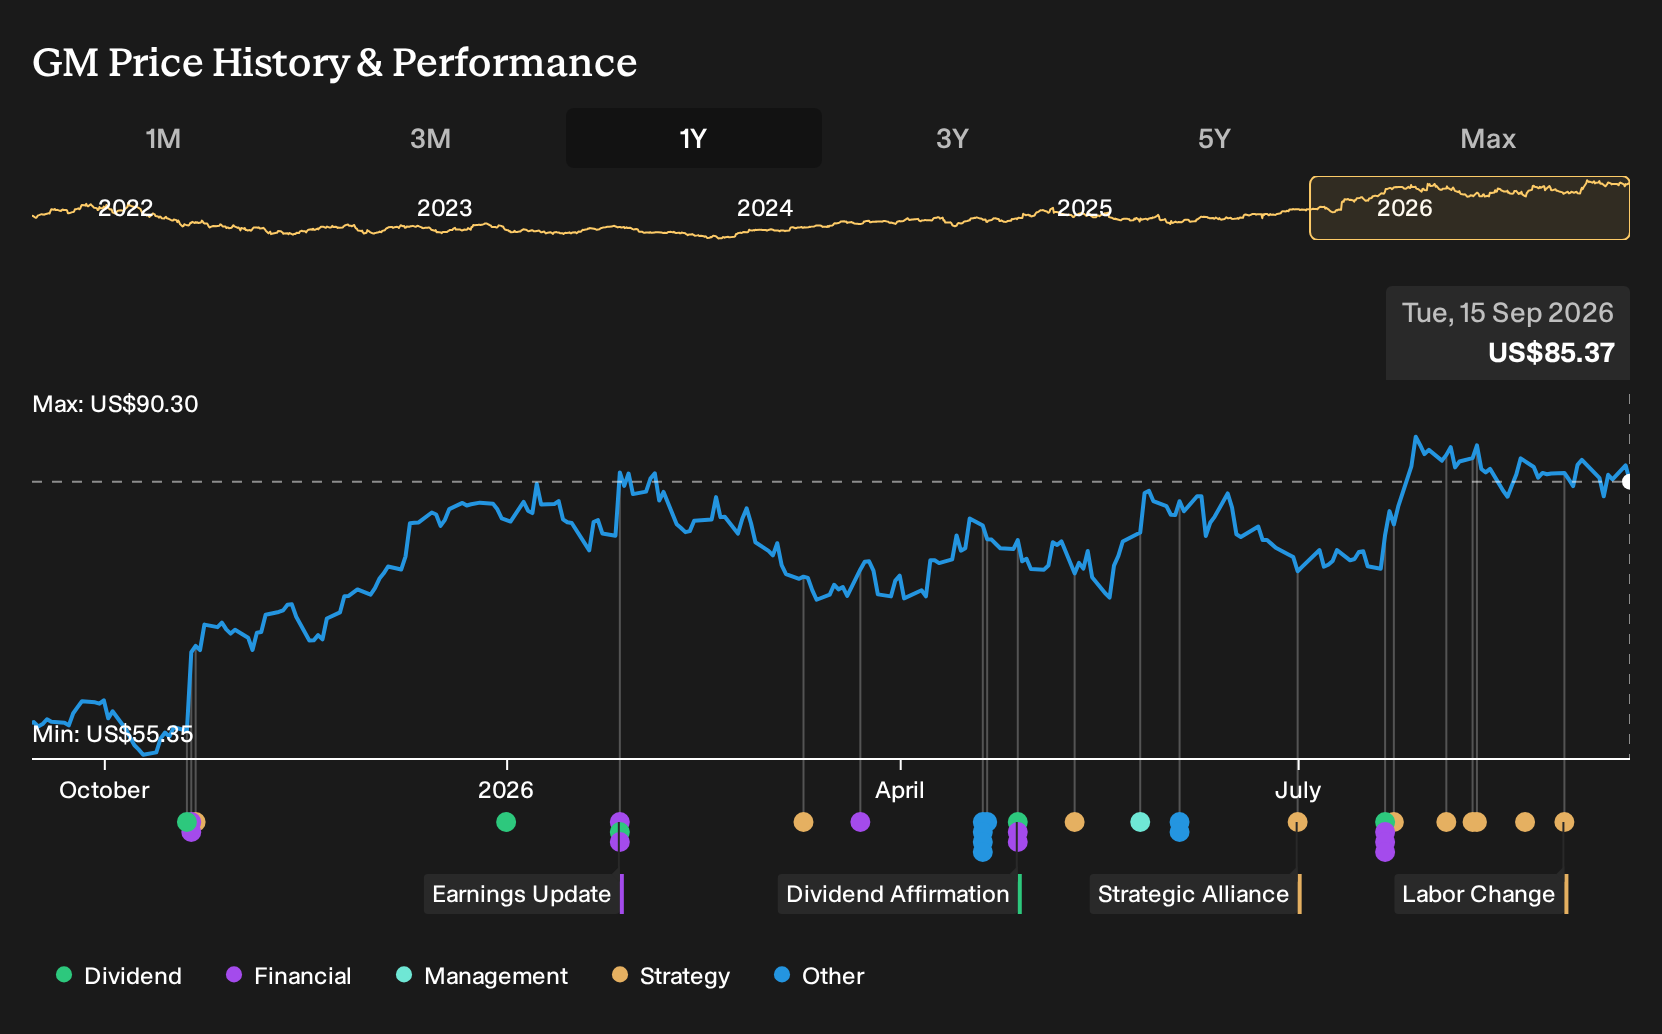
Exploring Other Perspectives
For a contrasting take on General Motors, the most optimistic analysts lean hard into the software catalyst. They were modelling roughly US$208.6b of revenue and US$18.9b in earnings by 2029, far above consensus, before this UBS digital update. You can use that gap to judge how much the new subscription focus might reshape those narratives.
Explore 7 other General Motors fair value estimates, including one that suggests potential upside of up to 60% from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your General Motors research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for General Motors. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate General Motors' overall financial health at a glance.
Looking For More Investment Ideas Beyond General Motors?
Once you have a view on General Motors, it can help to benchmark that thesis against other opportunities using the Simply Wall St Screener. That comparison lets you see whether GM's risk, balance sheet and potential upside align with the kind of portfolio you want to build.
- If capital preservation matters most to you, focus on resilience by scanning a curated set of 11 resilient stocks with low risk scores that may better suit a cautious approach.
- If dependable income is a priority, anchor your watchlist around 6 dividend fortresses that target higher yields with an emphasis on stability.
- If you prefer to hunt for mispriced opportunities, cast a wider net across a 16 high quality undiscovered gems that combine solid fundamentals with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com