
Tourmaline Oil (TSX:TOU) Declares Quarterly Dividend, Is It Still 11% Undervalued?
Tourmaline Oil (TSX:TOU) moved back into focus after declaring a CA$0.36 quarterly dividend ahead of the 15 September ex-dividend date, as recent energy price swings unsettled short-term sentiment.
The share price reaction has been relatively firm, with Tourmaline Oil up 7.07% on a 1 month share price return and 5.32% over 3 months. The 1 year total shareholder return of 6.79% and very large 5 year total shareholder return of 127.78% point to momentum that has cooled but not disappeared.
Seize this dividend moment around Tourmaline Oil to benchmark it against a hand picked group of income ideas in our 2 dividend fortresses.Tourmaline Oil has just pushed higher into its dividend date, which forces a timing call for anyone interested in the stock. Is paying up after this recent move sensible, or does patience make more sense on valuation grounds?
Most Popular Narrative: 11% Undervalued
Tourmaline Oil last closed at CA$63.72 against the widely followed fair value estimate of CA$71.45, which frames the current dividend decision around whether that gap feels justified.
Strategic build-out of low-cost, high-margin inventory in the Northeast BC Montney, with associated infrastructure owned by Tourmaline, positions the company for meaningful production growth to 850,000 BOE/d by early next decade, which, at flat pricing, will more than double annual free cash flow, supporting higher future dividend payments and potential buybacks.
See why 100 investors see Tourmaline Oil as 11% undervalued.
Result: Fair Value of CA$71.45 (UNDERVALUED)
Still, heavy exposure to volatile natural gas pricing and large capital spending through 2031 could easily upset the current Tourmaline Oil valuation story.
Find out about the key risks to this Tourmaline Oil narrative.
Another View On Tourmaline Oil’s Valuation
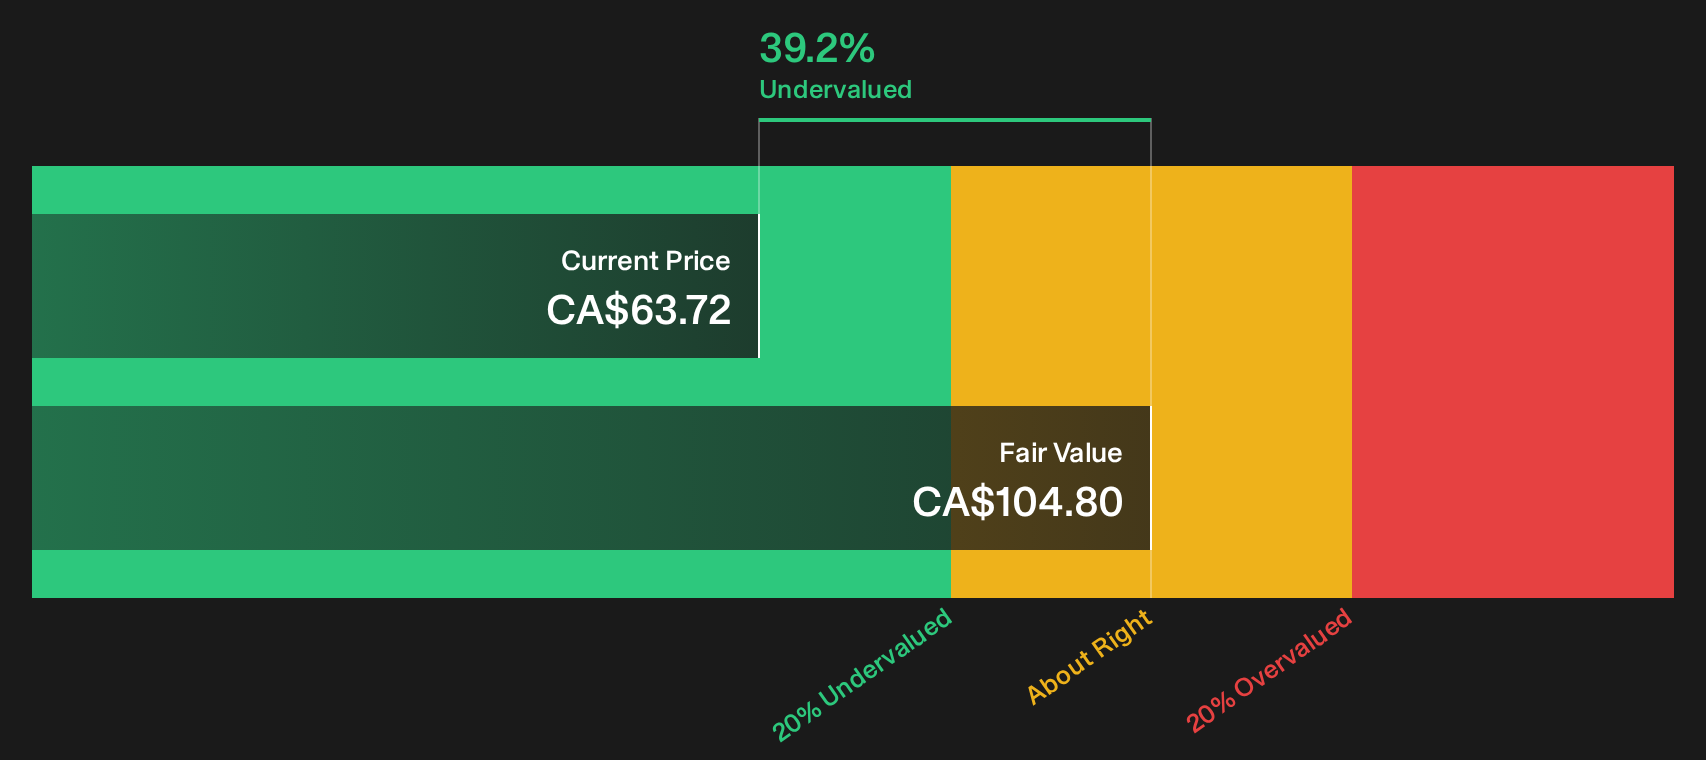
Tourmaline Oil screens as undervalued on the SWS DCF model, with the current CA$63.72 share price trading below an estimated future cash flow value of CA$104.80. That is a wide gap. The question for you is whether the cash flow assumptions behind that figure feel realistic enough to trust.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed feelings on Tourmaline Oil after all that. If the balance of risks and rewards feels finely poised, review the data for yourself, then weigh up the 2 key rewards and 3 important warning signs.
Looking for more ideas beyond Tourmaline Oil?
You have seen how Tourmaline Oil stacks up. Now widen the lens and pressure test your income and quality watchlist with a few focused stock screens.
- Target resilience first and stress test your downside by scanning 1 resilient stocks with low risk scores that aim to keep volatility in check while you stay invested.
- Hunt for quality at a sensible entry point by reviewing the 3 high quality undervalued stocks that currently combine fundamentals with pricing that may leave room for upside.
- Strengthen the backbone of your portfolio by filtering for a list of solid balance sheet and fundamentals (7 results) so sudden shocks in debt or liquidity do not catch you off guard.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com