
Is Hecla Mining (HL) Undervalued After Its Conference Spotlight?
Hecla Mining (HL) is set to present at the H.C. Wainwright 28th Annual Global Investment Conference on September 14, 2026. This event puts the silver producer in front of institutional capital.
Hecla Mining’s recent share price has pulled back, with a 7 day share price return of down 8.7% and a 1 day decline of 0.7%. However, the 90 day share price return of 16.3% and 1 year total shareholder return of 64.7% indicate momentum that long term holders have already felt.
Scan beyond Hecla Mining and see how other precious metals producers are setting up for their next move with the hand picked 10 top silver producer stocks.
After a sharp pullback on the week but a powerful run over the past year, Hecla Mining now forces a timing choice. Is this dip enough of an entry, or does the valuation still argue for patience?
Most Popular Narrative: 21% Undervalued
Hecla Mining last closed at $18.68, while the most followed narrative anchors fair value at $23.53, which points to a material gap that this conference appearance may either reinforce or challenge in investors’ minds.
Hecla is poised to benefit from accelerating demand for silver driven by ongoing global electrification and renewable energy growth, as silver is critical for EVs and solar panels. This positions the company for potential top-line revenue expansion and greater leverage to rising silver prices.
Elevated inflation and persistent macroeconomic uncertainty are fostering stronger investor demand for precious metals as safe havens, which can underpin higher realized silver prices and margin expansion for Hecla's silver-focused portfolio.
See why 59 investors see Hecla Mining as 21% undervalued.
Result: Fair Value of $23.53 (UNDERVALUED)
Still, the narrative around Hecla Mining depends on execution. Rising regulatory and environmental requirements and potential shareholder dilution are both capable of reshaping the story quickly.
Find out about the key risks to this Hecla Mining narrative.
Another View: Hecla Mining Through The P/E Lens
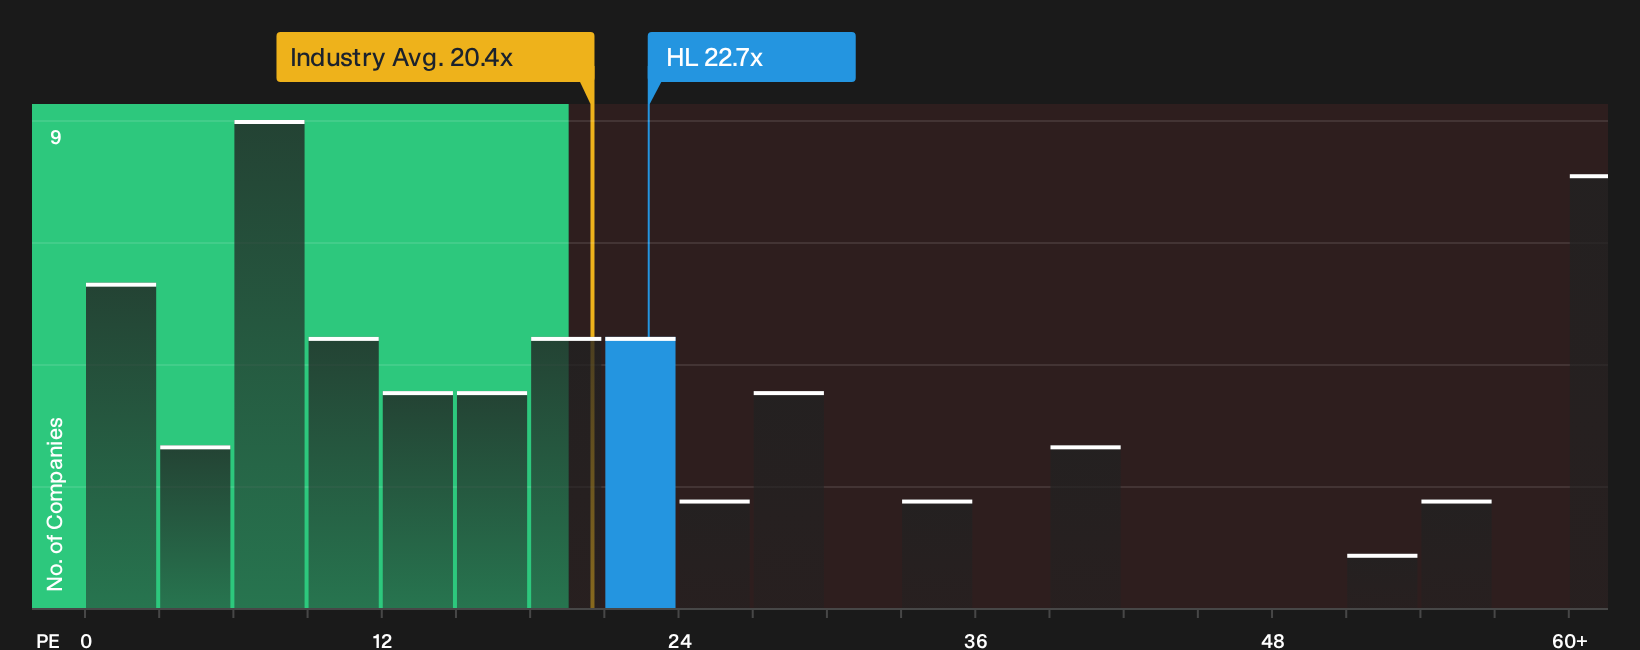
The fair value narrative for Hecla Mining points to upside, yet the simple earnings multiple paints a tougher picture. At a P/E of 22.7x, the stock trades above the estimated fair ratio of 22x, the US Metals and Mining industry at 20.4x, and a 17.6x peer average. That richer tag can mean less room for error if investor expectations cool.
To see how this pricing gap links back to the underlying numbers and where the market could shift next, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Hecla Mining is mixed in this piece, so consider your own position carefully and evaluate the thesis against your personal risk and reward tolerance. To see the upside case investors are focused on, start with the 2 key rewards.
Want more ideas beyond Hecla Mining?
Do not stop your research with a single silver producer. Use the Simply Wall St Screener to spot fresh ideas before the wider market pays attention.
- Target potential mispricings by scanning for companies that combine quality fundamentals with attractive valuations through the 34 high quality undervalued stocks.
- Support consistency seekers by reviewing businesses that offer robust payouts in the 6 dividend fortresses.
- Help reduce portfolio stress by focusing on financially resilient opportunities in the 11 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com