
Uber (UBER) Stock May Look Reasonable Following Spain Robotaxi Permit News
Uber Technologies has delivered a solid 61.0% share price gain over the past 5 years, yet recent volatility and mixed headlines leave a clear question for you as an investor. Is the current US$71.43 share price adequately supported by the earnings the business is generating today?
- That 61.0% rise over 5 years puts real weight on whether Uber’s current earnings base and profit trajectory can carry the valuation now attached to the stock.
- Big commitments to autonomous vehicles, AI driven operations and global restructuring, including job cuts and market exits, can reshape future profitability, cash needs and the timing of when earnings are available to shareholders.
- There is a second opinion on Uber Technologies worth weighing. See what analysts think Uber Technologies's shares could be worth.
The issue now is whether Uber’s earnings profile today, judged against its current P/E and related multiples, is enough to justify paying around US$71.43 per share.
If you are weighing whether Uber Technologies' 61.0% five year gain and current P/E feel justified, it can help to compare that same earnings lens across 34 high quality undervalued stocks.
Is Uber Technologies a Bargain on Earnings?
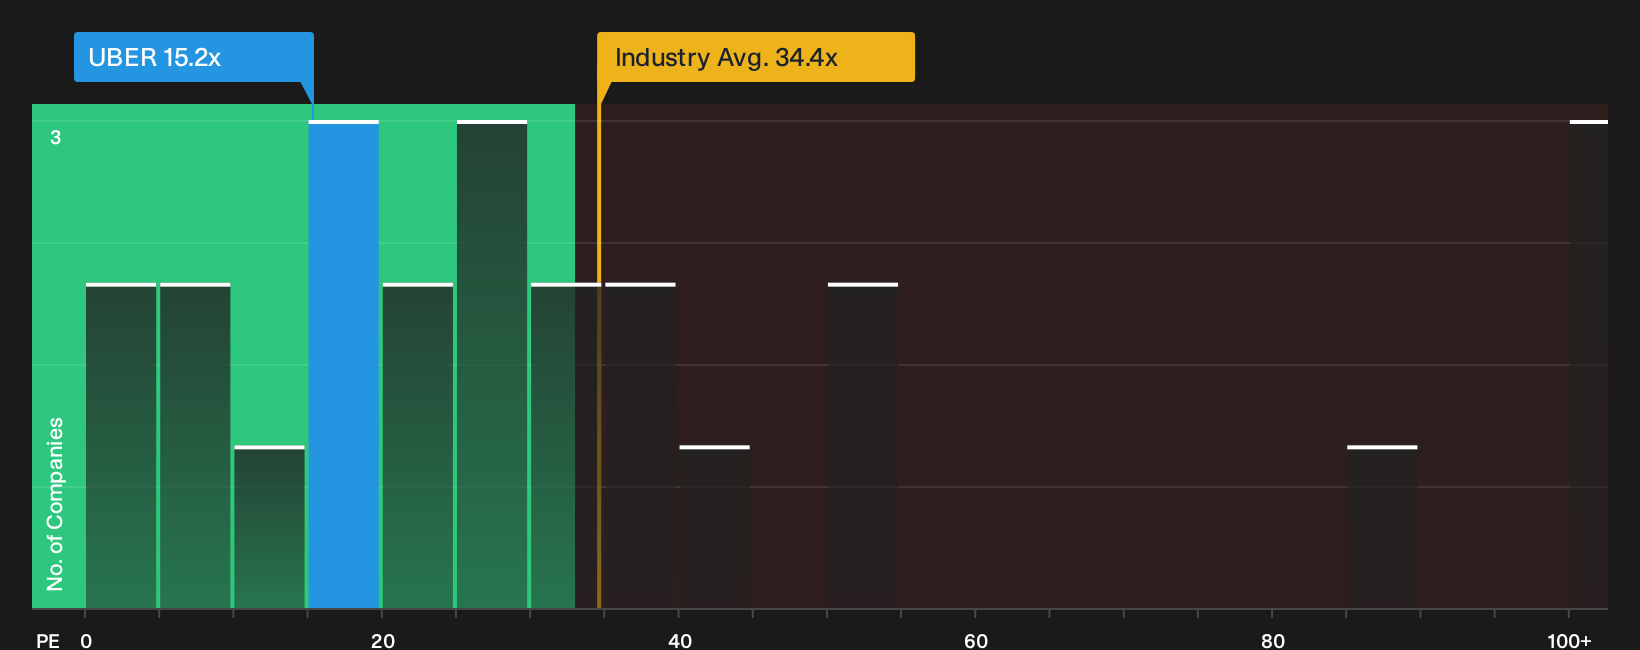
A P/E lens fits Uber Technologies because the market is currently rewarding the business primarily on its earnings power rather than its assets or revenue alone. On this measure, Uber trades on a P/E of about 15.2x, compared with roughly 34.4x for the wider Transportation group and a peer average near 45.9x, so the stock changes hands at a sizeable discount to both its sector and closer comparables.
The fair multiple implied by Uber’s own profile is higher than where the shares trade, so the current 15.2x sits below what this tailored yardstick suggests. This points to the stock screening as undervalued on this framework. Because recent insider share purchases and the push into autonomous vehicles have attracted fresh attention to Uber, that discount is worth weighing carefully if you think the recent restructuring and technology bets can sustain the current earnings base. Explore the numbers behind Uber Technologies's P/E valuation.
The Uber Technologies Narrative: What Would Justify Today's Price?
Simply Wall St Narratives act as the missing link between Uber Technologies' current valuation puzzle and the future assumptions investors are implicitly making about growth, profitability and earnings power at today's share price. Each narrative sets out a clear, testable view of what would need to hold true for the stock to be worth materially more or less over time. It also treats fair value as a thesis about Uber Technologies' business that you can track as new information arrives on the Community page.
Community views on Uber Technologies split between investors who see extra upside in the current price and others who think expectations already capture most of what the business is likely to deliver.
Bull case: 38% undervalued
"Management intends to commit more than $10 billion over several years to autonomous-vehicle partners, fleet operations and vehicle commitments…"
Discover why this Narrative puts Uber Technologies at 38% undervalued.
Bear case: roughly fairly valued
"While early autonomous vehicle partnerships with NVIDIA and Waymo aim to create a hybrid network of human drivers and AVs, management expects AV operations to remain unprofitable for a few years…"
Explore why this Narrative puts Uber Technologies at roughly fairly valued.
One more Uber Technologies check that belongs beside the current share price
Price multiples tell you what investors are paying for Uber Technologies today, but the missing piece is how professional analysts think the business might look a few years from now. Explore where analysts expect Uber Technologies to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com