
Norfolk Southern (NSC), What Is Behind The Fresh Attention?
Norfolk Southern (NSC) is back in the spotlight after management joined Morgan Stanley’s 14th Annual Laguna Conference, giving investors fresh commentary on the railroad’s operations, capital plans, and progress on key freight initiatives.
Norfolk Southern shares trade at US$320.22, with the stock giving up some ground over the past month even as the proposed Union Pacific combination and new Charleston to Huntsville rail service keep attention on its role in Southeastern freight corridors.
Scan beyond Norfolk Southern and evaluate other rail and freight beneficiaries of these corridor shifts with a curated set of 38 power grid technology and infrastructure stocks
After a strong 1 year run and a recent pullback, Norfolk Southern now sits at US$320.22 with fresh growth projects on the table. Does that price still skew the risk reward toward buyers?
Most Popular Narrative: 12% Undervalued
Norfolk Southern’s most followed valuation storyline puts fair value at about $363.72, above the last close at $320.22, which keeps the stock framed as undervalued in that narrative.
The analysts have a consensus price target of $363.72 for Norfolk Southern based on their expectations of its future earnings growth, profit margins and other risk factors.
However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of $414.0, and the most bearish reporting a price target of just $297.0.
See why 11 investors see Norfolk Southern as 12% undervalued.
Result: Fair Value of $363.72 (UNDERVALUED)
Still, that 12% discount story can fray quickly if storm related costs keep biting into profitability, or if coal pricing and intermodal competition weaken key freight corridors.
Find out about the key risks to this Norfolk Southern narrative.
Another View On Norfolk Southern’s Valuation
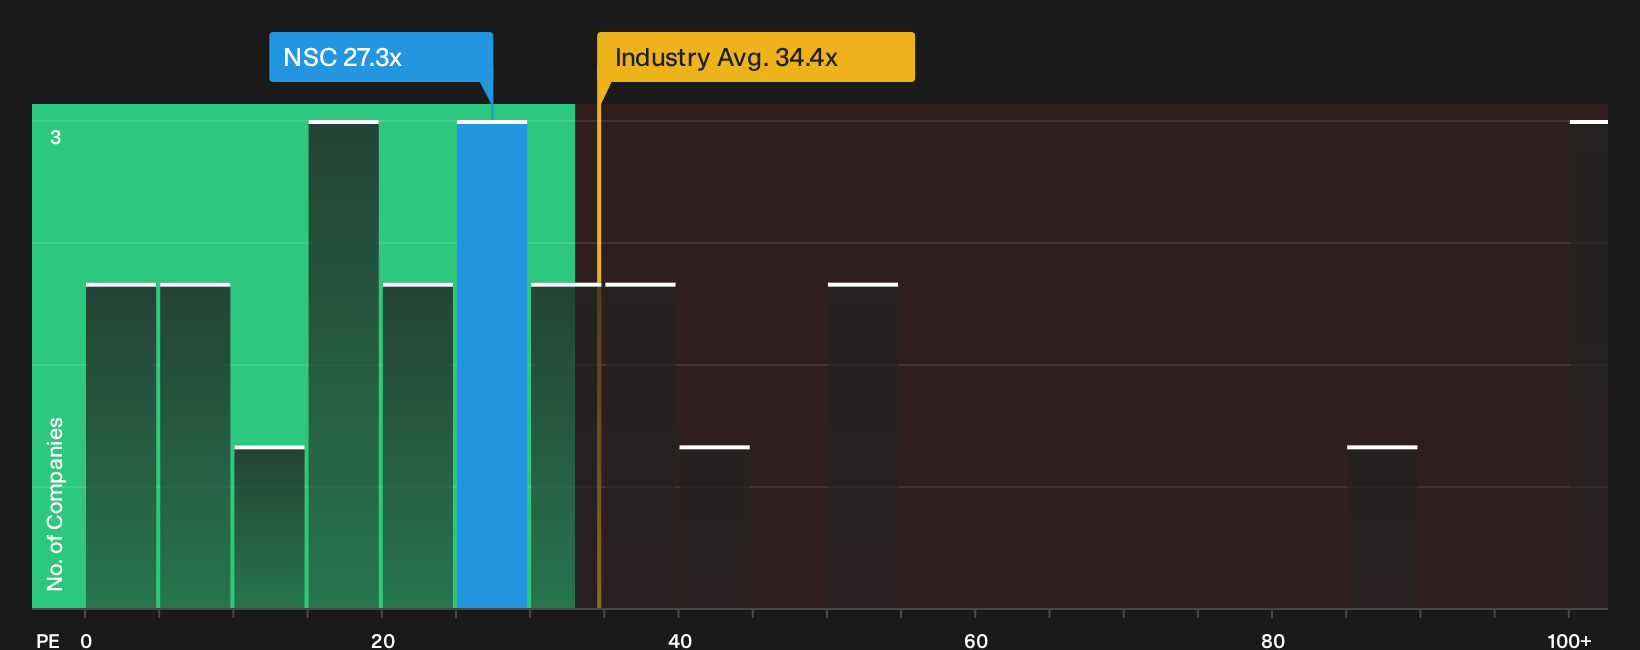
Analysts lean on earnings forecasts to argue Norfolk Southern is about 12% below fair value, yet the P/E picture tells a different story. The stock trades at 27.3x earnings versus a 25.5x peer average and a 24.4x fair ratio, which points to less upside and more valuation risk if sentiment cools.
For a closer look at how the earnings multiple stacks up against what the numbers imply, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Norfolk Southern so far. If you want to move quickly and judge the trade-off for yourself, start with the 3 key rewards and 1 important warning sign.
Looking for more ideas beyond Norfolk Southern?
You have a clear view on Norfolk Southern. Now give yourself options by scanning other opportunities that might fit your style before the next move arrives.
- Target income resilience with companies that pay meaningful yields and show staying power by checking a curated group of 6 dividend fortresses.
- Hunt for quality at a discount by running through our hand picked set of 16 high quality undiscovered gems that combine solid fundamentals with less market attention.
- Prioritise capital preservation first and filter for steadier performers using a focused batch of 11 resilient stocks with low risk scores before committing fresh money.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com