
IQVIA (IQV) Stock Looks Cheap Even After A 44% Run
IQVIA Holdings has delivered a strong share price run, and the question now is whether that climb is matched by the cash flows that underpin the business. With a Discounted Cash Flow (DCF) estimate available, investors are weighing up how closely the current trading level lines up with the cash the company is expected to generate.
- IQVIA Holdings has returned 44.4% over the past year, which puts real pressure on the valuation question of whether that move is supported by the strength and durability of its cash flows.
- The recent pricing of US$2b in senior notes that are intended to refinance nearer term borrowings may reshape interest costs and the timing of cash available to equity holders, which feeds directly into any cash flow based valuation work.
- Prefer to judge IQVIA Holdings on earnings? See why IQVIA Holdings's 32.3x P/E tells a different valuation story.
The issue now is whether the current share price around US$269.67 can be explained by the intrinsic value suggested by IQVIA Holdings' future cash flows.
If IQVIA Holdings has you thinking hard about whether recent returns line up with its cash flows, it can help to compare it with 34 high quality undervalued stocks.
Is IQVIA Holdings a Bargain on Cash Flow?
The Discounted Cash Flow model here looks at the cash IQVIA Holdings can return to shareholders based on its own free cash generation. Over the last twelve months, the business produced about $2.2b of free cash flow, and the projections used in the model assume that this cash generation continues to grow over the coming years rather than shrink.
Those rising forecasts, combined with a 2 Stage Free Cash Flow to Equity setup, result in an estimated intrinsic value that sits meaningfully above the current share price of $269.67. The recent pricing of $2b in senior notes due 2034, which is earmarked to refinance nearer term debt, helps explain why the Discounted Cash Flow outcome supports a richer valuation than the equity market is currently offering. Find out what IQVIA Holdings could be worth using our Discounted Cash Flow (DCF) estimate.
The IQVIA Holdings Narrative: What Would Justify Today's Price?
Narratives for IQVIA Holdings pick up where the DCF puzzle leaves off and explain which paths for growth, profitability and earnings would need to occur for the share price to end up materially higher or lower than it is today. These are all housed on Simply Wall St's Community page. Each narrative then links its number to a specific view on how IQVIA Holdings' expansion prospects, margin profile and key risks might change, giving you a reference point you can revisit as new information arrives.
IQVIA Holdings draws two very different community read throughs, with one camp seeing more upside in the story than the other.
Bull case: roughly fairly valued
"Record R&D Solutions backlog and strong sequential increases in qualified pipeline and RFP flow indicate sustained demand for outsourced clinical research…"
Discover why this Narrative puts IQVIA Holdings at roughly fairly valued.
Bear case: 11% overvalued
"Increasing data privacy regulations worldwide, including potential future expansions of GDPR and new US federal laws, will significantly restrict IQVIA's ability to collect, process, and monetize healthcare and real-world data…"
Explore why this Narrative puts IQVIA Holdings at 11% overvalued.
One more IQVIA Holdings signal worth pulling up
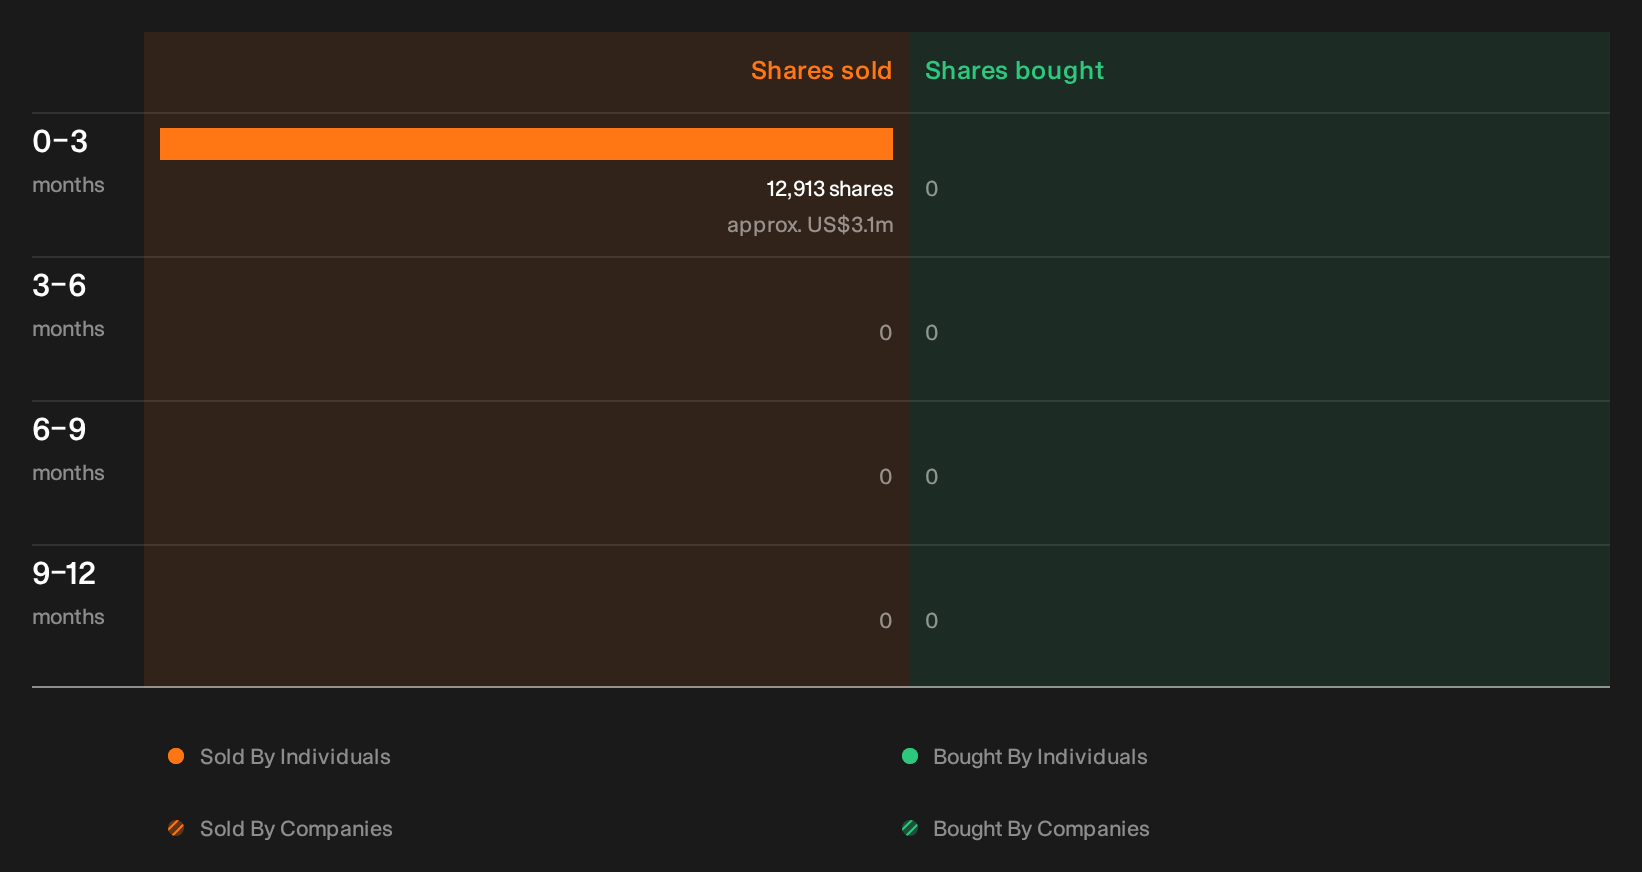
There is one extra clue that deserves a closer look, with recent share sales by people on the inside of IQVIA Holdings flagged by our checks, and the specific sellers, volumes and context left for you to explore. See the recent insider selling flagged for IQVIA Holdings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com