
Why Did RB Global (NYSE:RBA) Shares Move Today?
RB Global (RBA) has secured Toronto Stock Exchange approval to expand its normal course issuer bid, increasing the potential share repurchase pool to as many as 14,224,129 shares or US$1 billion.
RB Global shares have picked up short-term momentum, with a 1-day share price return of 2.48% and a 7-day gain of 5.17%. However, the 90-day share price return has fallen 19.76%, and the 1-year total shareholder return has declined 25.77%, even after a 54.72% total shareholder return over five years.
Compare RB Global’s buyback-driven value story with other companies that screen well on quality and pricing by scanning our hand picked 34 high quality undervalued stocks.
RB Global is signaling it likes its own share price enough to spend up to US$1b buying stock back. Do you treat that as a window to act now, or wait for an even cheaper entry before the valuation work stacks up for you?
Most Popular Narrative: 33% Undervalued
RB Global’s widely followed narrative pegs fair value at $127.73, well above the recent $86.11 close. This puts the latest $1b buyback capacity in a very specific valuation context for anyone weighing the current pullback.
Strategic global expansion and technology investments are enhancing operational efficiency, supporting higher transaction volumes, and driving long-term revenue and margin growth.
Continued expansion of value-added services such as data analytics, transportation, and financial solutions is increasing service revenue, improving overall earnings quality, and contributing to margin expansion through higher-margin offerings.
See why 3 investors see RB Global as 33% undervalued.
Result: Fair Value of $127.73 (UNDERVALUED)
Still, RB Global’s story can break if macro pressures keep transaction volumes soft or if acquisitions and new markets introduce costs that drag on margins.
Find out about the key risks to this RB Global narrative.
Another View On RB Global’s Valuation
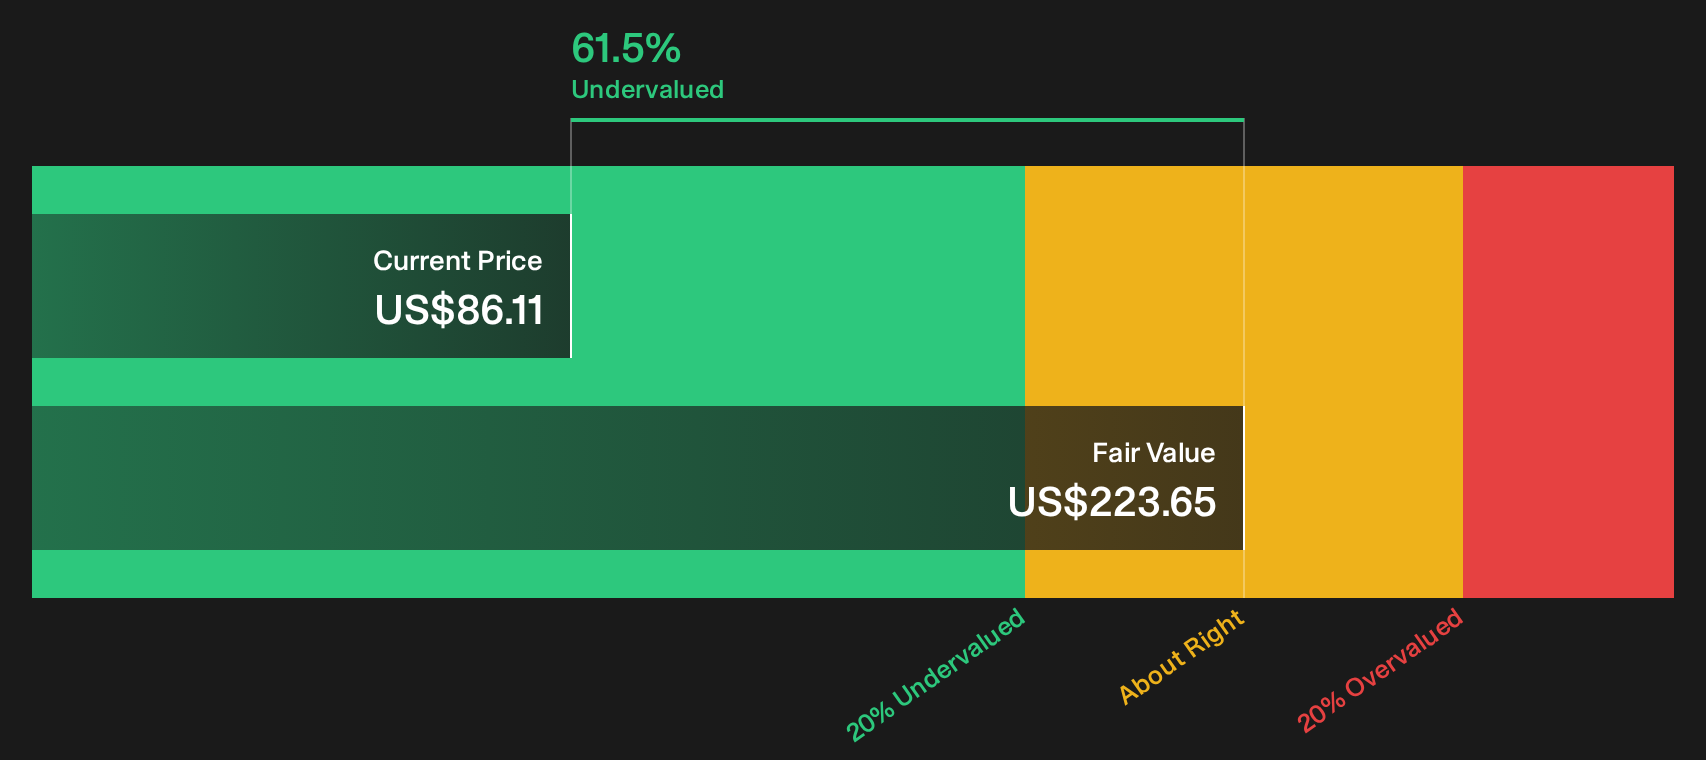
RB Global screens as cheap against the SWS DCF model, with an estimated future cash flow value of $223.65 versus the recent $86.11 share price. That points to a large implied gap. The question is whether you trust long dated cash flow assumptions more than today’s market multiple.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around RB Global’s buyback and valuation story can feel tricky, so act while the data is fresh and shape your own view with 5 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond RB Global?
RB Global might be on your radar today, but your next strong idea could come from widening the search with a few targeted screeners that surface very different types of opportunities.
- Target steadier compounding potential by checking companies built to generate dependable income and resilient yields with 6 dividend fortresses.
- Hunt for mispriced prospects that combine strong fundamentals with appealing entry prices using the curated 16 high quality undiscovered gems.
- Prioritize capital protection first and look for businesses with sturdier financial footing through a focused 11 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com