
Bank Of Montreal (TSX:BMO) Is Back In The Spotlight But Why?
Bank of Montreal (TSX:BMO) has been active in the debt markets, filing a large US$75b shelf registration and issuing new U.S. dollar, Canadian dollar and sterling notes across multiple maturities.
Despite all this balance sheet activity, Bank of Montreal’s share price has cooled in the near term, with a 1‑month share price return down 6.28%, even as the year to date share price return is 33.08% and the 5‑year total shareholder return is 138.46%. This suggests longer term momentum remains strong, while recent trading reflects investors reassessing risk and funding costs around its fresh wave of bond and capital issuance.
Scan how Bank of Montreal’s funding moves compare with other large lenders by reviewing the hand-picked list of solid balance sheet and fundamentals (7 results) for potential ideas in the same space.
Bank of Montreal now trades well below recent highs after an intense funding push. Does that reset leave enough upside, after factoring in richer capital costs, to keep the risk reward tilted toward buyers?
Most Popular Narrative: 5% Undervalued
Bank of Montreal’s most followed valuation storyline pegs fair value at about CA$255 per share, a shade above the CA$241.69 last close. This frames the recent pullback as a gap between narrative and screen price rather than a collapse in conviction.
BMO's continued investment in digital and AI-powered banking platforms, such as the LUMI Assistant and multiple award-winning payment innovations, is improving operational efficiency and customer engagement, which should drive increased net margins and persistently positive operating leverage.
See why 90 investors see Bank of Montreal as 5% undervalued.
Result: Fair Value of CA$255 (UNDERVALUED)
Still, if Canadian growth stays weak or credit issues in unsecured retail and commercial real estate build, the upbeat Bank of Montreal narrative could weaken quickly.
Find out about the key risks to this Bank of Montreal narrative.
Another View: What P/E Says About Bank of Montreal
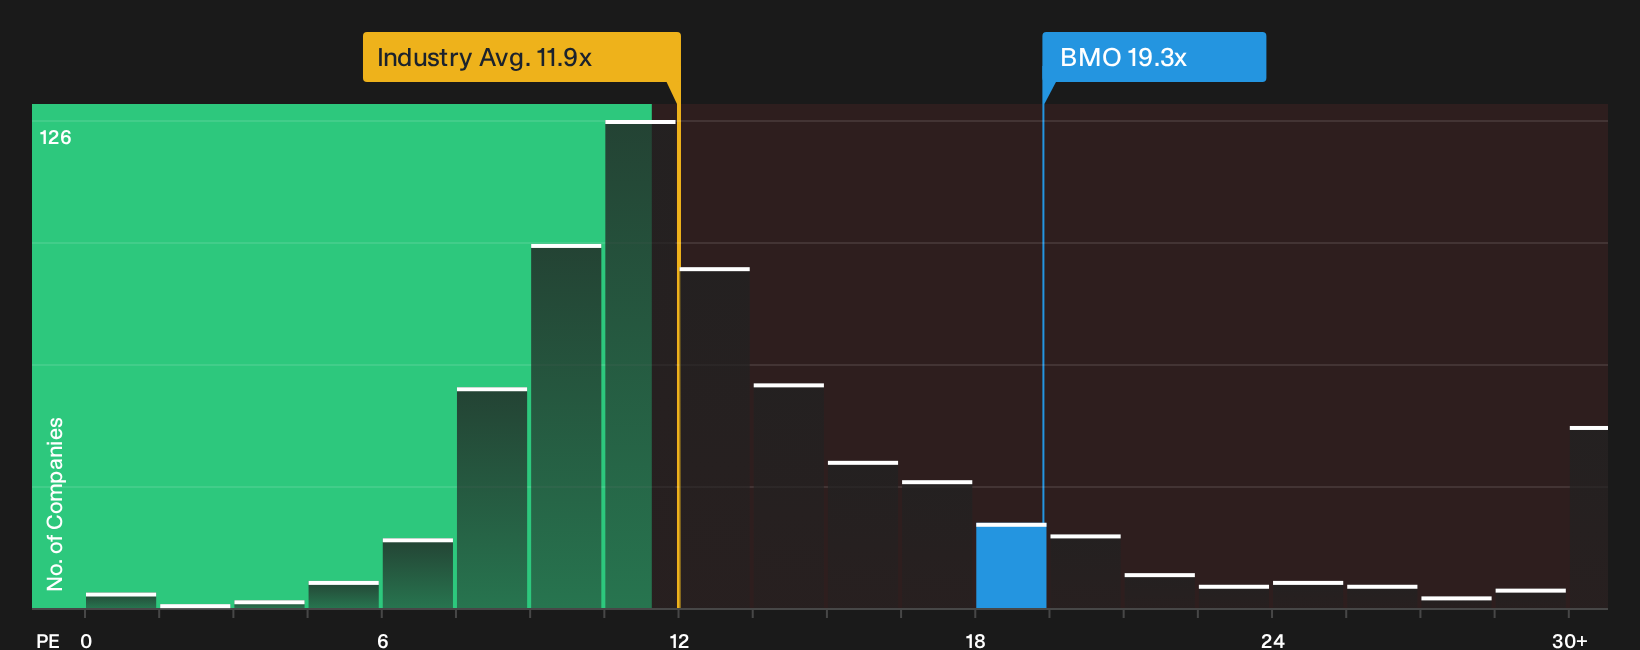
The SWS DCF model sees Bank of Montreal trading at about a 22% discount to an estimated future cash flow value of CA$309.06 per share. On simple P/E, however, the picture flips. The bank trades around 19.3x earnings, above a fair ratio of 18x.
That multiple also sits higher than both the North American banks industry at 11.9x and the peer average at 16.6x, which points to less room for error if earnings underwhelm. Investors now have to weigh a rich earnings multiple against a cheaper cash flow view and decide which story they trust.
See what the numbers say about this price and find out in our valuation breakdown. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Bank of Montreal can easily pull you in opposite directions, so move fast, review the full data set, and weigh both the 3 key rewards and 1 important warning sign.
Looking for more Bank of Montreal investment ideas?
Do not stop your research with Bank of Montreal alone. Broaden your watchlist with focused stock lists that surface very different ways to put capital to work.
- Target resilience by scanning a curated 1 resilient stocks with low risk scores that highlights businesses with sturdier profiles when conditions get choppy.
- Hunt for value by reviewing a hand picked 3 high quality undervalued stocks that spotlight companies where price trails fundamentals.
- Build income potential by sifting through a 2 dividend fortresses that focuses on higher yielding stocks with staying power.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com