
Kerui: The off-season effect deepened, and second-hand residential transactions in key cities declined simultaneously in August
The Zhitong Finance App learned that in August 2026, the real estate market in key cities continued to adjust during the traditional off-season: the scale of new housing transactions hit a new low since March, and the year-on-year decline increased markedly; second-hand housing transactions “fell four times in a row” month-on-month, and the year-on-year increase narrowed for three consecutive months but remained positive, and still occupied an absolute dominant position in transactions. Looking ahead to the future market, the intensive implementation of new sales systems and credit management policies at the central level at the end of August, as well as the loosening of local policies such as Beijing and Shanghai, is expected to inject expected support into the “gold nine silver ten” market restoration. The year-on-year decline in new housing transactions in September is expected to narrow, and demand for second-hand housing is expected to remain high.
Overall Overview
The off-season effect deepened, and the total volume of second-hand transactions fell 9.26% month-on-month.
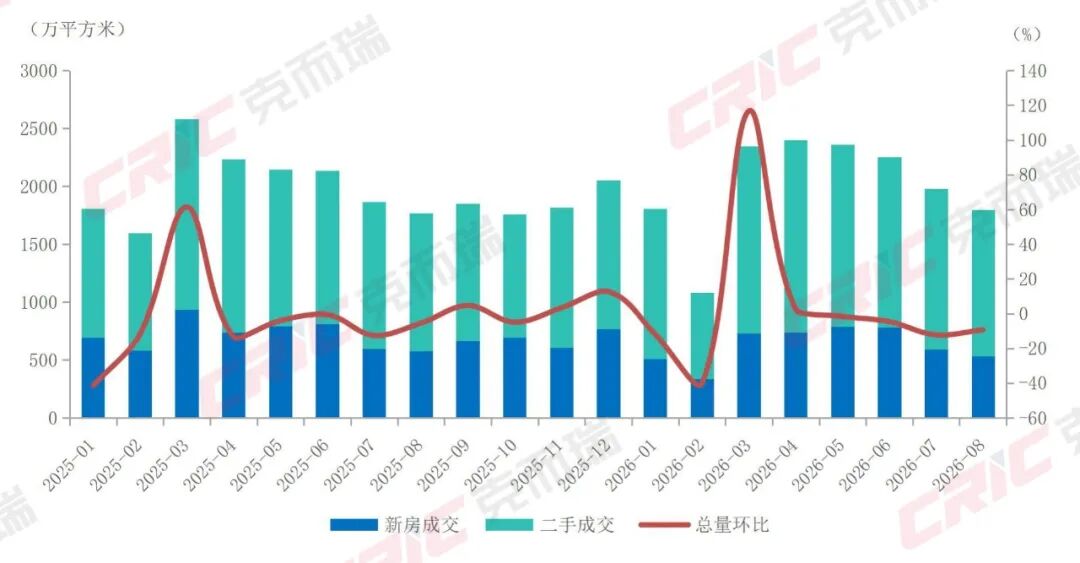
In August 2026, the total volume of housing market transactions (new building+used) in 14 key cities was about 17.967,900 square meters, down 9.26% from the previous month. The decline was 2.96 percentage points narrower than July, and up 1.70% year on year. Among them, new commercial residential transactions were 5.3337 million square meters, down 10.00% from the previous month and 7.65% from the previous year; second-hand residential transactions were 126.34,200 square meters, down 8.95% from the previous month and up 6.23% from the previous year. The total volume maintained positive year-on-year growth, mainly dependent on the resilient support of the second-hand housing market.
At the structural level, the share of second-hand housing transactions in 14 cities reached 70.32%, up another 0.25 percentage point from July (70.07%). It remained stable at more than 70% for two consecutive months, while the share of new homes fell to 29.68%. Under the “volume reduction” of second-hand goods, the trend of demand tilting towards the stock market has not changed.
Figure 1 Trends in the transaction area of newly built and second-hand housing in 14 key cities across the country from January 2025 to August 2026
Data source: CRIC China Real Estate Decision Consulting System.
Scope of 14 cities: Beijing, Shanghai, Guangzhou, Shenzhen, Hangzhou, Chengdu, Xi'an, Wuhan, Tianjin, Nanjing, Suzhou, Chongqing, Changsha, and Foshan.
Newly built commercial housing market
Supply rebounded 3.2% month-on-month, and the year-on-year decline in transactions widened to 7.5%.
1. Overall supply and demand: low supply recouped, transactions shrank in the off-season, and the supply-demand ratio rebounded to 0.70
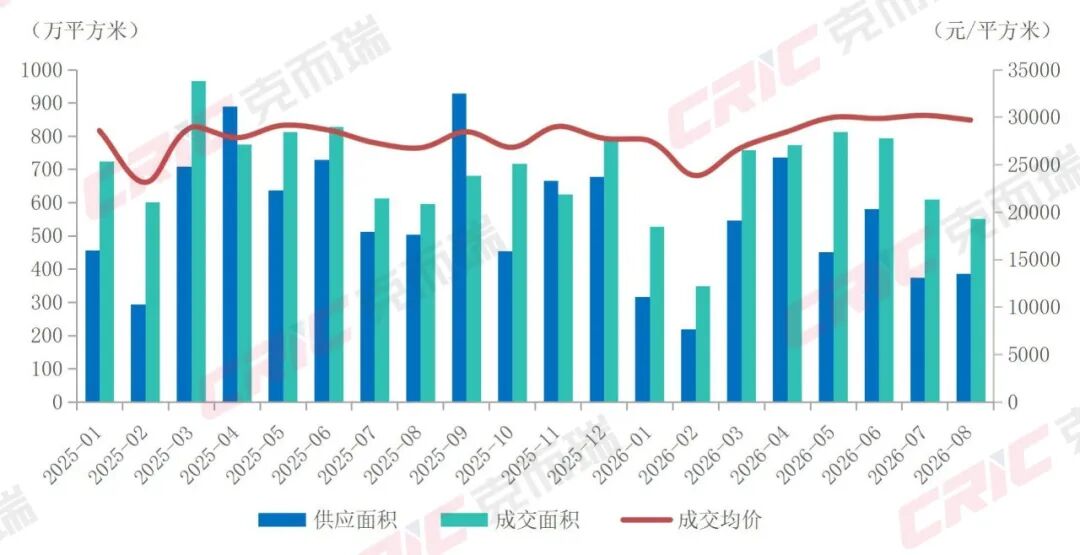
In August, the supply of newly built commercial housing rebounded slightly from month to month in 15 cities, while sales continued to decline during the off-season, and the ratio between supply and demand rebounded marginally. According to CRIC monitoring, a new supply of 3.866,300 square meters was added in the same month, up 3.24% from the previous month, down 23.36%; the transaction was 5.507 million square meters, down 9.61% from the previous month, down 7.53% from the previous month, up 6.99 percentage points from the previous month; the supply-demand ratio was 0.70, up from 0.61 in July, but it is still in the range where supply is less than demand.
The month-on-month recovery on the supply side was mainly driven by concentrated sales in some cities at the end of the month: “Gold Nine, Silver Ten” is approaching, housing companies' willingness to obtain evidence has been marginally restored. Cities such as Beijing, Shenzhen, Hangzhou, and Suzhou have clearly increased supply, and the characteristics of supplementary promotion are obvious under a low base. However, from a year-on-year perspective, supply still fell sharply by 23.36%, and the strategic direction of “determining production by sales” has not changed. Judging from the cumulative data, the total supply of 15 cities from January to August 2026 was about 36.595 million square meters, a cumulative year-on-year decrease of about 23.8%, and supply contracted throughout the year.
The month-on-month decline at the transaction end is in line with seasonal rules. On a year-on-year basis, the decline in new housing transactions widened again to 7.53% in August, showing that under the dual effects of shrinking supply and weakening demand in the off-season, the basis for stabilizing the bottom of the new housing market is still not strong, and the year-on-year repair of transactions is still repeated. Judging from the cumulative data, the total number of transactions in January-August 15 was 51.77,600 square meters, a cumulative year-on-year decrease of 12.5%, and 0.6 percentage points narrower than in January-July.
In terms of price, the average price of newly built commercial housing transactions in August 15 was 29,679 yuan/square meter, down 1.60% from the previous month and up 10.92% from the previous year. The year-on-year increase was slightly wider than in July. Prices continued to increase positively year over year. On the one hand, it was affected by the transaction structure base for the same period last year. On the other hand, the centralized filing of high-end projects in the core locations of first-tier cities and key second-tier cities during the month had a structural impact on average prices.
Figure 2 Supply and demand volume and price trends of newly built commercial housing in 15 key cities across the country from January 2025 to August 2026
Data source: CRIC China Real Estate Decision Consulting System; Statistical Caliber: Commercial housing, including residences, villas, and serviced apartments.
Scope of 15 cities: Beijing, Shanghai, Guangzhou, Shenzhen, Hangzhou, Chengdu, Xi'an, Wuhan, Tianjin, Nanjing, Suzhou, Chongqing, Hefei, Changsha, and Foshan.
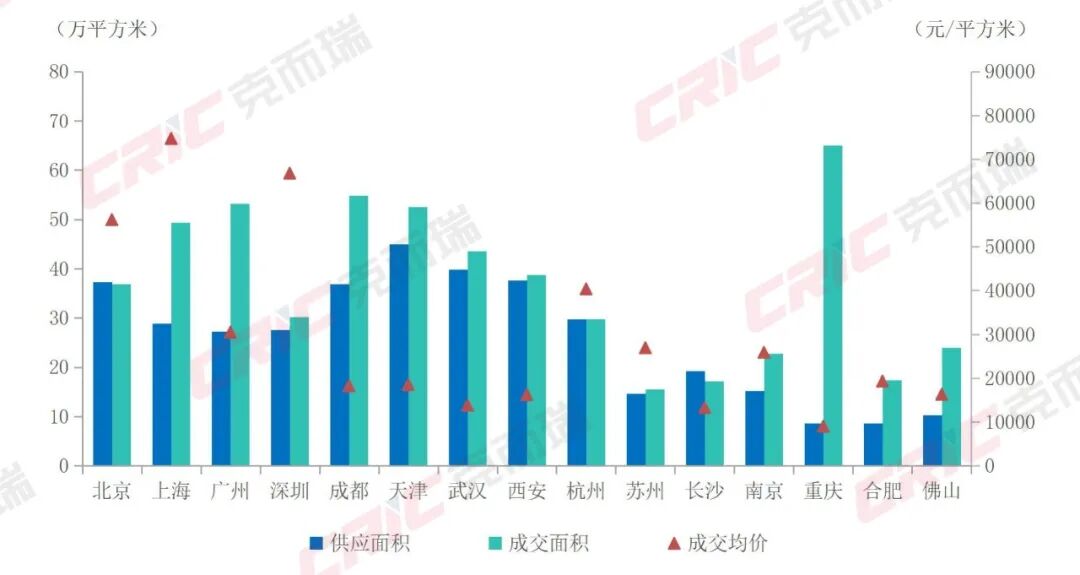
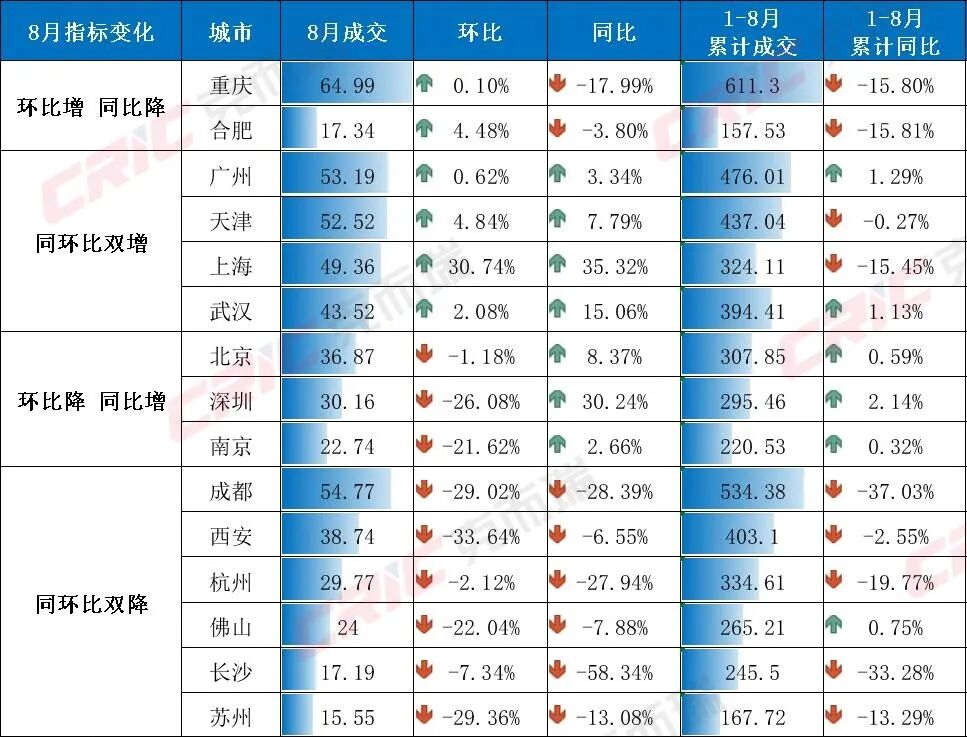
Looking at the city level, the newly built commercial housing transactions in the city on August 15 showed obvious characteristics of scale differentiation. Chongqing led with 649,900 square meters, followed by Chengdu (547,700 square meters) and Guangzhou (531,900 square meters). The three cities sold a total of 1,729,500 square meters, accounting for about 31% of the total volume of the 15 cities. Tianjin (5252,000 square meters) and Shanghai (493,600 square meters) also ranked among the highest in terms of transaction volume. Among them, Guangzhou had a month-on-month increase (+0.62% month-on-month and +3.34% year-on-month), while Shanghai surged 30.74% month-on-month, with the most outstanding performance among first-tier cities.
Figure 3 Supply and demand volume and price performance of newly built commercial housing in 15 key cities across the country in August 2026
Data source: CRIC China Real Estate Decision Consulting System.
The year-on-year performance differentiation was particularly significant. Seven of the 15 cities achieved positive year-on-year growth: Shanghai (+35.32%) and Shenzhen (+30.24%) had the highest gains, while cities such as Wuhan (+15.06%) and Beijing (+8.37%) maintained positive growth, and market recovery momentum was relatively strong. On the other hand, Changsha fell sharply by 58.34% year on year, and market adjustment pressure was relatively prominent. Chengdu (-28.39%) and Hangzhou (-27.94%) also saw significant declines. Suzhou changed from increase to decline this month after the base figure rose in the same period last year.
On a month-on-month basis, the number of cities that achieved positive growth expanded from 3 cities last month to 6 cities, and there was an increase in month-on-month stability. Among them, Shanghai led the way with an increase of 30.74%. The remaining nine cities saw month-on-month declines. Among them, Xi'an (-33.64%), Suzhou (-29.36%), Chengdu (-29.02%), and Shenzhen (-26.08%) had the highest declines, and the general characteristics of off-season cooling were obvious.
Looking at the volume price bureau, the average transaction price in Beijing is 56,178 yuan/square meter, Shanghai 7,4710 yuan/square meter, and Shenzhen 66,779 yuan/square meter, still forming the first tier of prices. Among them, Shanghai “volume increased and price fell”. In August, transactions rebounded 30.74% month-on-month, and the average price fell 11.47% month-on-month. The volume characteristics of mid-tier projects were obvious; Hangzhou (40,363 yuan/square meter) was affected by the transaction structure, and the average price rose 19.82% year on year, but fell 14.70% month-on-month, with large monthly fluctuations. On a month-on-month basis, only the three cities of Beijing (+2.91%), Tianjin (+1.03%), and Changsha (+3.90%) showed positive increases in average prices.
Table 1. Transaction area and changes of newly built commercial housing in 15 key cities across the country in August 2026 (unit: 10,000 square meters)
Data source: CRIC China Real Estate Decision Consulting System.
2. Transaction structure: the proportion of 90-130 square meters rose to 52.44%, and the share of large units declined marginally
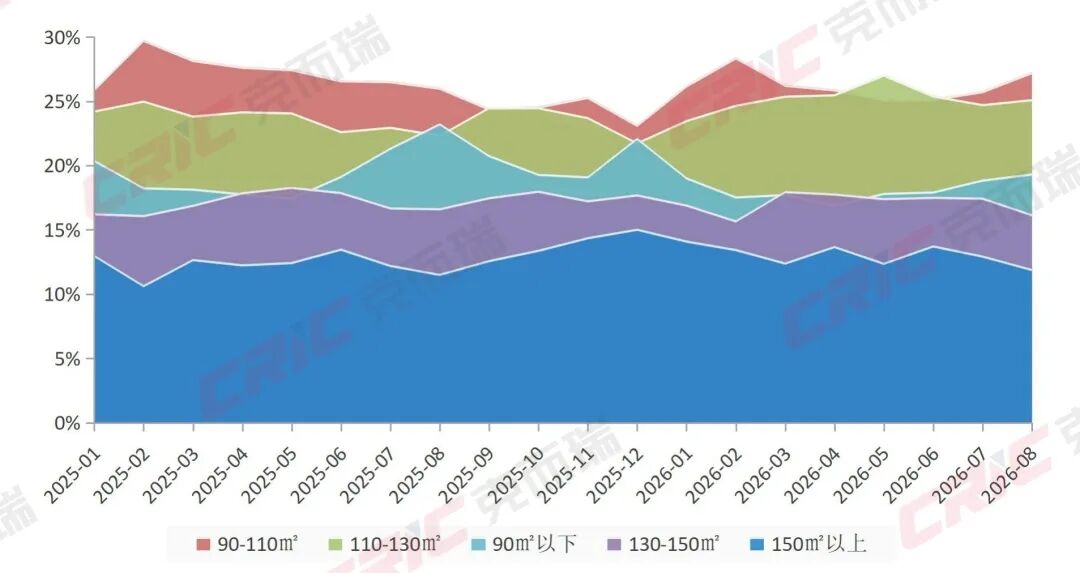
In August, the transaction structure of newly built commercial housing in 15 cities showed a marginal change of “just need to pick up, high-end decline” — the two main segments of 90-110 square meters and 110-130 square meters rebounded simultaneously, while the improvement levels above 130 square meters declined markedly. According to CRIC monitoring, the number of units sold under 90 square meters accounted for 19.39%, up 0.48 percentage points from July; 90-110 square meters accounted for 27.27%, an increase of 1.48 percentage points, the biggest increase in each category and a new high since March 2026; 110-130 square meters accounted for 25.17%, an increase of 0.39 percentage points; 130-150 square meters accounted for 16.22%, a decrease of 1.29 percentage points; 150 square meters or more accounted for 11.96%, a decrease of 1.04 percentage points. The total proportion of improved products above 130 square meters was 28.18%, down 2.33 percentage points from 30.51% in July, mainly affected by the slowdown in the promotion and filing of high-end projects this month.
Looking at the longer cycle, the 90-130 square meter area is still the main transaction force. August accounted for 52.44% of the total, an increase of 3.98 percentage points over the same period last year (48.46%), further consolidating its dominant position. Looking at the structure year over year, 110-130 square meters increased 2.77 percentage points, 90-110 square meters increased 1.21 percentage points, 150 square meters or more increased 0.38 percentage points, while 90 square meters or less decreased by 3.90 percentage points. It is worth noting that improved products above 130 square meters accounted for a total of 28.18%, a slight decrease of 0.08 percentage points from the previous year, which is basically the same as last year — against the backdrop of a sharp drop of 3.90 percentage points over the previous year in the proportion of 90㎡ or less, demand did not simply spill over to large apartments, but instead concentrated in the “functional improvement” range of 90-130 square meters. The total price constraint is still the core variable that determines the choice of apartment type.
Figure 4 Changes in the proportion of newly built commercial residential units sold by area in 15 key cities across the country from January 2025 to August 2026
Data source: CRIC China Real Estate Decision Consulting System.
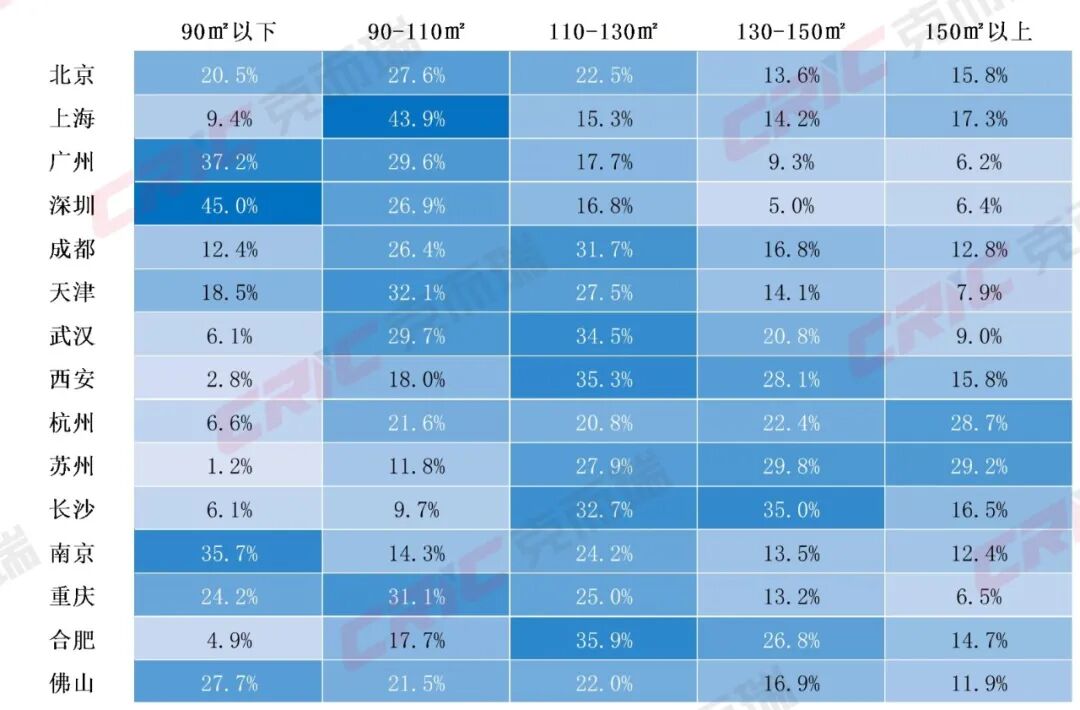
By city, there are large differences in the transaction structure of each area segment, and it is closely related to the city's energy level, housing price level, and supply and demand structure.
Among the first-tier cities, Shenzhen accounted for 44.97% of 90㎡ or less, Guangzhou was 37.19%, and Beijing was 20.52%, reflecting the characteristics of high housing price cities that just needed small apartments; Shanghai had an absolute main force of 90-110㎡ (43.94%), and demand for first reforms dominated, with over 150 square meters accounting for 17.25%, and high-end demand maintained a certain volume; it is worth noting that Nanjing's share of 90㎡ or less rose sharply to 35.68% in August (22.25% in July), and the characteristics of centralized release are obvious.
Among the strong second-tier cities, Suzhou accounts for 29.24%, and Hangzhou for 28.66%, and demand for high-end improvements is significantly higher than other cities, which is related to the concentration of high-net-worth people and sufficient supply of improved products; Changsha and Xi'an showed a clear preference for large apartments. 130-150 square meters in Changsha accounted for 35.04%, and Xi'an's 130-150 square meters and 150 square meters or more together accounted for 43.90%. Large apartment cost-effective products are the main force for local removal. In contrast, the structures of Chongqing (90-110 square meters account for 31.09%, 90 square meters or less account for 24.20%) and Tianjin (90-110 square meters account for 32.10%) are relatively small, and account for a higher proportion of immediate demand and initial purchase.
Table 2 Percentage of newly built commercial residential units sold by area in 15 key cities nationwide in August 2026
Data source: CRIC China Real Estate Decision Consulting System.
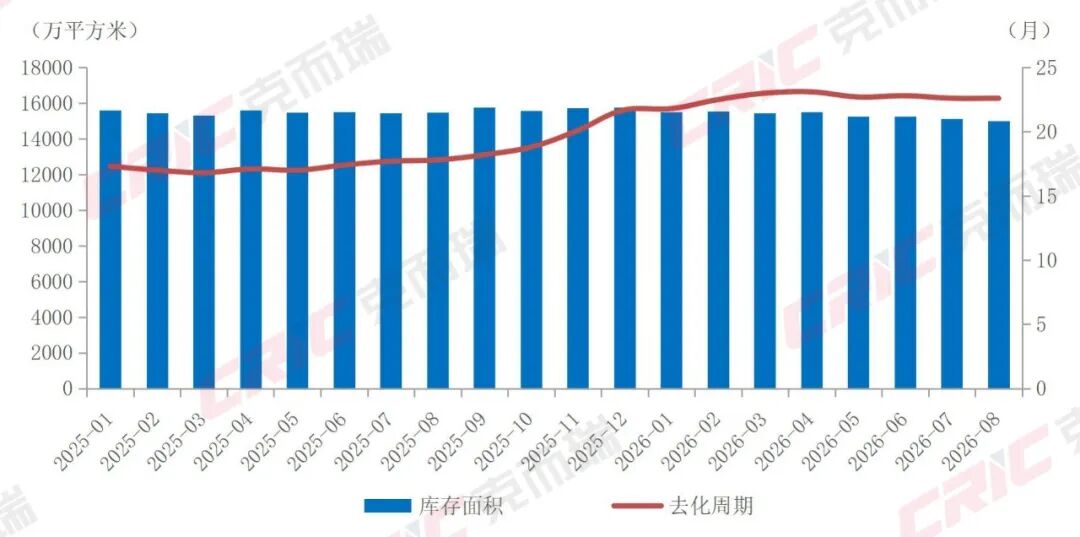
3. Inventory removal: Inventory fell four times month on month, and the removal cycle remained flat at a high level of 22.6 months
In August, the total inventory of newly built commercial residential homes in 15 cities continued to decline slightly, and the removal cycle remained flat at a high level. According to CRIC monitoring, as of the end of August, the inventory area of newly built commercial residential homes in 15 cities was 150,142 million square meters, down 0.71% from the previous year; due to the contraction in transactions, the removal cycle was 22.6 months, flat from month to month, 4.8 months longer than the same period last year (17.8 months). The decline in inventory mainly depended on low supply rather than transaction volume, and the downward pressure on supply and demand still existed.
Figure 5 Changes in the inventory and removal cycle of newly built commercial housing in 15 key cities across the country from January 2025 to August 2026
Data source: CRIC China Real Estate Decision Consulting System.
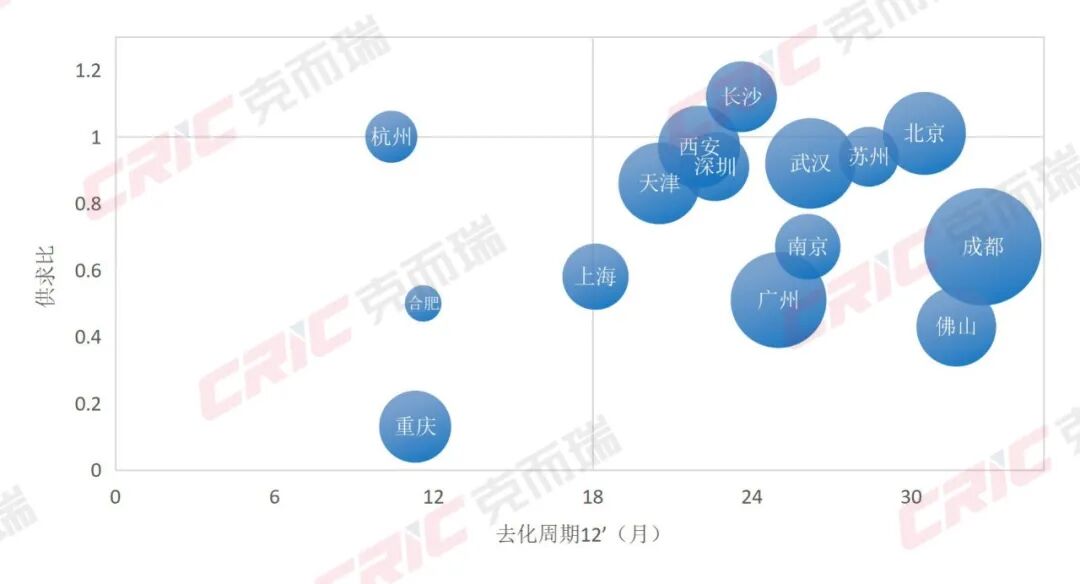
The de-fragmentation between cities is still significant. The decontamination cycle of Hangzhou (10.4 months), Chongqing (11.3 months), and Hefei (11.6 months) is below the 18-month warning line. Among them, Chongqing's August supply-demand ratio was only 0.13, and Hefei had the lowest inventory scale of 2,245,400 square meters in 15 cities. The supply contraction effect was most obvious; Shanghai, Tianjin, Xi'an, Shenzhen, Changsha, Nanjing, Wuhan, Guangzhou, Suzhou and other nine cities are in the 18-30 month decompression range; Beijing (30.5 months), and Foshan (31.7 months) and Chengdu (31.7 months) (32.7 months) Extraction cycles all exceeded In 30 months, the problem of inventory accumulation was quite prominent.
It is worth noting that Chengdu still ranked second among the 15 cities in August, but its inventory volume reached 23.2312 million square meters, the largest of the 15 cities. The removal cycle was as high as 32.7 months. The “high transaction and high inventory” coexistence pattern has not improved, and the supply backlog cannot be ignored. Foshan's inventory is 10.729 million square meters, and the removal cycle is 31.7 months. Demand support is weak due to the fact that the industrial population import falls short of expectations; Beijing has an inventory of 116.11,500 square meters and a removal cycle of 30.5 months. The inventory backlog in remote suburbs is still a major drag.
Figure 6 Cross-analysis of supply, demand and removal of newly built commercial housing in 15 key national cities in August 2026
Data source: CRIC China Real Estate Decision Consulting System.
Note: The bubble size represents the inventory area.
4. Project performance: Shanghai has 6 seats in the money list, and the distribution of cities in the area list tends to be balanced
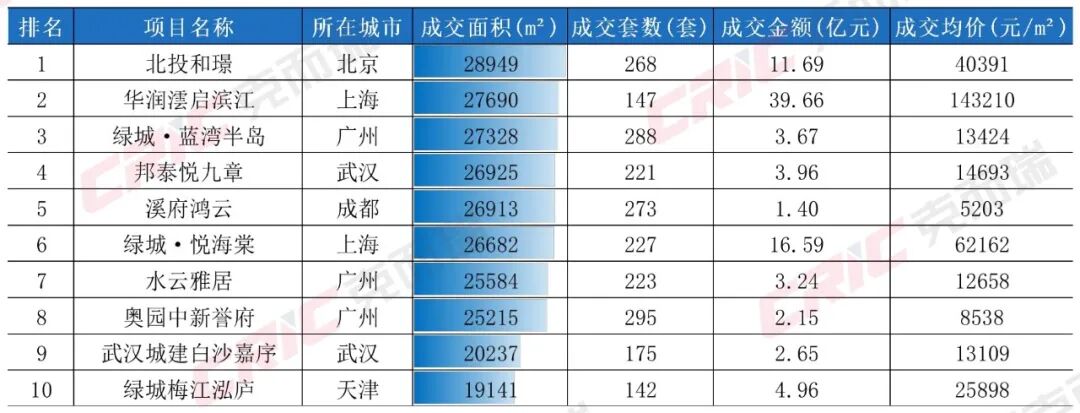
Judging from the top 10 projects with a transaction area, the city distribution of the leading projects is more balanced than in July, and Beijing, Shanghai, Han, and Rongjin have blossomed a bit more. Beijing's Beitou Hejing topped the list with 28,900 square meters, with an average transaction price of 40,391 yuan/square meter; Shanghai Huarun Qiqibinjiang ranked second with 27,700 square meters, with an average price of 14,3210 yuan/square meter, with both volume and price; Guangzhou's Greentown Blue Bay Peninsula, Wuhan Bangtaiyue Jiuzhang, and Chengdu Xifu Hongyun ranked three to five. Among them, Chengdu Xifu Hongyun had an average price of only 5,203 yuan/square meter, and the characteristics of the amount needed to move were remarkable. Chengdu, which had 3 seats in the July area list, was shortlisted for only 1 seat this month, and Guangzhou became the most shortlisted city with 3 seats.
Table 3 Top 10 sales area of newly built commercial residential projects in 15 key cities across the country in August 2026
Data source: CRIC China Real Estate Decision Consulting System.
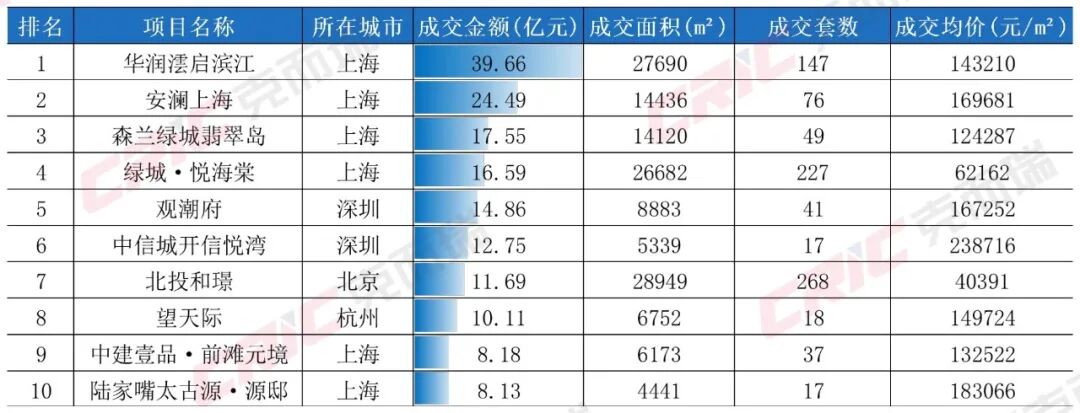
The top 10 turnover shows the ultimate “high-end improvement of core cities”. Shanghai has 6 seats, Shenzhen has 2 seats, and Beijing and Hangzhou each have 1 seat. At the top of the list was Shanghai Huarun Qijiang, with a transaction amount of 3,966 billion yuan, an average price of 14,3210 yuan/square meter; followed by Anlan Shanghai (2,449 billion yuan, average price 169,681 yuan/square meter) and Sunland Green City Emerald Island (1,755 billion yuan), followed by Shanghai's high-end market. In the TOP10, the average price of 8 seats exceeds 120,000 yuan/square meter, and the asset allocation needs of high-net-worth individuals continue to support the independent market in the high-end market in core cities; traders are still dominated by central enterprises and leading housing enterprises from China Resources Land, Zhonghai Real Estate, Greentown China, etc., and industry concentration continues to rise.
Table 4 Top 10 sales value of newly built commercial residential projects in 15 key cities nationwide in August 2026
Data source: CRIC China Real Estate Decision Consulting System.
The contrast between the area list and the price list was further widened: the TOP10 sold a total of 254,700 square meters, amounting to 8.997 billion yuan, with an average suite area of 112.73 square meters; the TOP10 sold a total of 143,500 square meters, amounting to 16.401 billion yuan, with an average apartment area of 159.94 square meters — the latter was less than 60% of the former, creating nearly double the amount. This comparison reflects the current polarization of the market: on the one hand, cities such as Wuhan and Chengdu rely on cost-effective projects to maintain the transaction scale, moving in volume but at low prices; on the other hand, Shanghai and Shenzhen rely on high-end improvement projects in core locations to contribute transaction amounts, which are expensive but low in volume.
Stock commodity housing market
In August, transactions fell 8.95% month-on-month, and the year-on-year increase narrowed to 6.23%.
1. Total transaction volume: Approximately 12.63 million square meters in August, maintaining positive year-on-year growth for five consecutive months
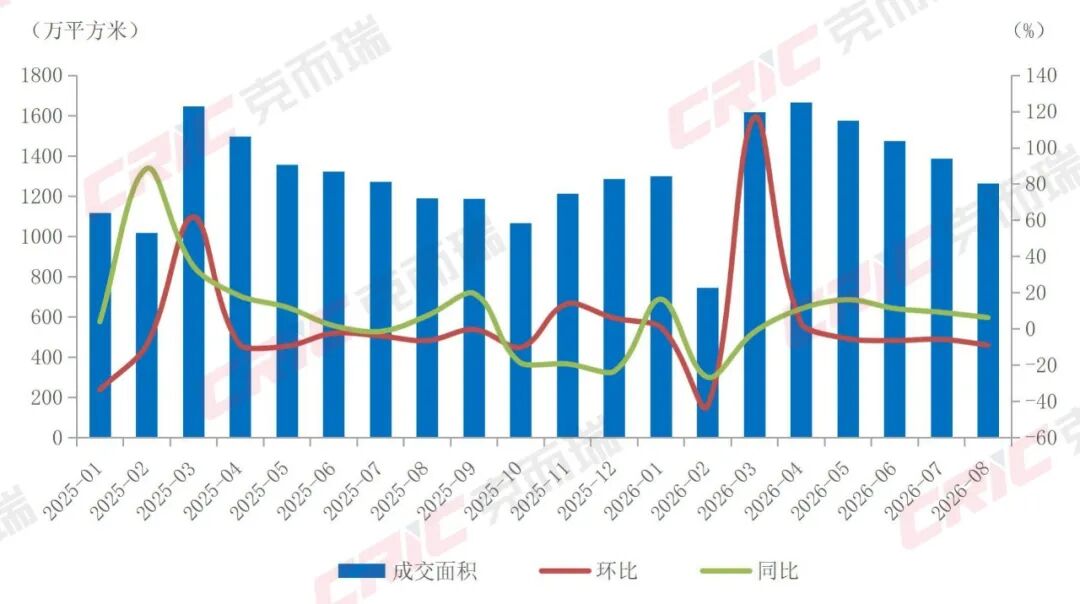
Affected by the traditional low season in August and the decline in demand-side sentiment, the total transaction area of second-hand housing in 14 key cities in August was 126.34,200 square meters, down 8.95% from the previous month, and the decline was 3.17 percentage points higher than in July; the year-on-year increase was still 6.23%, but the increase was 2.9 percentage points narrower than July, for the third consecutive month. In January-August, a total of 1102.181,000 square meters were sold, with a cumulative year-on-year increase of 5.8%, leading the way for new homes in terms of size and growth rate.
Judging from the quantitative energy trend, second-hand housing transactions declined month by month after rising to 16.6397 million square meters in April. However, the overall situation remained relatively high of 12 million square meters or more, about 2.3 times that of new homes in 15 cities, and the dominant position in the stock market was stable. The month-on-month decline widened in August, weakening at the same time as the new housing market, reflecting a marginal decline in overall demand-side sentiment, rather than second-hand housing being put under pressure alone.
Figure 7 Changes in second-hand housing transaction area in 14 key national cities from January 2025 to August 2026
Data source: CRIC China Real Estate Decision Consulting System.
2. City performance: Shanghai, Beijing, and Beijing are the largest, with Suzhou leading the year-on-year increase
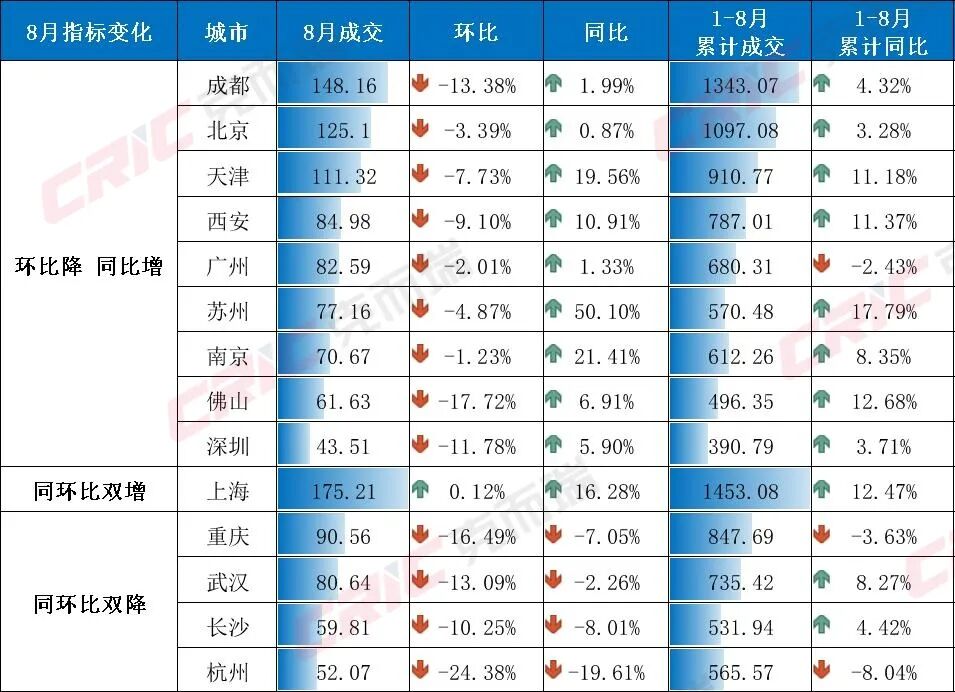
By city, in terms of transaction scale, Shanghai ranked first with 1.752,100 square meters, followed by Chengdu with 1.481,600 square meters. Beijing (1,251,000 square meters) and Tianjin (1,113,200 square meters) also maintained a scale of more than 1 million square meters, forming the four major highlands of “Shanghai, Rong, Beijing, and Tianjin.” It is followed by Chongqing (905,600 square meters) and Xi'an (849,800 square meters), and the overall scale hierarchy is stable.
In terms of year-over-year performance, 10 out of 14 cities achieved positive growth. Suzhou ranked first with a year-on-year increase of 50.10%, followed by Nanjing (+21.41%), Tianjin (+19.56%), Shanghai (+16.28%), Xi'an (+10.91%), etc., with an increase of more than 10%, and strong market recovery momentum; Hangzhou (-19.61%), Changsha (-8.01%), Chongqing (-7.05%), and Wuhan (-2.26%) fell year-on-year, with a cumulative year-on-year decline of 8.04% in January-August. The city with the weakest cumulative performance.
On a month-on-month basis, only Shanghai (+0.12%) achieved a slight month-on-month increase, while the remaining 13 cities all declined. Among them, cities such as Hangzhou (-24.38%), Foshan (-17.72%), Chongqing (-16.49%), and Chengdu (-13.38%) had the highest declines, while Suzhou (-4.87%), Beijing (-3.39%), Guangzhou (-2.01%), and Nanjing (-1.23%) showed relatively moderate declines.
Table 5 Changes in second-hand housing transaction area in 14 key cities across the country in August 2026 (unit: 10,000 square meters)
Data source: CRIC China Real Estate Decision Consulting System.
Future market outlook
As the off-season transitions to “gold, nine, silver, ten,” new housing transactions are expected to stabilize month-on-month.
Entering September, the traditional peak season of “gold, nine, silver, ten” is approaching. The supply-side is expected to expand moderately, driven by housing companies' sprint results for the third quarter. New housing transactions may be affected by marginal restoration due to the pace of promotion and policy expectations, but the extent of repair still depends on substantial improvement in demand-side confidence; demand for second-hand housing is expected to remain high, but it may continue to decline slightly from month to month. Overall, the pattern of “strong second-hand, weak new homes” is difficult to reverse in the short term, and the replacement chain continues to support the new housing improvement market.
The supply side is expected to pick up seasonally, but the trend of contraction is difficult to change. With the opening of the “Golden Nine” promotion window, housing companies' willingness to sell is expected to improve marginally, and cities such as Shanghai, Hangzhou, and Suzhou that have already converted centralized land supply volumes are more certain. However, against the backdrop of sales pressure and tight capital, the “determine production by sales” strategy of housing enterprises will continue. It is expected that supply will maintain negative year-on-year growth, and the supply-demand ratio is expected to remain in the 0.6-0.8 range. The pattern of supply over demand forms some support for inventory removal.
New housing transactions are expected to recover month-on-month, and the year-on-year decline is narrowing. The year-on-year decline in new housing transactions widened to 7.53% in August, mainly due to the combination of the off-season and shrinking supply. Entering September, as supply volume declines with the same period last year, compounded by the “Golden Nine, Silver, Ten” peak season and the New Deal expectations at the end of August, new housing transactions are expected to stabilize month-on-month in September, with a year-on-year decline or marginal narrowing.
Urban differentiation continues, and core first-tier and high-energy second-tier cities are relatively resilient. Cities such as Shanghai, Beijing, and Guangzhou have strong momentum for market restoration over the same period last year, and demand for high-end improvements is still supported; while cities with high inventories and removal cycles of more than 30 months, such as Chengdu and Foshan, supply contraction and demand adjustments may continue, and there is a lot of pressure to clear the market.
The second-hand housing market remains resilient, but momentum may be weakening marginally. The second-hand housing market has been growing for five consecutive months, but the month-on-month decline widened in August, and market momentum weakened. Second-hand housing transactions are expected to stabilize slightly in September with the peak season. The year-on-year increase may narrow to about 5%, and the dominant position in the stock market will not change.