
Camtek (CAMT) Stock May Be Overvalued On Its Sales Outlook
Camtek has had a powerful run over the past few years, yet a choppy recent stretch now raises a sharper question for investors about whether the current US$134.66 share price lines up with its sales. With momentum cooling in the short term but longer term returns still strong, the issue is what that combination really says about how the market is valuing the business today.
- Over the past 5 years the stock has returned 227.4%, which puts a lot of weight on whether the revenue base can support that kind of re-rating.
- The company’s value story now leans heavily on how efficiently it can convert its product demand into sustained sales and cash generation, since that underpins what investors are really paying for.
- There is a second opinion on Camtek worth weighing. See what analysts think Camtek's shares could be worth.
The stock’s next move may depend on whether Camtek’s current price can be squared with its sales when measured against the Fair Ratio benchmark.
If you want to test the same sales based valuation question beyond Camtek, you can compare it with a wider set of stocks using the 34 high quality undervalued stocks
Has Camtek Run Too Far on Sales?
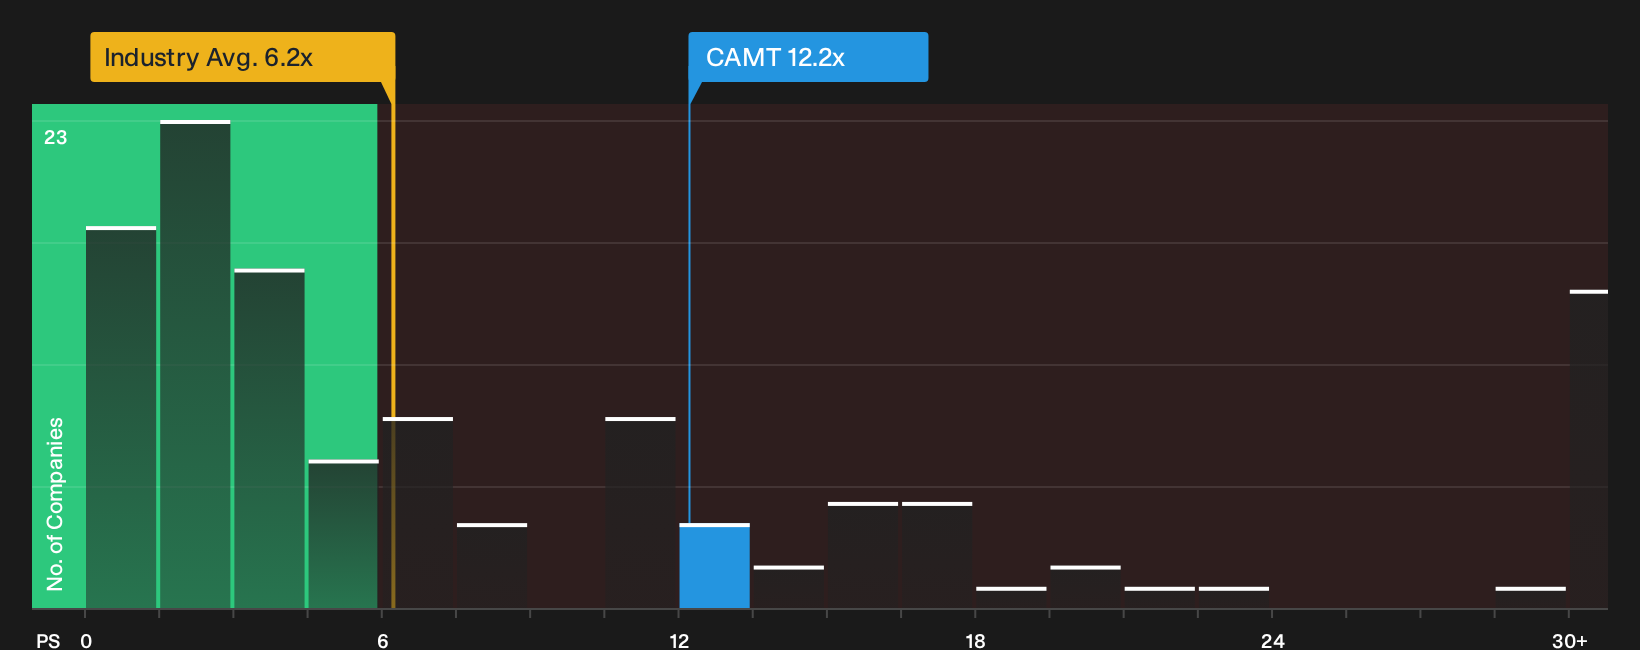
P/S fits Camtek well because investors often focus on revenue traction for semiconductor equipment companies when earnings can swing around investment cycles. On this measure, Camtek trades on a P/S of about 12.2x, which is roughly double the broader Semiconductor industry average near 6.2x and slightly below the peer group on roughly 13.5x. That places the stock in a premium zone versus the sector, even if it is not at the very top of its closer peer pack.
The Fair Ratio model, which looks at factors such as Camtek’s growth profile, margins, size and business risks, points to a materially lower P/S level than the one the market is paying today. The current multiple therefore sits above what that framework would suggest for the business and leans toward Camtek looking overvalued on sales compared with its own fundamentals. Investors weighing this will likely want to decide whether Camtek’s revenue quality and execution justify paying well ahead of that tailored benchmark before expecting further upside on this metric. Explore the numbers behind Camtek's P/S valuation.
The Camtek Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Camtek valuation puzzle leaves off by spelling out which growth, margin and earnings paths would need to play out for the stock to look materially higher or lower than today’s price. Each scenario links its number to a specific view on how Camtek’s expansion prospects, profitability and risk profile could evolve, giving you a reference point you can revisit as fresh information comes through.
One of the top community narratives on Camtek: 28% undervalued
"Accelerating demand for high-performance computing and AI-driven applications is expanding the need for advanced packaging, micro-bump and hybrid bonding inspection..."
Discover why this Narrative puts Camtek at 28% undervalued.
For Camtek, the share price is only one piece of the puzzle
Before you decide how to treat Camtek in your portfolio, it is worth asking who is actually steering the business and how their pay is structured, because those incentives can shape what happens next. See who runs Camtek and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com