
Carlyle (CG) Stock Still Looks Expensive After Its Sharp Pullback
Carlyle Group has seen its share price fall sharply this year, which puts a fresh spotlight on whether the current valuation lines up with the earnings power of the business. With a mixed share price record over different timeframes, investors are asking how much of Carlyle Group's earnings story is already reflected in today's price.
- Over the past 3 years the stock has gained about 39.5%. Anyone who has held through that period now has to decide how much of that journey is backed up by the underlying earnings profile.
- Recent focus on artificial intelligence across Carlyle's portfolio and credit activities, from the Exiger investment to work in AI driven debt markets, can influence how investors think about future fee income, operating efficiency and the durability of earnings.
- Your read on Carlyle Group is one view; the desks covering it have another. See what analysts think Carlyle Group's shares could be worth.
The issue now is whether Carlyle Group's current share price, after its recent pullback, is appropriately supported by the earnings it is generating and expected to generate.
If the recent slide in Carlyle Group has you rethinking how much you want to pay for earnings exposure tied to AI and credit, a focused screen of 32 AI small caps.
Has Carlyle Group Run Too Far on Earnings?
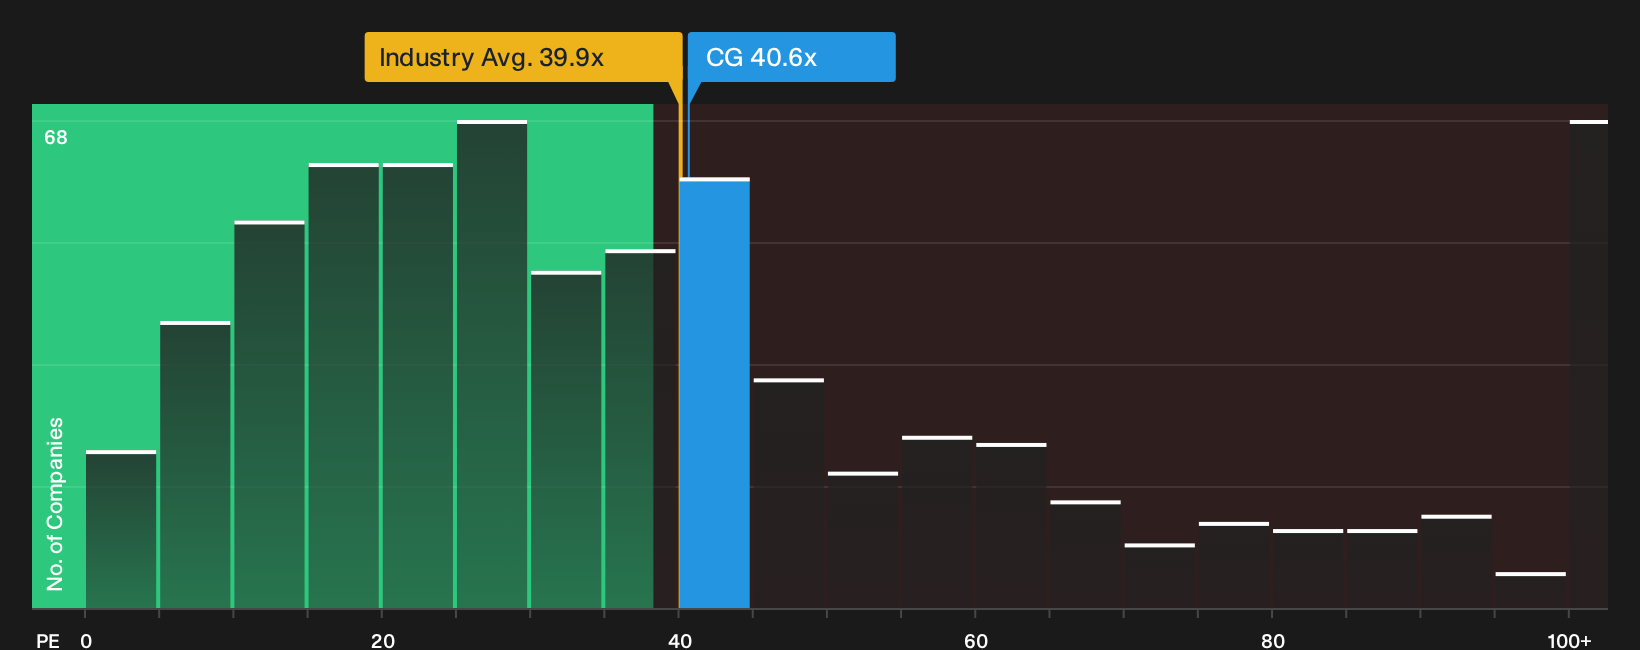
The P/E ratio suits Carlyle Group because earnings are a central yardstick for how investors value fee based asset managers. Carlyle Group trades on a P/E of 40.6x, which is slightly above the capital markets industry average of about 39.9x and also above the peer group at roughly 34.3x. That puts the stock on a richer earnings tag than many comparable platforms, even before considering its specific mix of private equity, credit and AI related initiatives across the portfolio.
The fair multiple implied by the excess returns workup is lower than where Carlyle Group trades today, so the current P/E sits on the expensive side of what that tailored model suggests for its growth, profitability and risk profile. Because the company has been pushing hard into AI partnerships such as the Exiger platform and the MIT collaboration, the premium earnings multiple appears tied to investor willingness to pay more for those potential fee streams and efficiency gains rather than to any discount signal. This leaves the stock screening as overvalued on P/E terms relative to its modeled fair ratio. Explore the numbers behind Carlyle Group's P/E valuation.
The Carlyle Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Carlyle Group pick up where this valuation puzzle leaves off by spelling out which paths for growth, margins and earnings would need to hold for the stock to be worth materially more or less than today. Each scenario focuses less on a single P/E or model output and more on the underlying assumptions that drive its fair value view, so you can later compare those expectations with the financial results as they arrive on Simply Wall St's Community page.
One of the top community narratives on Carlyle Group: 43% undervalued
"Carlyle's recent implementation of a $1.4 billion share repurchase authorization reflects management's belief that their share price is undervalued..."
Discover why this Narrative puts Carlyle Group at 43% undervalued.
Before acting on Carlyle Group's valuation, there is another piece of the puzzle
Price multiples and growth stories only tell part of what you need to know about Carlyle Group, because recent research has also highlighted specific risk checks that could shift how you frame the opportunity. Take a closer look at 5 warning signs (3 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com