
Cementir Holding (BIT:CEM) Stock Still Looks Reasonable On Its 92% Run
Cementir Holding has seen its share price pull back in recent months after a strong multi‑year run, which puts fresh attention on what investors are paying for its earnings today. With the stock now around €13.66, the key issue is how that market value lines up with the profit the business is generating.
- Over the past 3 years the share price has gained about 92.2%, which now puts that earlier upswing in the spotlight when judging what its current earnings are worth.
- The group’s ability to convert operating profit into cash and manage capital spending can shape how much of its earnings ultimately support shareholder value over time.
- There is a second opinion on Cementir Holding worth weighing. See what analysts think Cementir Holding's shares could be worth.
The issue now is whether Cementir Holding’s current share price is adequately supported by its earnings profile.
If you are reassessing Cementir Holding on its earnings profile and want other ideas built on valuation criteria, a focused stock screen of 195 high quality undervalued stocks can be a useful second step.
Does Cementir Holding Look Undervalued on Earnings?
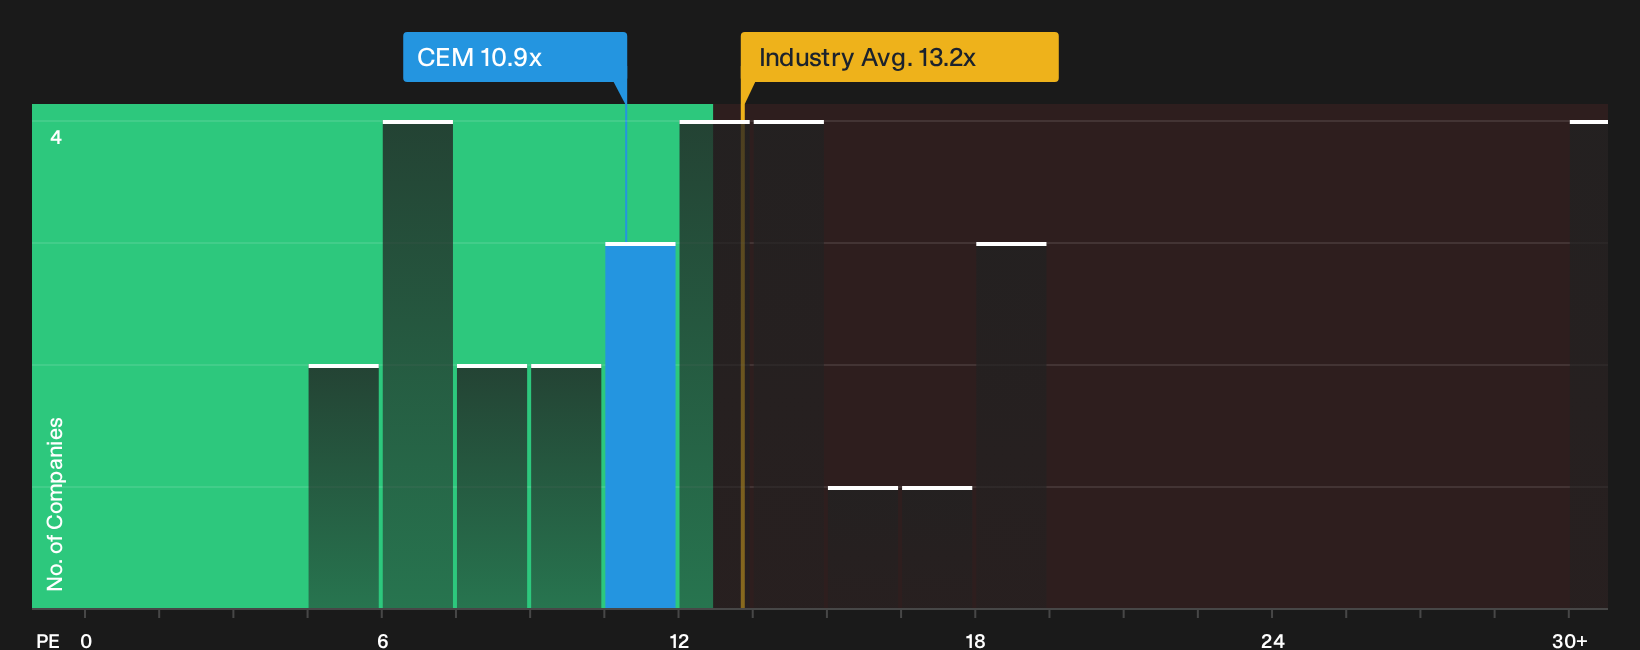
The P/E ratio works well for Cementir Holding because earnings are a key anchor for how investors judge a mature industrial group. On this measure, the stock trades on about 10.9x, which is lower than the Basic Materials sector average of roughly 14.4x and also below a peer group average of about 14.4x.
The tailored fair multiple, which adjusts for Cementir Holding’s own growth prospects, profitability and risk profile, is above the current 10.9x level. This places the shares below what this framework would expect investors to pay for the company’s earnings in relation to similar businesses. For anyone weighing Cementir Holding on earnings alone, the gap between its current P/E and this fair benchmark is the key question to work through. Explore the numbers behind Cementir Holding's P/E valuation.
The Cementir Holding Narrative: What Would Justify Today's Price?
Narratives for Cementir Holding pick up where the P/E question leaves off by spelling out which specific paths for future growth, profitability and earnings would need to play out for the current share price to look materially higher or lower. Each scenario links its implied valuation back to a clear view on how Cementir Holding's growth, margins and risk profile might evolve, which gives you something concrete to revisit as new information comes through on the Community page.
One of the top community narratives on Cementir Holding: 32% undervalued
"The company is progressing on carbon capture and lower CO2 cement products, including the ACCSION CCS project in Denmark backed by a €220 million grant…"
Discover why this Narrative puts Cementir Holding at 32% undervalued.
One more angle on Cementir Holding that many investors check
Cementir Holding’s current valuation tells only part of the story, because analyst models sketch out where earnings and profits might sit a few years from now and give you another reference point to compare with today. Explore where analysts expect Cementir Holding to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com