
Is Boot Barn Holdings (BOOT) Cheap As Conference Optimism Meets Mixed Guidance?
Boot Barn Holdings (BOOT) is back in the spotlight after management used two high profile retail conferences in mid September to highlight improving sales trends and a more confident outlook for the current quarter.
Recent pricing tells a different story to the upbeat conference tone. Boot Barn Holdings’ share price has fallen 21.4% over the past 30 days and is down 31.22% year to date, while the 3 year total shareholder return of 52.03% and 5 year total shareholder return of 41.75% show longer term holders are still ahead overall. This suggests near term momentum has cooled even as the broader multi year payoff remains positive.
Spot shifting sentiment around Boot Barn Holdings against other retailers by scanning our hand picked 34 high quality undervalued stocks, which now shows weaker momentum but potentially stronger fundamentals than the recent price action suggests.That selloff now pits a weaker share price against a retailer still talking up sales and guidance. For Boot Barn Holdings, does that mix still tilt the risk reward toward buyers once valuation is on the table?
Most Popular Narrative: 43% Undervalued
On the most followed view, Boot Barn Holdings screens as undervalued, with a fair value of about $225 per share set against the recent $128.37 close, which puts the conference optimism in a different light for anyone weighing the recent drawdown.
Robust store expansion into underpenetrated markets, particularly in population-growing regions, is driving higher-than-expected new store performance, strong customer acquisition, and increased sales productivity. This expansion provides an ongoing tailwind for revenue and positions Boot Barn to benefit from broader demographic shifts, supporting long-term top-line growth.
See why 11 investors see Boot Barn Holdings as 43% undervalued.
Result: Fair Value of $225.14 (UNDERVALUED)
Still, the bullish Boot Barn Holdings story leans heavily on rapid store expansion and steady demand for western and workwear, which could both crack if tastes or traffic shift.
Find out about the key risks to this Boot Barn Holdings narrative.
Another View: Boot Barn Holdings On Earnings Multiples
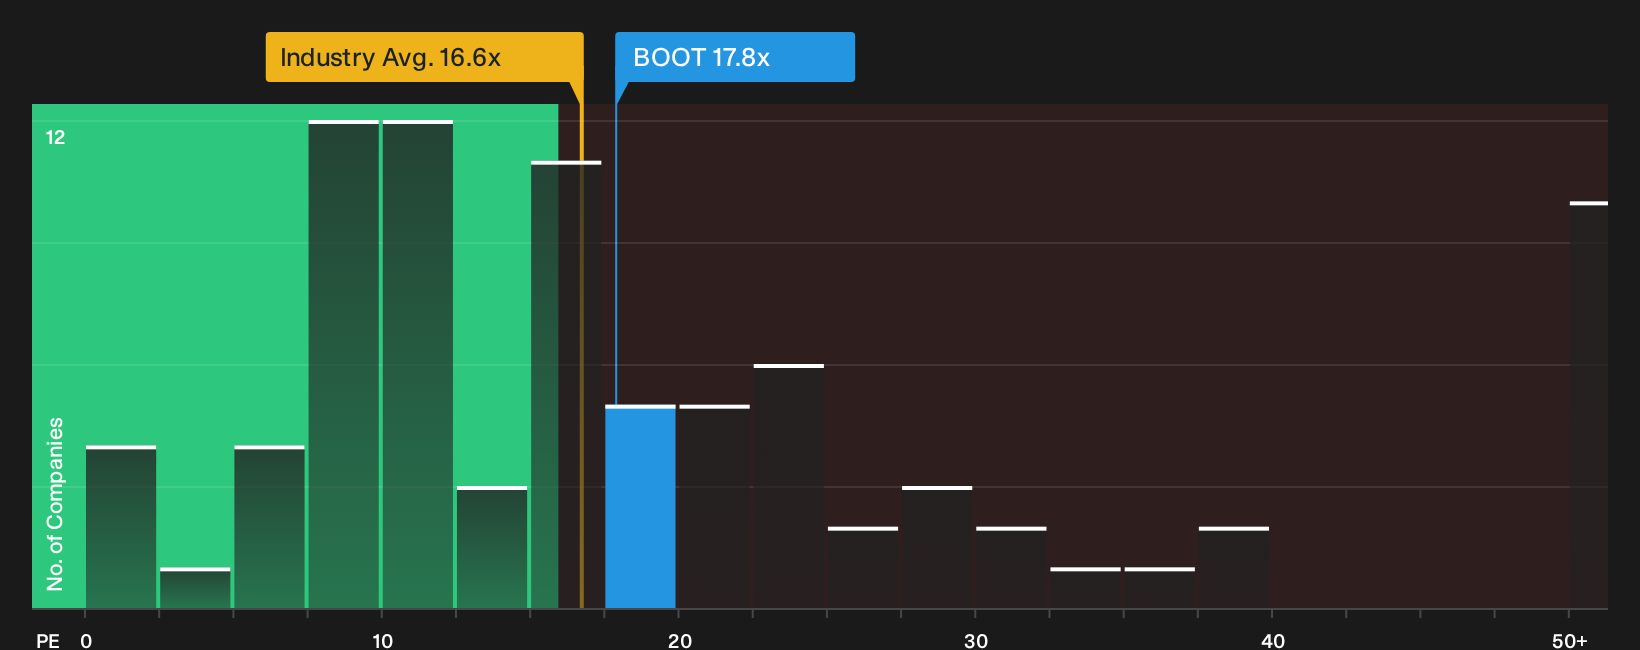
The story looks very different once Boot Barn Holdings is valued on its current P/E of 16x. That level is almost in line with its own fair ratio of 15.9x and close to the US Specialty Retail industry on 16.6x, which points to a stock that now prices in far less of a discount than the 43% undervalued narrative implies.
From this perspective, investors are paying a richer multiple than immediate peers yet only a fraction below the fair ratio, so the upside case leans more on execution and sentiment than on a clear cut bargain. The key question is whether that trade off feels comfortable enough for fresh money at today’s $128.37 level or not.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Boot Barn Holdings is clearly split, so move quickly to review the underlying numbers, pressure test the bullish points and weigh up the 4 key rewards.
Looking for more Boot Barn Holdings style investment ideas?
If Boot Barn Holdings has your attention, do not stop here. Fresh opportunities rarely wait and broadening your watchlist now can sharpen every decision.
- Target resilient income streams by scanning companies in the 6 dividend fortresses that prioritise consistent payouts alongside solid fundamentals.
- Hunt for quality at a discount using the 16 high quality undiscovered gems that surfaces lesser known businesses with strong financial profiles.
- Reduce portfolio stress by focusing on the 11 resilient stocks with low risk scores that highlights stocks with more robust balance sheets and lower risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com